 | ||
| 17th November 2026 | view in browser | ||
| Dollar has the bid, tech has the burden of proof | ||
| Markets head into Tuesday with the dollar firm and Wall Street looking for its footing as US retail sales test Fed rate-hike expectations and Nvidia earnings put AI sentiment back in focus. | ||
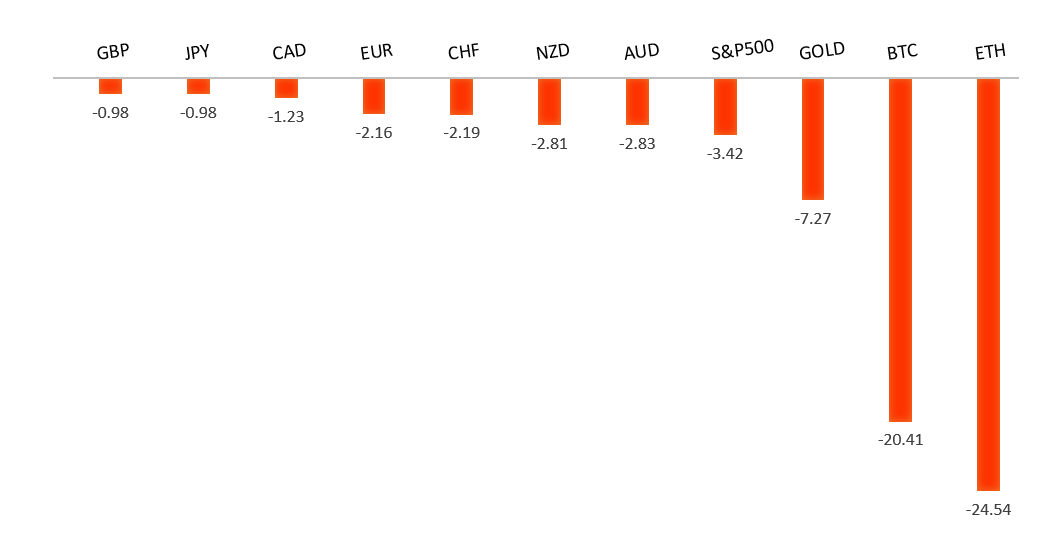
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
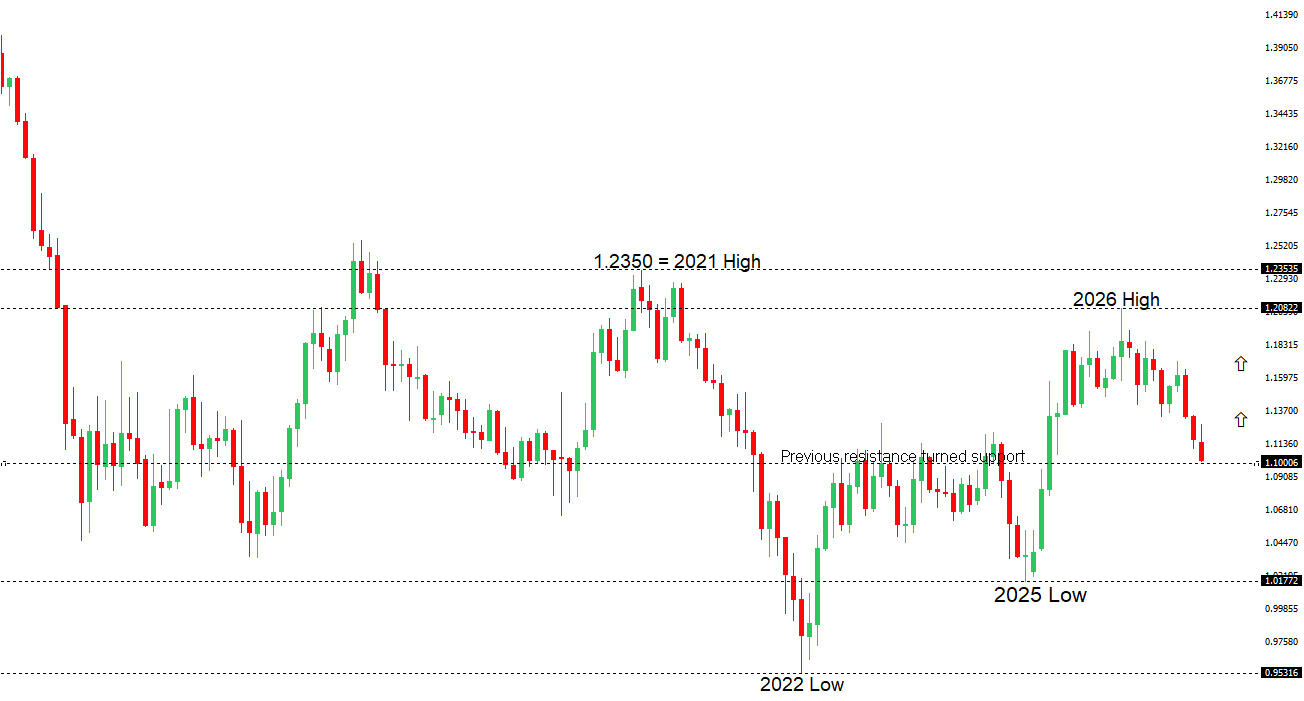 | ||
| R2 1.1103 - 12 November high - Medium R1 1.1073 - 13 November high - Medium S1 1.0985 - 17 November/2026 low - Strong S2 1.0900 - Figure - Medium | ||
| EURUSD: fundamental overview | ||
| The euro is struggling below 1.1000 against the dollar, near its weakest levels since May 2025, as hotter-than-expected US inflation, resilient jobs data, and hawkish Fed commentary reinforce expectations for a December rate hike. Persistent Middle East tensions are adding to safe-haven demand for the dollar. In Europe, French political gridlock, missed deficit targets, and mounting sovereign debt concerns are blunting the support the euro might otherwise draw from growing expectations for further ECB tightening. US retail sales are the next test of whether resilient domestic demand can sustain the dollar’s momentum. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
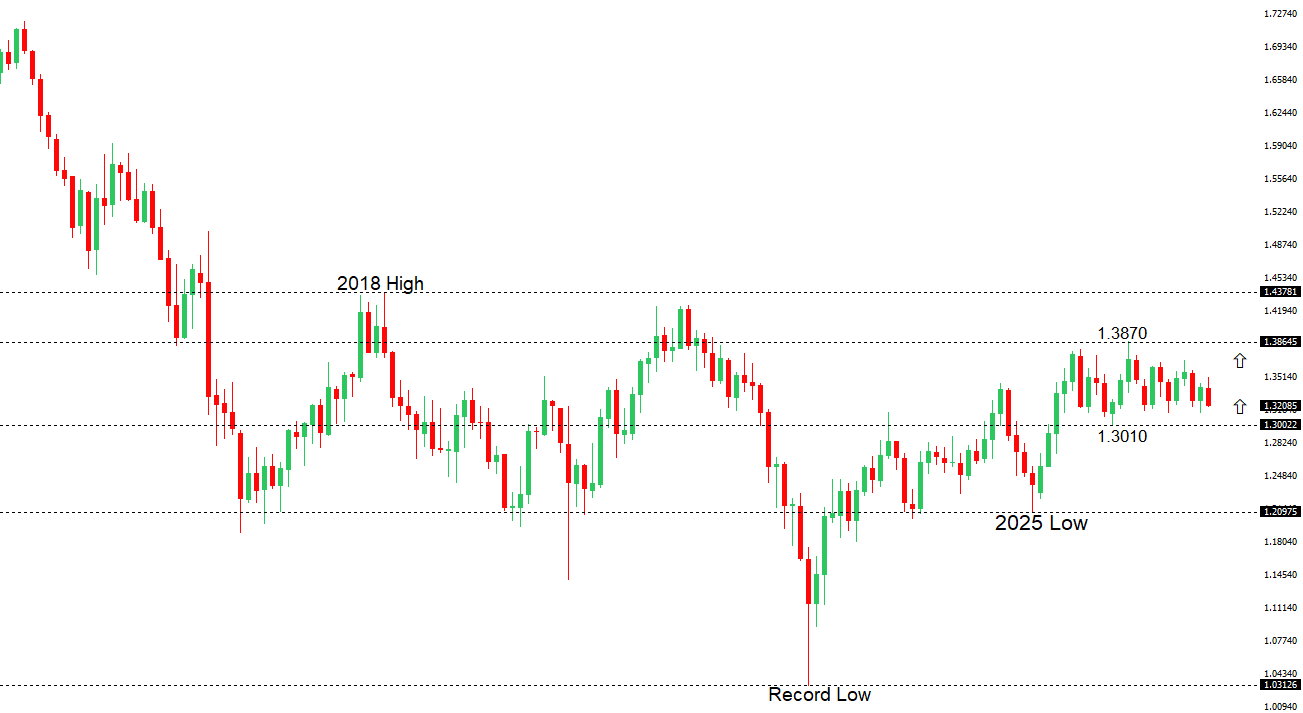 | ||
| R2 1.3419 - 22 October high - Medium R1 1.3356 - 11 November high - Medium S1 1.3169 - 17 November low - Medium S2 1.3137 - 14 October/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound has edged higher from a one-month low against the dollar as the greenback pulls back from a 19-month high, with traders looking to UK jobs and inflation data for the next steer on Bank of England policy. The jobs report is expected to show unemployment holding at 4.7% and regular pay growth easing to 3.6%, leaving Wednesday’s inflation print as the next test of expectations for a December BoE hike. Sterling’s rebound remains modest, with sticky US inflation and hawkish Fed commentary driving markets to fully price in a December rate hike, while Middle East tensions continue to support demand for the dollar. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would to put in a weekly close back above 160.00 to take the immediate pressure off the downside. | ||
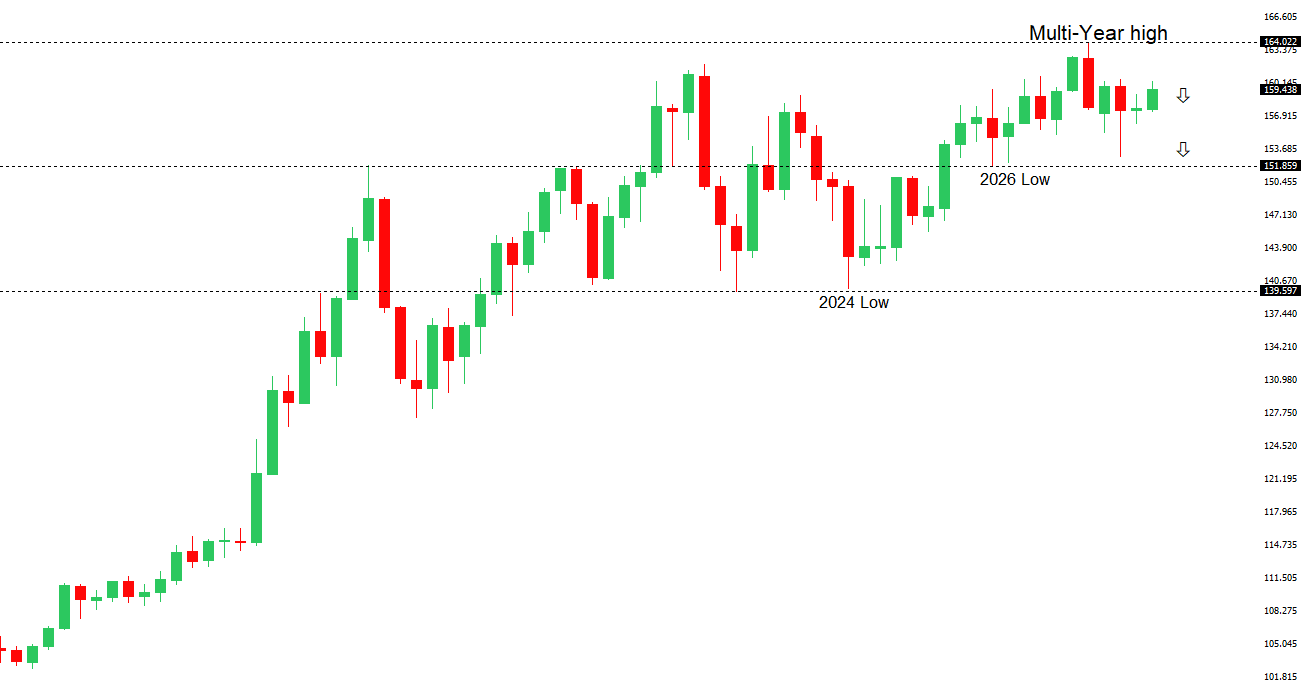 | ||
| R2 160.40 - 2 September high - Strong R1 160.19 - 13 November high - Medium S1 158.66 - 11 November low - Medium S2 156.96 - 30 October low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen has firmed modestly, with renewed intervention warnings from Japan’s finance ministry and safe-haven demand amid weakness in AI stocks making traders more reluctant to add to yen shorts. Japan’s economy stalled in the third quarter and household consumption fell for a second straight quarter, strengthening the case for gradual Bank of Japan tightening. BOJ board member Takata nevertheless kept the door open to further hikes, warning that a weak yen could amplify inflation and stressing that the pace would depend on the data. For now, the wide US–Japan yield gap remains a headwind for the yen, with a quarter-point Fed hike in December nearly fully priced and US retail sales the next test for the dollar. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
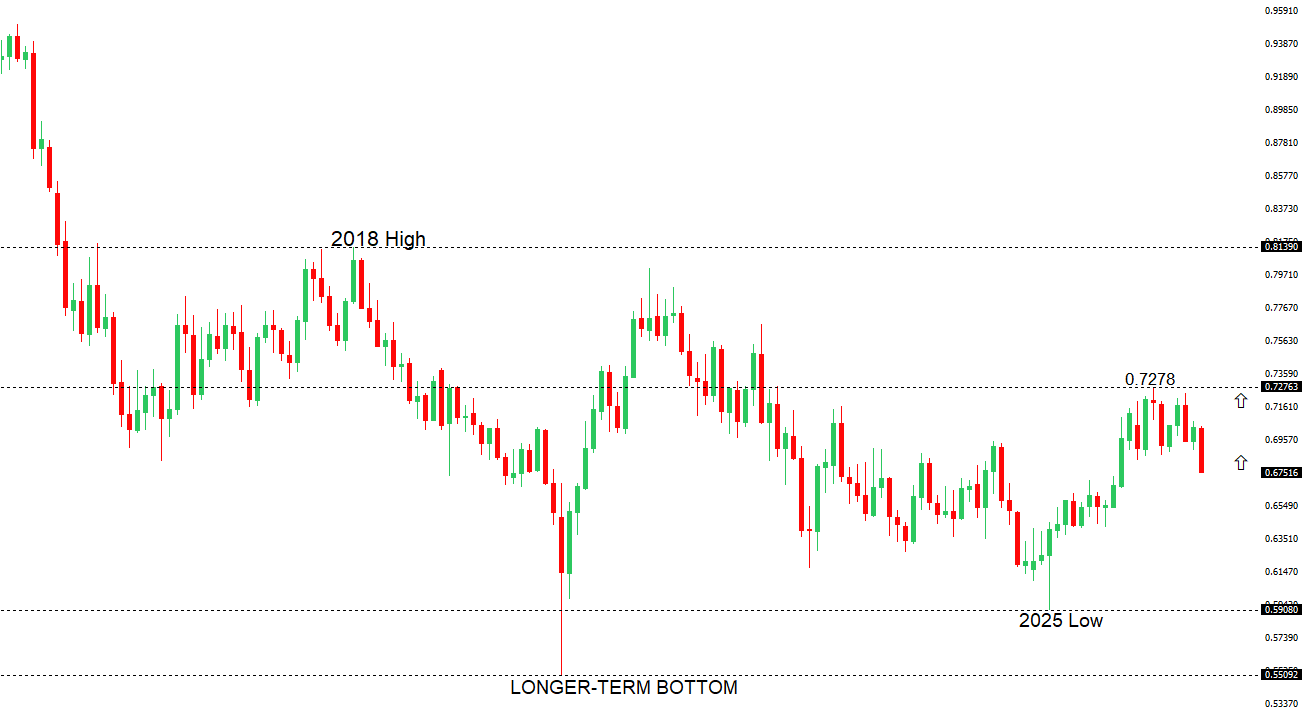 | ||
| R2 0.6886 - 11 November high - Medium R1 0.6815 - 13 November high - Medium S1 0.6727 - 17 November low - Medium S2 0.6663 - 5 January/2026 low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar slipped below 0.6750 and remains near its weakest levels since January as hawkish Fed expectations and slowing Chinese growth outweigh support from the RBA’s latest rate hike. The RBA minutes showed that policymakers were more concerned about leaving policy too loose as inflation risks rose, while Governor Bullock flagged the risk that oil prices stay elevated. The board signaled it would assess incoming data before deciding its next move. In the US, hotter inflation and Fed official Hammack’s warning that price pressures are broadening have reinforced expectations of a December rate hike, keeping the US dollar supported ahead of October retail sales. Softer Chinese growth has added to the pressure on the Aussie, which has been the weakest G10 currency this month. | ||
| Suggested reading | ||
| Trump loses. European populism lives on, M. Wolf, Financial Times (November 16, 2026) A Layman Thinks About AI, H. Marks, Oaktree Capital (November 11, 2026) | ||