 | ||
| 29th October 2026 | view in browser | ||
| Fed holds ground, dollar loses footing | ||
| Global markets head into Thursday digesting a Fed decision that offered little in the way of surprises, with the dollar losing some ground, equities holding up, and attention shifting to upcoming central bank decisions and corporate earnings. | ||
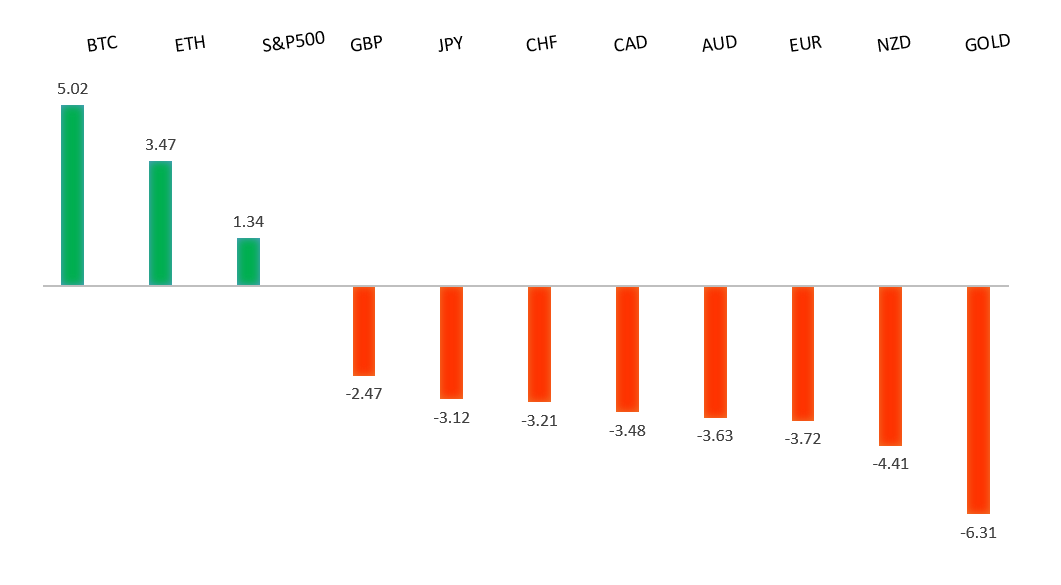
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
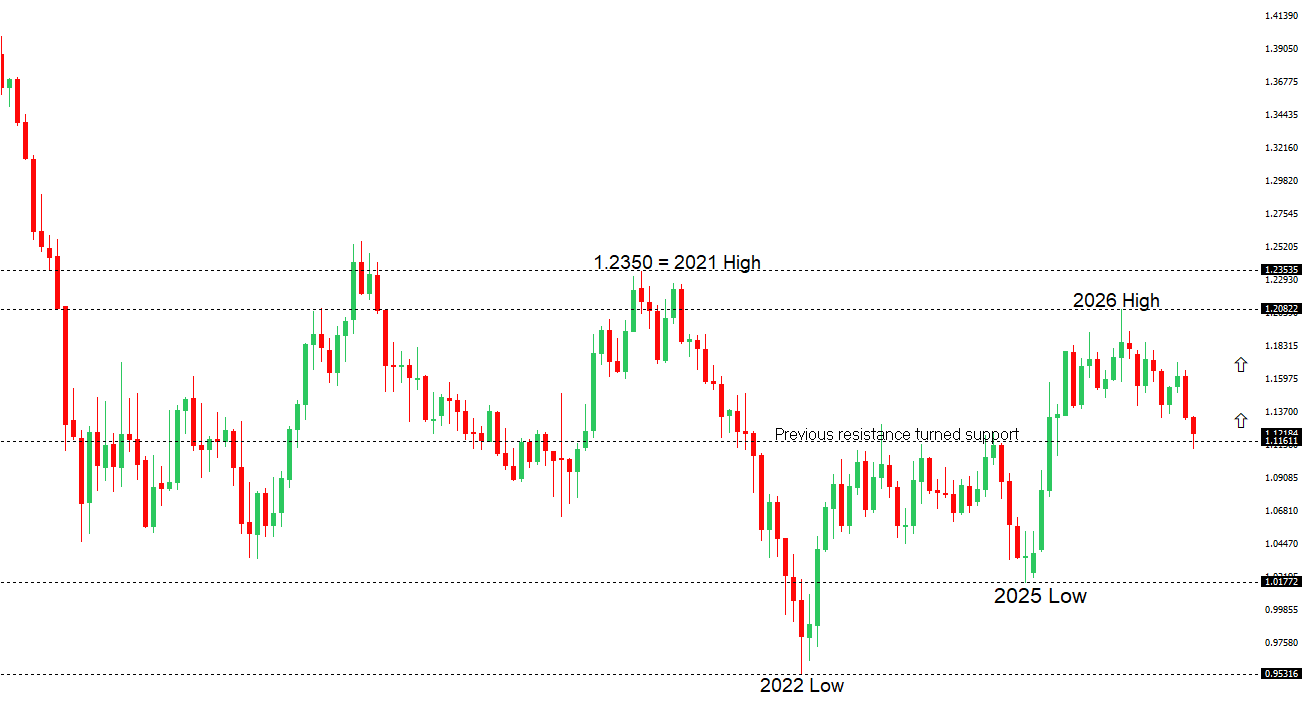 | ||
| R2 1.1270 - 16 October high - Strong R1 1.1200 - Figure - Medium S1 1.1113 - 14 October/2026 low - Strong S2 1.1100 - Figure - Medium | ||
| EURUSD: fundamental overview | ||
| The euro has found renewed demand against the US dollar, recovering from recent weakness as markets respond to a Federal Reserve decision that offered little in the way of additional hawkish surprises. While the Fed continues to signal that further tightening remains possible, Chair Warsh’s acknowledgment that restrictive policy is beginning to deliver results has encouraged some dollar profit-taking, reinforcing the view that much of the hawkish outlook is already reflected in market pricing. On the European side, attention now shifts to Thursday’s ECB decision, where policymakers are widely expected to maintain a cautious approach as they balance inflation risks against a still-fragile growth outlook. Political and fiscal uncertainty in France remains an underlying headwind for the single currency, though the immediate focus is on whether President Lagarde offers any meaningful shift in the ECB’s policy guidance. Looking ahead, upcoming eurozone growth figures and key US inflation and activity data should help shape expectations for the next phase of monetary policy divergence, with the euro potentially benefiting if markets begin to reassess the extent of additional Fed tightening. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
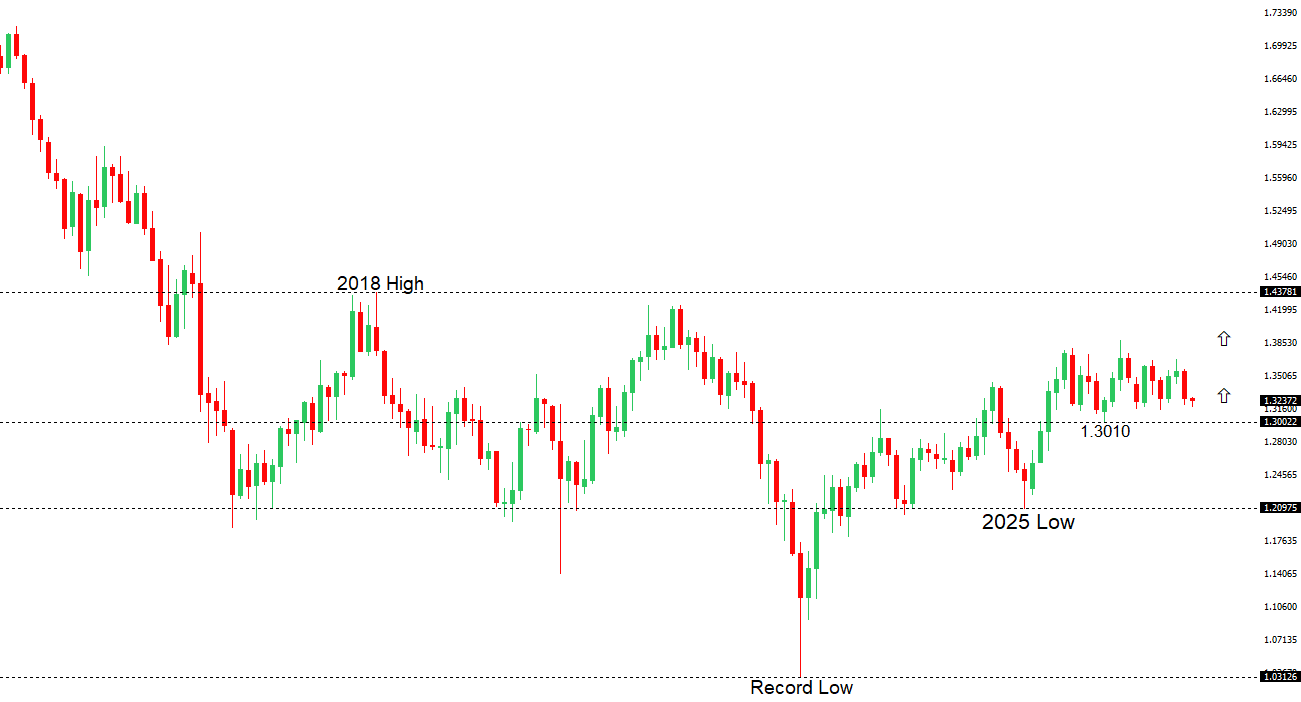 | ||
| R2 1.3498 - 16 September high - Medium R1 1.3420 - 22 October high - Medium S1 1.3272 - 28 October low - Medium S2 1.3137 - 14 October/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound has managed to recover some ground against the US dollar, with the latest Federal Reserve decision offering little in the way of a fresh catalyst for dollar strength. Although Fed Chair Kevin Warsh maintained his commitment to price stability and acknowledged continued economic resilience, the decision to leave rates unchanged reinforced the view that much of the hawkish outlook has already been priced in. On the domestic front, sterling continues to contend with expectations for a cautious Bank of England, as policymakers balance persistent inflation pressures against a softer growth outlook and signs of cooling in the labor market. Meanwhile, uncertainty surrounding the UK fiscal outlook and the upcoming Autumn Budget remains an additional source of caution. For now, the pound’s direction remains heavily influenced by broader dollar sentiment, with scope for further recovery should markets begin to reassess the extent of additional Fed tightening. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
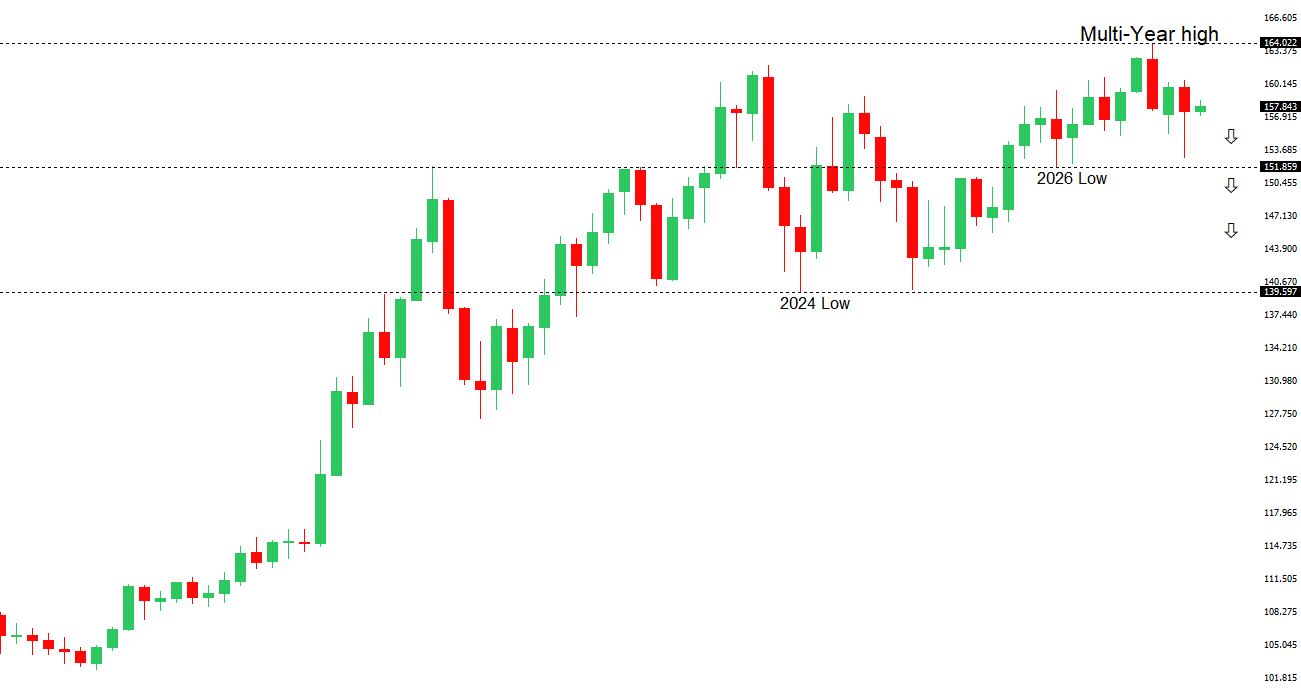 | ||
| R2 159.04 - 24 September high - Strong R1 158.35 - 28 October high - Medium S1 156.07 - 23 October low - Medium S2 155.29 - 4 September low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen has managed a modest recovery against the US dollar, though the broader fundamental backdrop remains challenging as markets digest the Federal Reserve’s latest policy decision and look ahead to the Bank of Japan. The Fed’s decision to leave rates unchanged, despite two officials favoring additional tightening, has offered the yen some relief, with Chair Kevin Warsh reaffirming the central bank’s commitment to bringing inflation back to target while acknowledging continued economic resilience. Still, the significant yield advantage enjoyed by the dollar remains a key headwind for the Japanese currency, particularly as investors question how aggressively the BOJ will be prepared to normalize policy. With USDJPY trading near levels that have historically raised concerns among Japanese authorities, the threat of official intervention also remains a consideration. Attention now turns to the BOJ’s policy decision and guidance, with any indication of a more determined tightening path potentially providing the yen with additional support. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
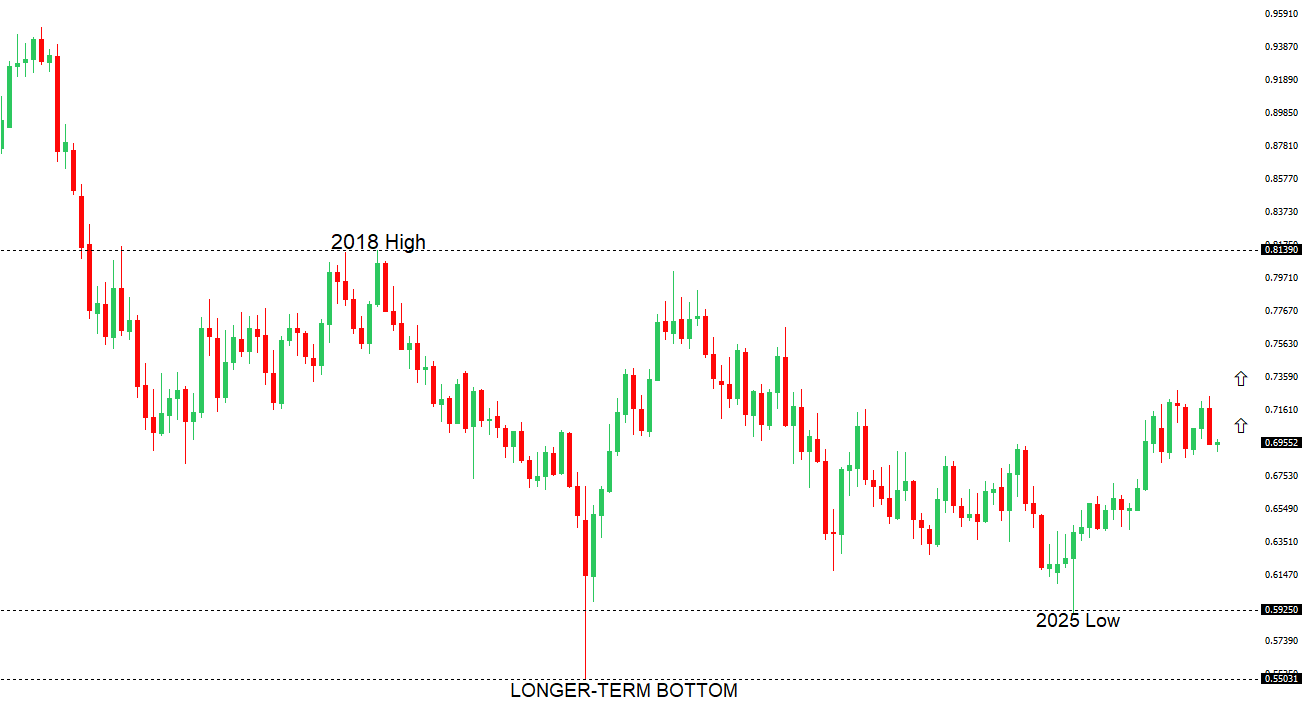 | ||
| R2 0.7100 - Figure - Medium R1 0.7065 - 28 October high - Medium S1 0.6970 - 20 October low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian Dollar has extended its recovery to a fresh one-month high, supported by a combination of domestic monetary policy expectations and renewed US Dollar weakness. Australia’s latest hotter-than-expected inflation data has reinforced expectations that the Reserve Bank of Australia may need to maintain a restrictive policy stance or consider additional tightening, providing an important source of support for the currency. Meanwhile, the Federal Reserve’s decision to leave rates unchanged, despite two officials favoring a hike, has weighed on the US Dollar, with markets seemingly finding little in Chair Warsh’s comments to justify a further hawkish repricing. The resulting improvement in risk sentiment has added to demand for the higher-beta Australian Dollar, with the divergence between a potentially more hawkish RBA and a Fed that may already have much of its hawkish outlook priced in continuing to favor the Aussie. | ||
| Suggested reading | ||
| Can local communities reinvent the UK high street?, L. Onita, Financial Times(October 28, 2026) The Fed’s New Worry: What If The AI Boom Goes Bust?, V. Guida, Alhambra (October 28, 2026) | ||