 | ||
| 2nd November 2026 | view in browser | ||
| A relief rally with a long guest list of risks | ||
| Markets open the week attempting a cautious recovery as hopes for Middle East diplomacy ease oil prices, while US elections, technology earnings and interest-rate uncertainty keep investors on edge. | ||
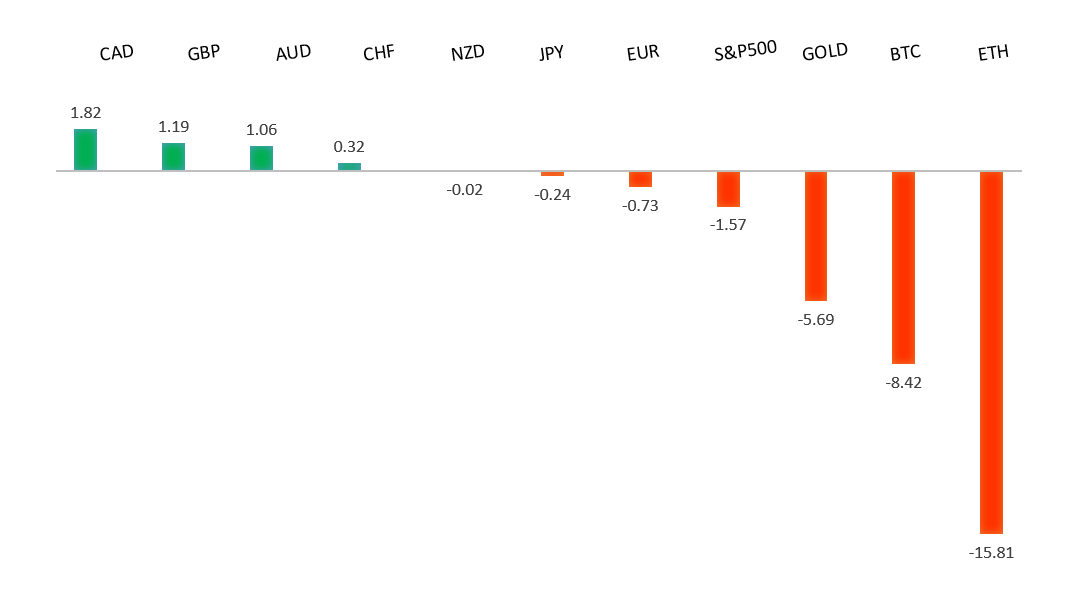
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
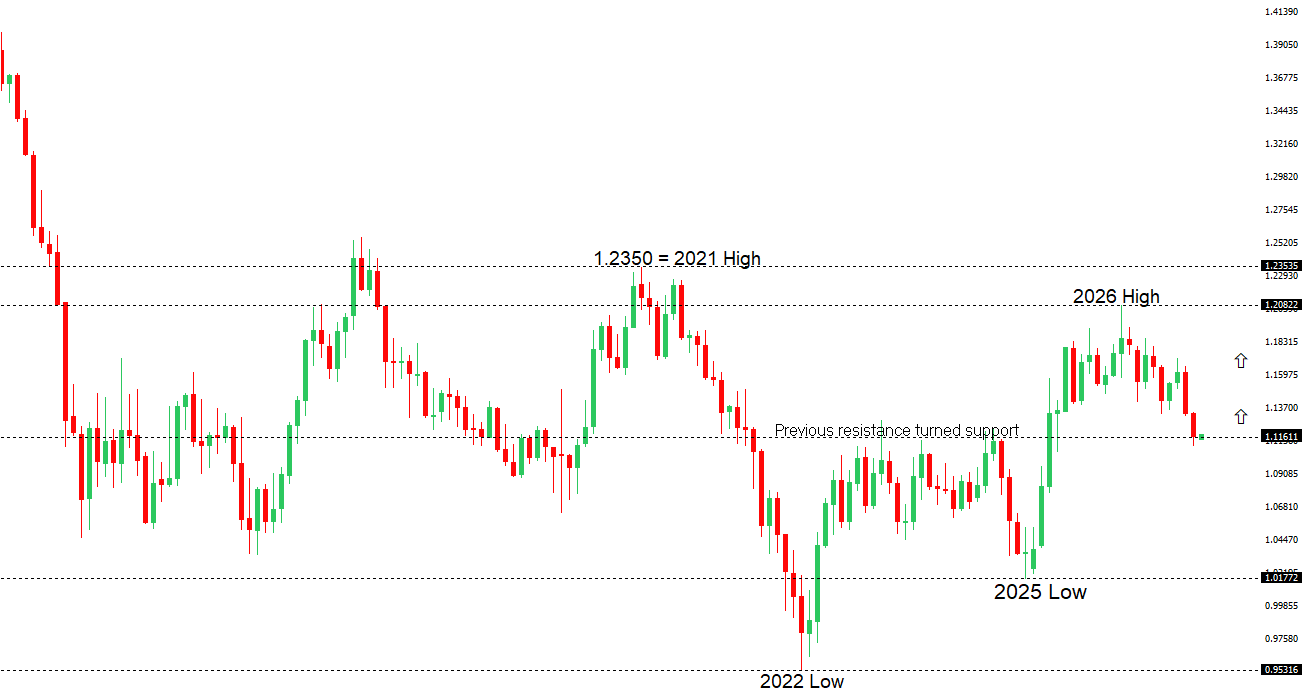 | ||
| R2 1.1270 - 16 October high - Strong R1 1.1215 - 30 October high - Medium S1 1.1136 - 30 October low - Medium S2 1.1104 - 29 October/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro is drawing support from stronger-than-expected Eurozone growth and persistent inflation risks, reinforcing expectations that the ECB could raise rates again in December. Resilience in Germany and Spain has helped offset weakness in France, suggesting the regional economy is weathering elevated energy costs better than feared. Hawkish comments from Bundesbank President Nagel have further supported the single currency, keeping additional tightening firmly on the table and limiting the prospect of a wider policy gap with the Fed. However, France’s fiscal and political difficulties remain a headwind, with Fitch’s negative outlook revision highlighting concerns over debt sustainability. Attention now turns to German retail sales, US manufacturing data and Tuesday’s US midterm elections, which could influence the dollar through shifts in expectations for fiscal policy and the broader economic outlook. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
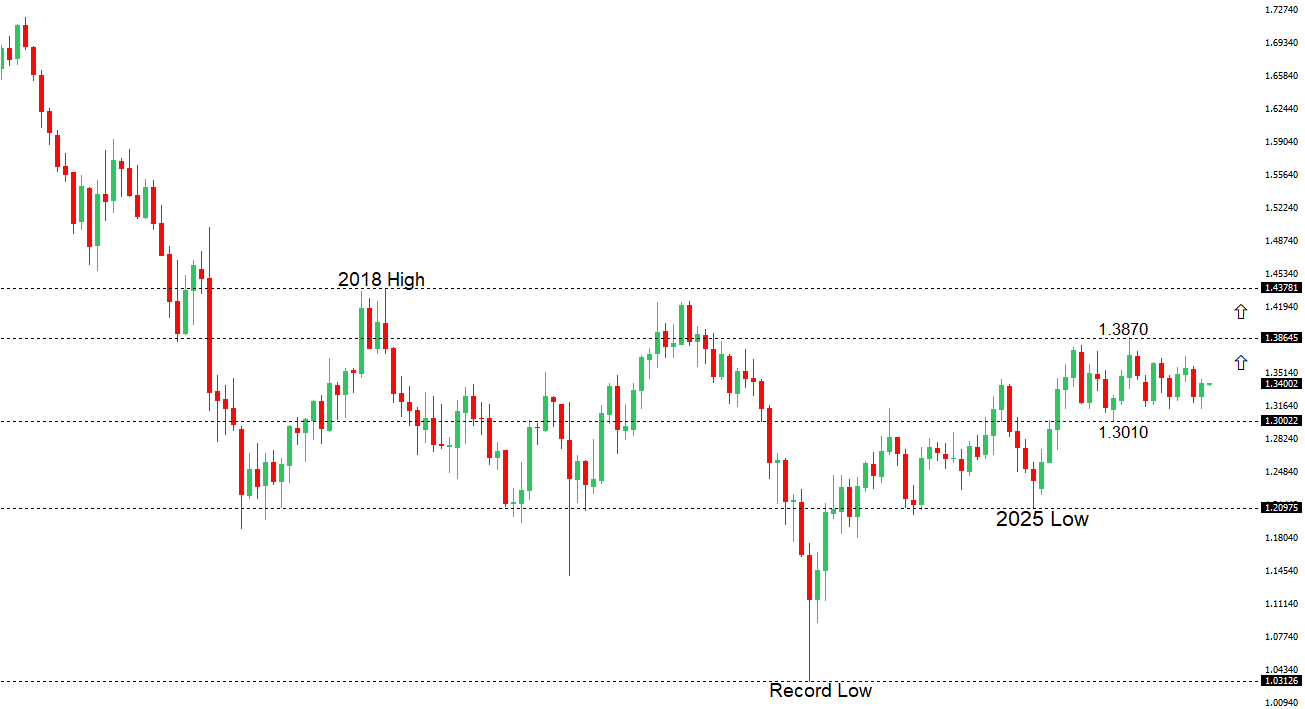 | ||
| R2 1.3498 - 16 September high - Medium R1 1.3434 - 30 October high - Medium S1 1.3339 - 28 October high - Medium S2 1.3272 - 28 October low - Strong | ||
| GBPUSD: fundamental overview | ||
| Sterling has started the week on a firmer footing, supported by expectations of tighter Bank of England policy and a softer US dollar as hopes for progress in US–Iran diplomacy reduce demand for safe havens. Markets are anticipating a quarter-point rate increase at Wednesday’s BoE decision, leaving the pound sensitive to the vote split and guidance on whether further tightening will be needed. With a hike already widely expected, sustained support will depend on how strongly policymakers signal concern over persistent inflation. Meanwhile, US business surveys and Friday’s employment report will help shape the dollar outlook, with Middle East developments remaining an important driver of broader risk sentiment. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
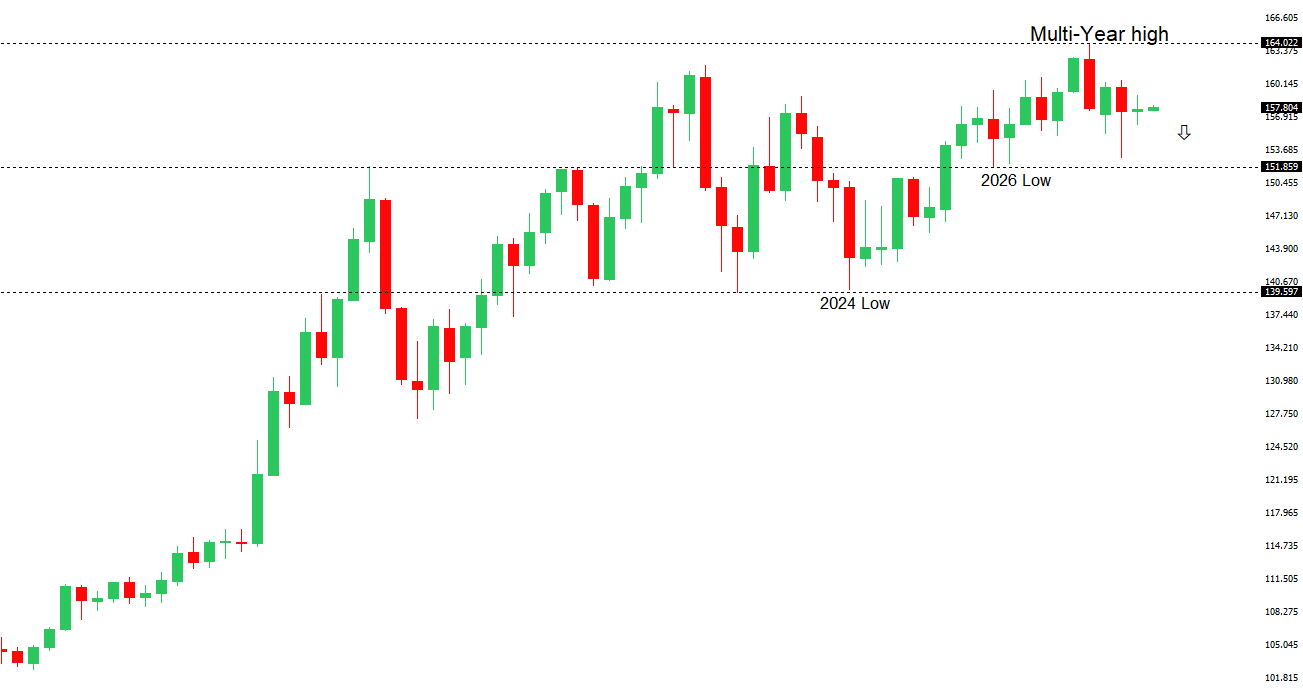 | ||
| R2 159.04 - 24 September high - Strong R1 158.35 - 28 October high - Medium S1 156.07 - 23 October low - Medium S2 155.29 - 4 September low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen has come under renewed pressure as uncertainty over the timing of the Bank of Japan’s next rate increase keeps attention on Japan’s still-unfavorable interest rate differentials. The BoJ’s less hawkish messaging has tempered support from expectations of further policy normalization, while fresh warnings from Finance Minister Satsuki Katayama about action against excessive or disorderly currency weakness have offered little immediate relief. Meanwhile, resilient US activity and persistent inflation pressures continue to underpin expectations of further Federal Reserve tightening, supporting the dollar’s yield advantage. Hopes for progress in Middle East diplomacy could temper dollar demand, although elevated oil prices and the risk of renewed confrontation remain concerns for Japan’s energy-dependent economy. Overall, the yen remains vulnerable without clearer signals of BoJ tightening, while intervention risk could increasingly restrain the pace of depreciation. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
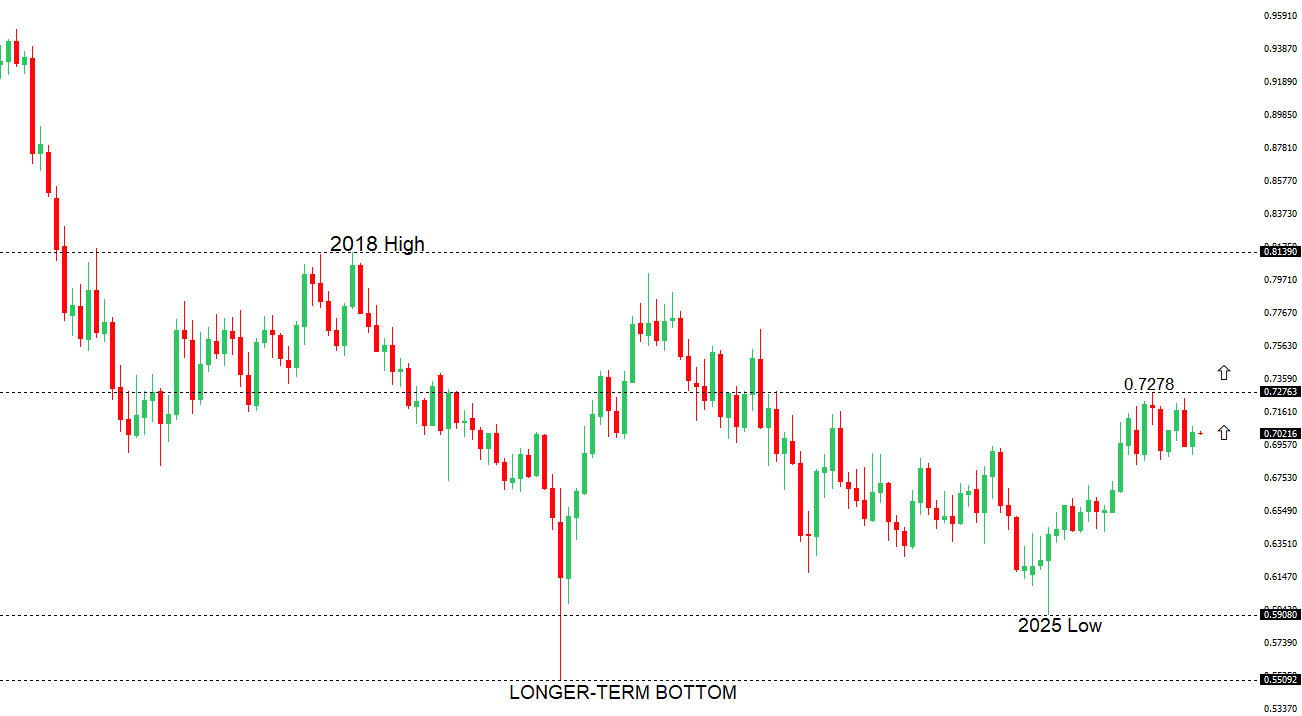 | ||
| R2 0.7100 - Figure - Medium R1 0.7068 - 29 October high - Medium S1 0.6970 - 20 October low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar has come under modest pressure as disappointing Chinese official PMI data raised concerns about demand from Australia’s largest trading partner, while geopolitical uncertainty supported safe-haven demand for the US dollar. However, expectations for a 25-basis-point RBA rate hike on Tuesday, driven by persistent domestic inflation pressures, are providing an offset and keeping traders cautious about extending bearish positions. The key focus is whether the RBA delivers the expected increase and signals further tightening, with the guidance likely to determine whether interest rate support can outweigh concerns about China and broader risk sentiment. | ||
| Suggested reading | ||
| What’s the risk of political violence?, M. Wolf, Financial Times (November 2, 2026) The Fed Knows It Needs to Hike. So Why Wait?, J. Wolfers, Platypus Economics (October 29, 2026) | ||