 | ||
| 25th September 2026 | view in browser | ||
| Hopes for Hormuz, pressure from yields | ||
| Markets head into Friday caught between relief over the extended US–China trade truce and hopes for Iran diplomacy on one side, and rising bond yields, a firm dollar and unresolved geopolitical risks on the other. | ||
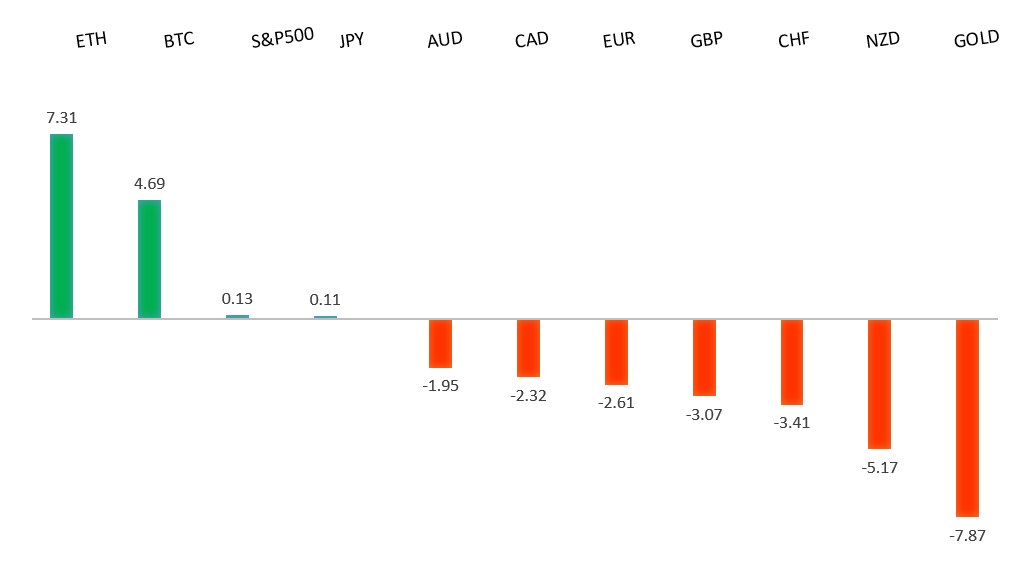
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1300. | ||
 | ||
| R2 1.1557 - 16 September high - Medium R1 1.1498 - 17 September high - Medium S1 1.1359 - 24 September low - Medium S2 1.1353 - 28 July low - Medium | ||
| EURUSD: fundamental overview | ||
| The euro remains under pressure against the dollar as resilient US activity and hawkish Fed commentary keep expectations of further tightening alive. That has outweighed support from the eurozone’s stronger September business surveys and the ECB’s recent rate increase. Higher energy costs are adding to eurozone inflation risks and the case for another ECB hike, but they also threaten growth, leaving the euro vulnerable while investors see the US economy holding up better. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
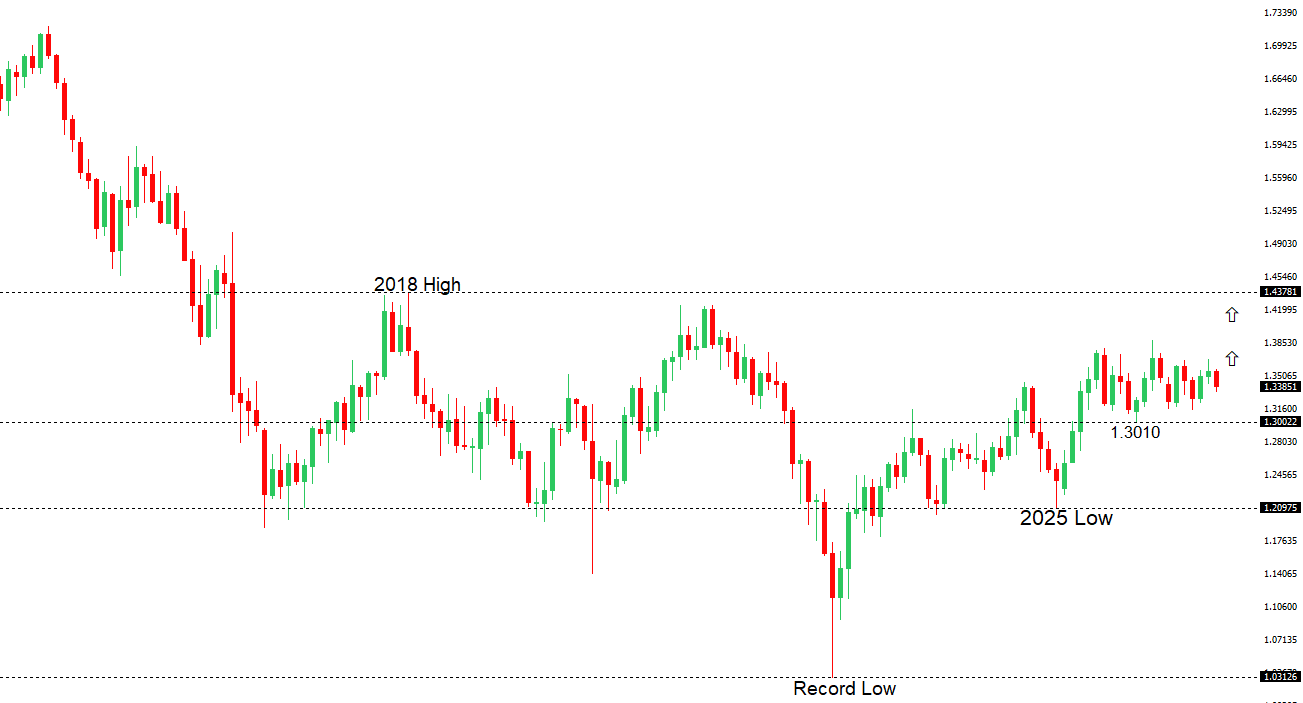 | ||
| R2 1.3407 - 17 September high - Medium R1 1.3300 - Figure - Medium S1 1.3204 - 24 September low - Medium S2 1.3140 - 24 June/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| Sterling remains under pressure as UK fiscal concerns add to a broader rise in the dollar. August borrowing came in above expectations, leaving the deficit for the financial year to date ahead of official forecasts and increasing scrutiny of the government’s room to maneuver ahead of October’s Budget. September’s softer UK business surveys have added to growth concerns, especially after stronger US readings reinforced the dollar. The Bank of England’s concern that high energy prices could keep inflation elevated is supporting expectations of a rate hike, but that prospect has offered the pound limited relief while investors weigh the same energy shock’s effect on UK growth and public finances. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
 | ||
| R2 160.40 - 2 September high - Strong R1 159.04 - 24 September high - Medium S1 156.57 - 21 September low - Medium S2 155.33 - 17 September low - Medium | ||
| USDJPY: fundamental overview | ||
| The yen has recovered modestly after USDJPY kissed 159, as the risk of Japanese intervention made traders cautious about pushing the pair closer to 160. Hopes for US-Iran diplomacy have also taken some strength out of the dollar by easing oil and inflation concerns. The broader pressure on the yen remains, though: the Bank of Japan’s recent rate increase has done little to close the wide interest rate gap with the US, while expectations of further Fed tightening continue to support US yields and the dollar. For now, intervention risk is limiting yen weakness, but the rate gap remains the main obstacle to a sustained recovery. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
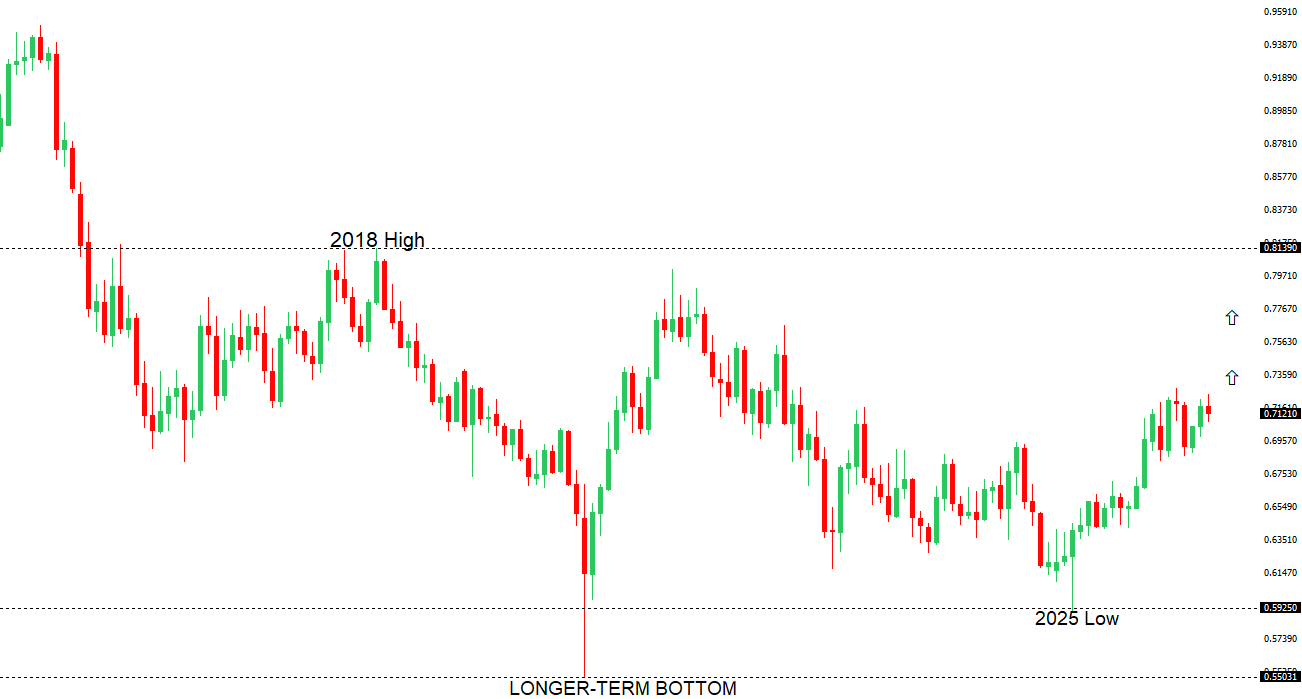 | ||
| R2 0.7142 - 15 September high - Strong R1 0.7100 - Figure - Medium S1 0.7004 - 24 September low - Medium S2 0.7000 - Psychological - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar has steadied as traders weigh support from a hawkish RBA against a firm US dollar. Australia’s unemployment rate rose slightly in August, but stronger job growth and higher labor force participation suggest the labor market remains resilient, keeping expectations of a rate hike next week intact. The extension of the US–China trade truce has also helped sentiment toward the Aussie, given Australia’s exposure to Chinese demand, although the Trump–Xi summit offered little progress on the larger disputes. Meanwhile, elevated US yields and expectations of further Fed tightening continue to limit the currency’s gains. | ||
| Suggested reading | ||
| History’s craziest frauds | The Story of Money, G. Tett, Financial Times (September 23, 2026) We Can’t Repeal the Laws of Economics, H. Marks, Oaktree (September 22, 2026) | ||