 | ||
| 27th October 2026 | view in browser | ||
| Delicate dance between risk and restraint | ||
| Global markets head into Tuesday with a cautiously constructive tone, as a rebound in equities and easing oil prices offer some relief, while a firmer Dollar and looming central bank decisions keep investors focused on monetary policy expectations and geopolitical risks. | ||
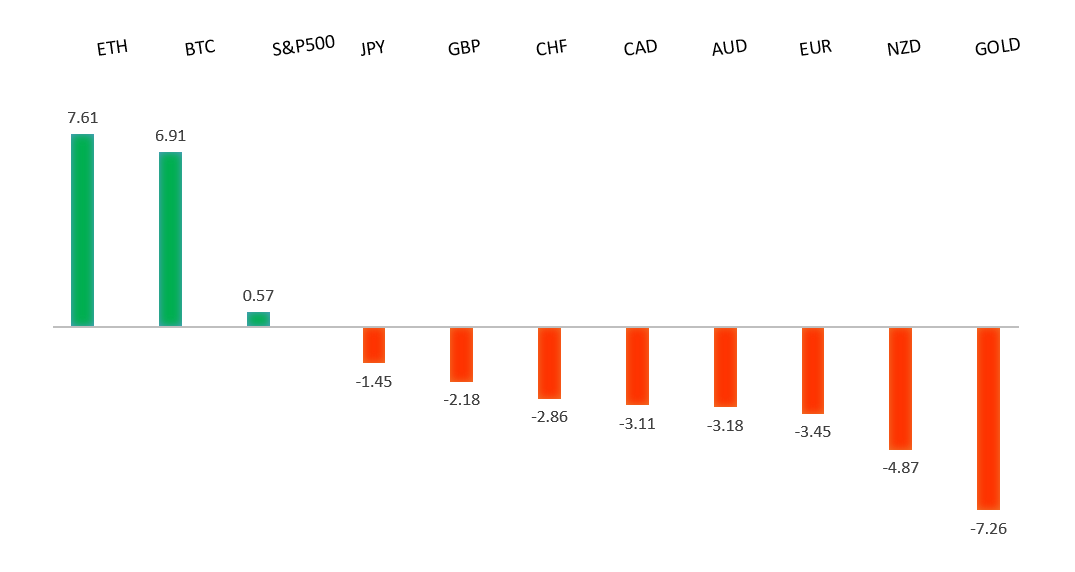
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
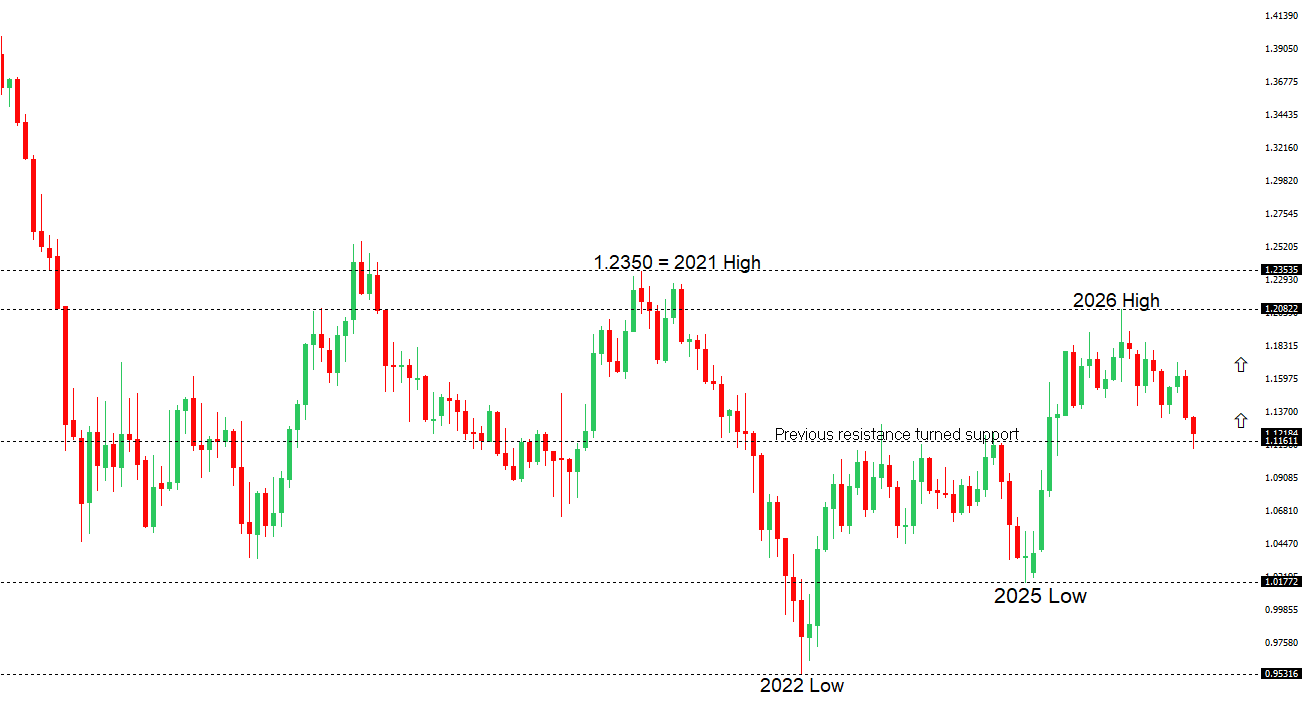 | ||
| R2 1.1337 - 1 October high - Medium R1 1.1270 - 16 October high - Medium S1 1.1148 - 15 Octoberber low - Medium S2 1.1113 - 14 Octoberber/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro remains under pressure as investors position for a busy week of central bank decisions, with the Federal Reserve and European Central Bank set to announce policy decisions just one day apart. The single currency has struggled to capitalize on encouraging German economic data, with October’s Ifo business climate index rising more than expected, supported by an improvement in business expectations even as current conditions weakened. The report offers some reassurance that Europe’s largest economy is finding its footing, though persistent fiscal and political uncertainty in France continues to temper enthusiasm for the euro. Attention now turns to the ECB, which is widely expected to leave rates unchanged on Thursday, with investors focused on President Lagarde’s assessment of inflation, growth, and the prospects for further tightening in December. Meanwhile, expectations for a more hawkish Fed and the prospect of a widening US-Eurozone interest rate differential have reinforced dollar demand. Tuesday’s ECB bank lending survey and Lagarde’s remarks will provide additional insight into the regional outlook ahead of Thursday’s decision, with the euro likely to remain sensitive to any shift in relative monetary policy expectations. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
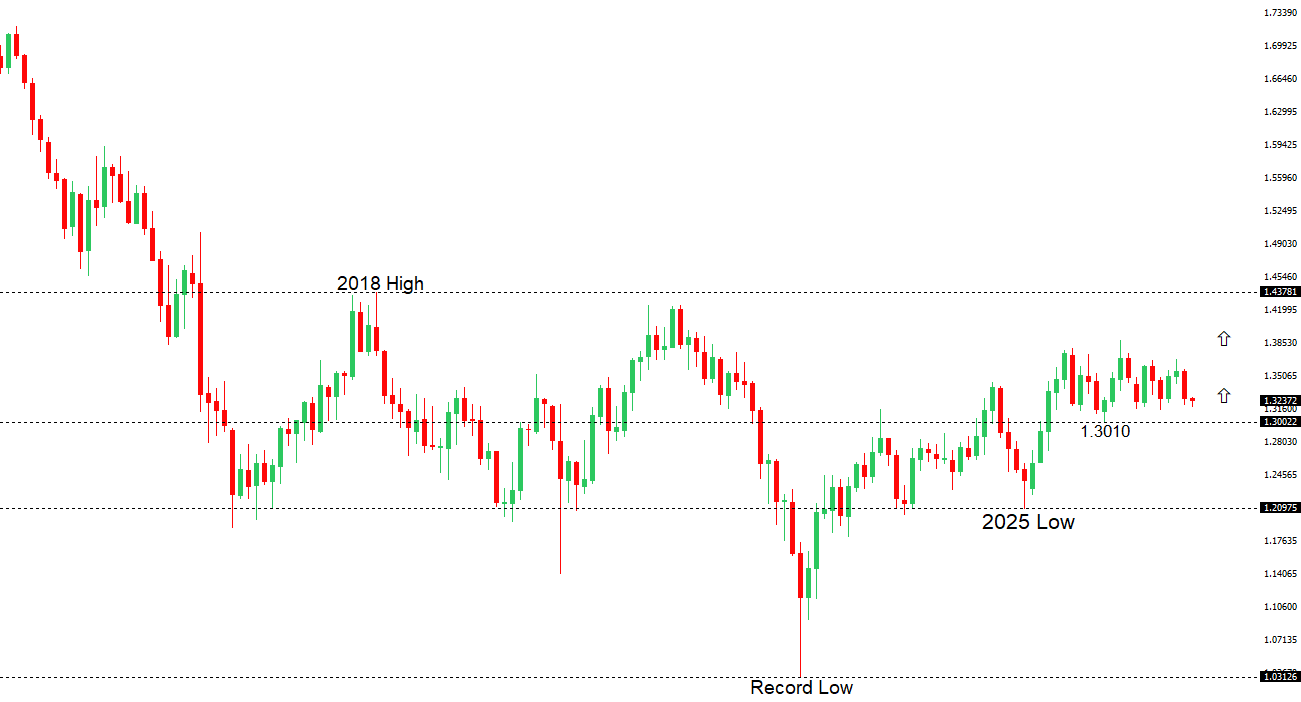 | ||
| R2 1.3498 - 16 September high - Medium R1 1.3420 - 22 October high - Medium S1 1.3297 - 20 October low - Medium S2 1.3137 - 14 October/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The Pound has come under modest pressure, with recent weakness against the US Dollar largely reflecting renewed Dollar demand ahead of Wednesday’s Federal Reserve decision rather than a deterioration in UK fundamentals. Sterling has held relatively steady against the Euro, supported by expectations that the Bank of England will raise interest rates at its November meeting following persistent inflation pressures and resilient wage growth. Attention is now turning to Chancellor Reeves’ upcoming Budget, where fiscal policy, potential tax changes, and government borrowing plans will be closely scrutinized for their implications for growth, inflation, and gilt yields. Reports of a further increase in the minimum wage have reinforced concerns over persistent domestic cost pressures, adding to the case for tighter monetary policy. With the Fed decision, UK Budget, and upcoming US inflation data all on the calendar, Sterling’s near-term direction will likely depend on the interaction between UK fiscal credibility, BoE policy expectations, and broader Dollar sentiment. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
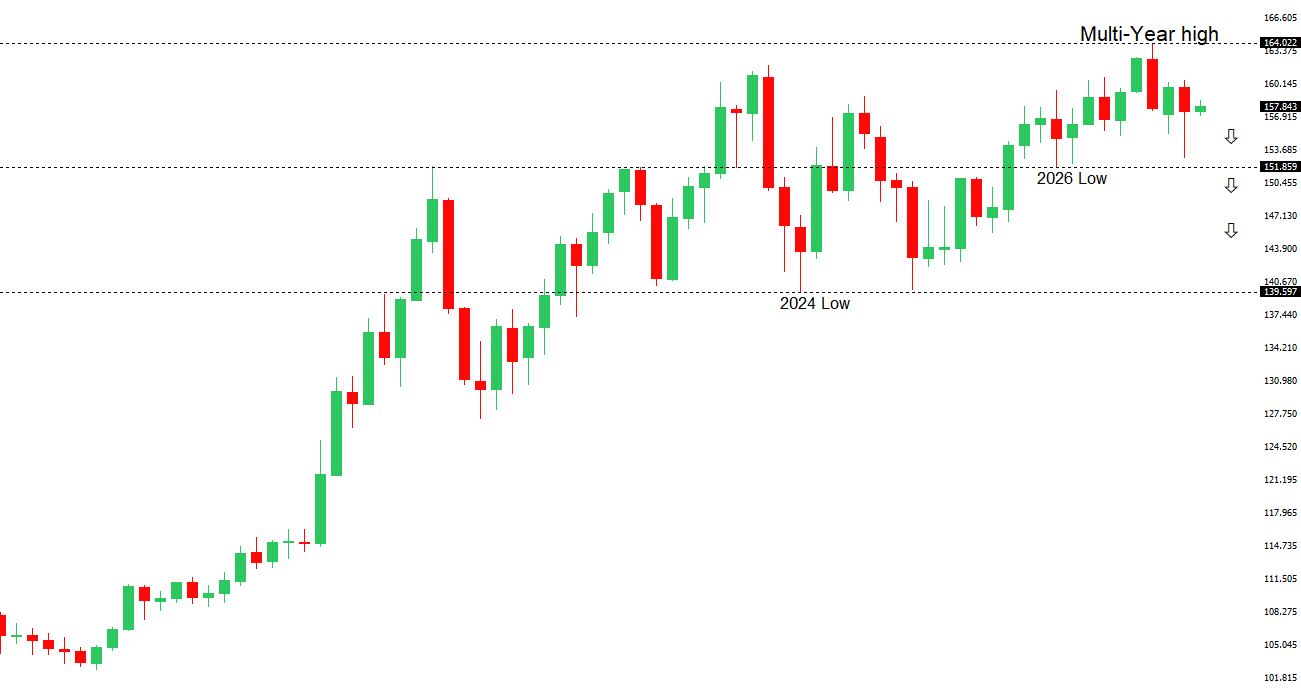 | ||
| R2 159.04 - 24 September high - Strong R1 158.26 - 22 October high - Medium S1 156.07 - 23 October low - Medium S2 155.29 - 4 September low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen has come back under pressure as investors look ahead to Friday’s Bank of Japan policy decision, with markets widely expecting the central bank to leave rates unchanged following September’s hike. Governor Ueda has signaled little urgency to deliver consecutive rate increases, shifting attention to his guidance on the timing of further tightening, particularly the possibility of another move in December. While underlying inflation pressures and wage growth continue to support the case for additional policy normalization, uncertainty surrounding Japan’s economic outlook and the sustainability of inflation has kept the BoJ cautious. Upcoming Tokyo inflation and employment figures will provide another important test of the tightening outlook, while the Federal Reserve’s policy decision and key US economic releases could prove equally influential through their impact on US Treasury yields and interest rate differentials. With a near-term BoJ hold largely priced in, the yen may need a more hawkish signal from Ueda or a meaningful retreat in US yields to regain sustained upside momentum. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
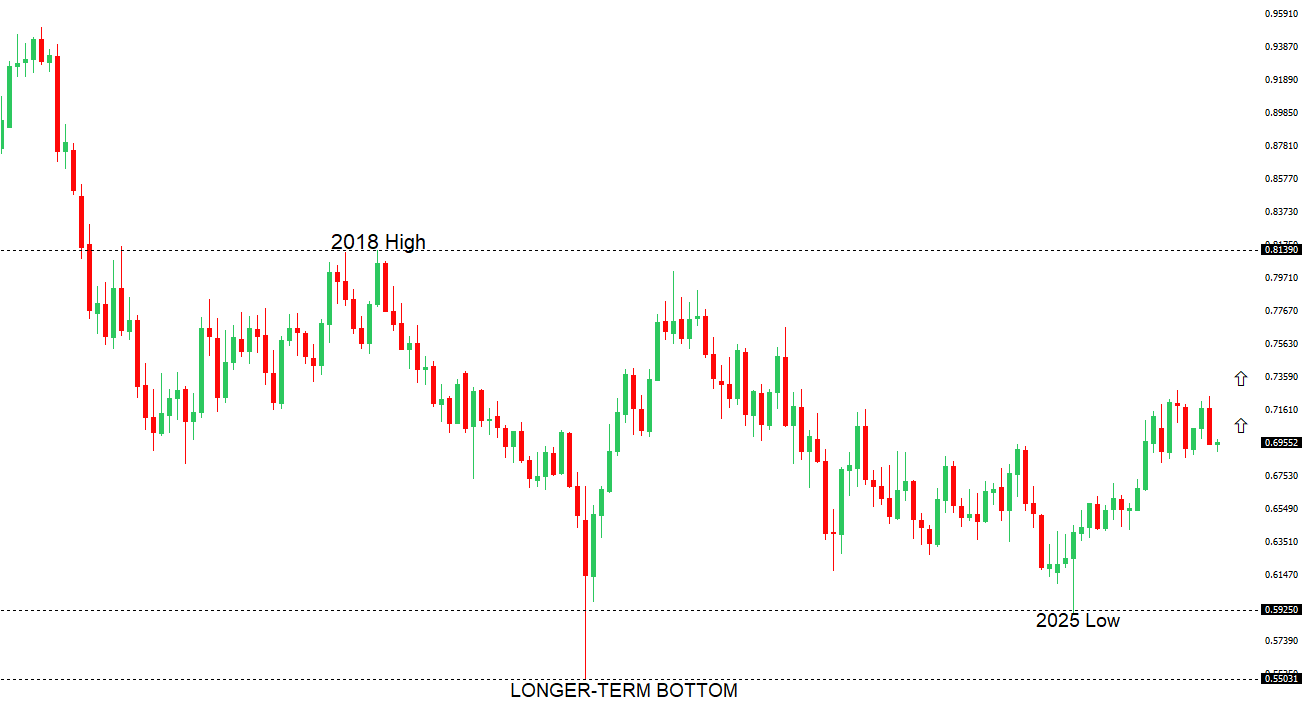 | ||
| R2 0.7100 - Figure - Medium R1 .7046 - 24 September high - Medium S1 0.6970 - 20 October low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar has come under modest pressure as renewed US dollar strength offsets otherwise supportive risk sentiment and expectations of further Reserve Bank of Australia tightening. The RBA’s relatively hawkish stance continues to underpin the Aussie, with persistent domestic inflation pressures keeping the prospect of another rate hike firmly in focus. Attention now turns to Wednesday’s Australian inflation figures and remarks from RBA Governor Michele Bullock, with any upside surprise in underlying price pressures likely to reinforce expectations for additional tightening. Meanwhile, easing oil prices amid diplomatic efforts in the Middle East have helped improve broader market sentiment, although geopolitical uncertainty remains a source of caution. The Federal Reserve’s policy decision and Chair Kevin Warsh’s accompanying guidance will also be critical, with the outlook for US interest rates and the dollar likely to influence the Aussie’s near-term direction. | ||
| Suggested reading | ||
| The infinite career – why we can’t retire, I. Berwick, Financial Times (October 26, 2026) Fed Chair Warsh Has to Make a Communications U-Turn, G. Robb, Axios (October 25, 2026) | ||