 | ||
| 5th October 2026 | view in browser | ||
| A softer Fed, a stubborn dollar | ||
| Equities enter Monday supported by softer Fed hike expectations, while elevated yields underpin the dollar, French fiscal stress weighs on the euro and recovering Gulf supply nudges oil lower despite persistent geopolitical risks. | ||
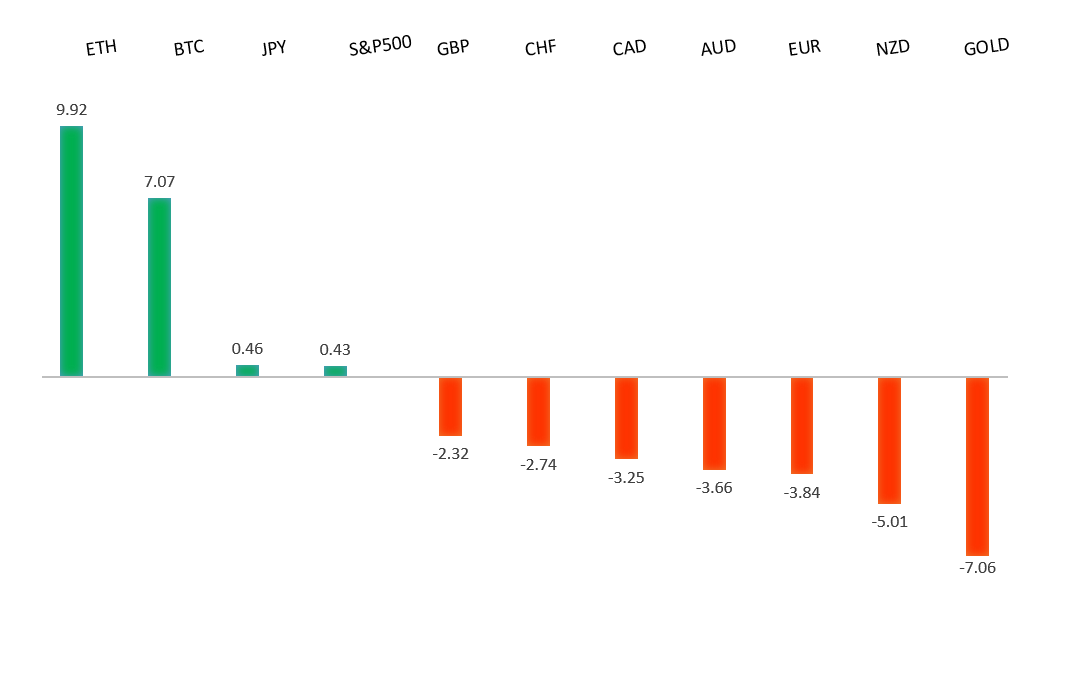
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1200 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
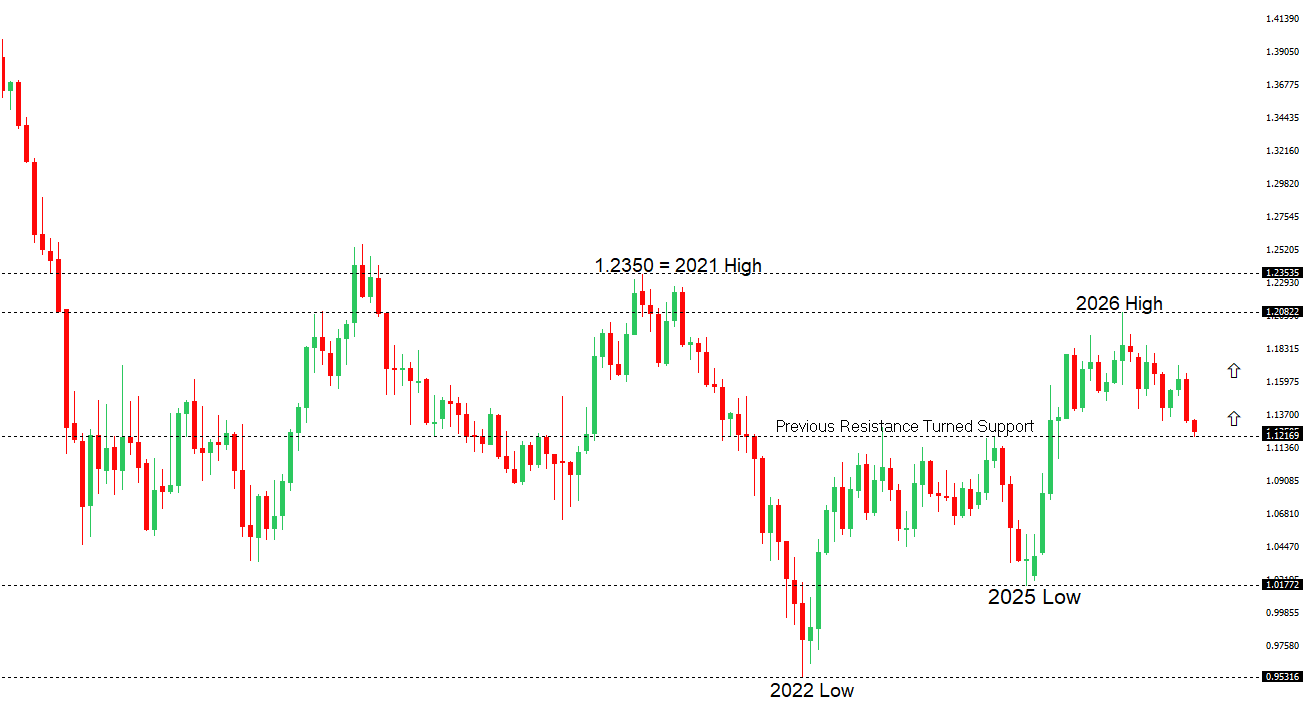 | ||
| R2 1.1337 - 1 October high - Medium R1 1.1286 - 2 October high - Medium S1 1.1161 - 4 Octoberber/2026 low - Strong S2 1.1100 - Figure - Strong | ||
| EURUSD: fundamental overview | ||
| The euro remains under pressure as France’s fiscal problems and political uncertainty undermine confidence, with rising borrowing costs and doubts over the government’s ability to pass its budget raising concerns about wider regional spillovers. These domestic risks have outweighed the potential support from weaker US employment data, which reduced expectations for an October Fed rate hike. Meanwhile, cautious ECB communication and contained underlying inflation suggest little urgency to tighten policy, leaving the euro sensitive to French budget developments and the next round of US data, particularly today’s ISM services report. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
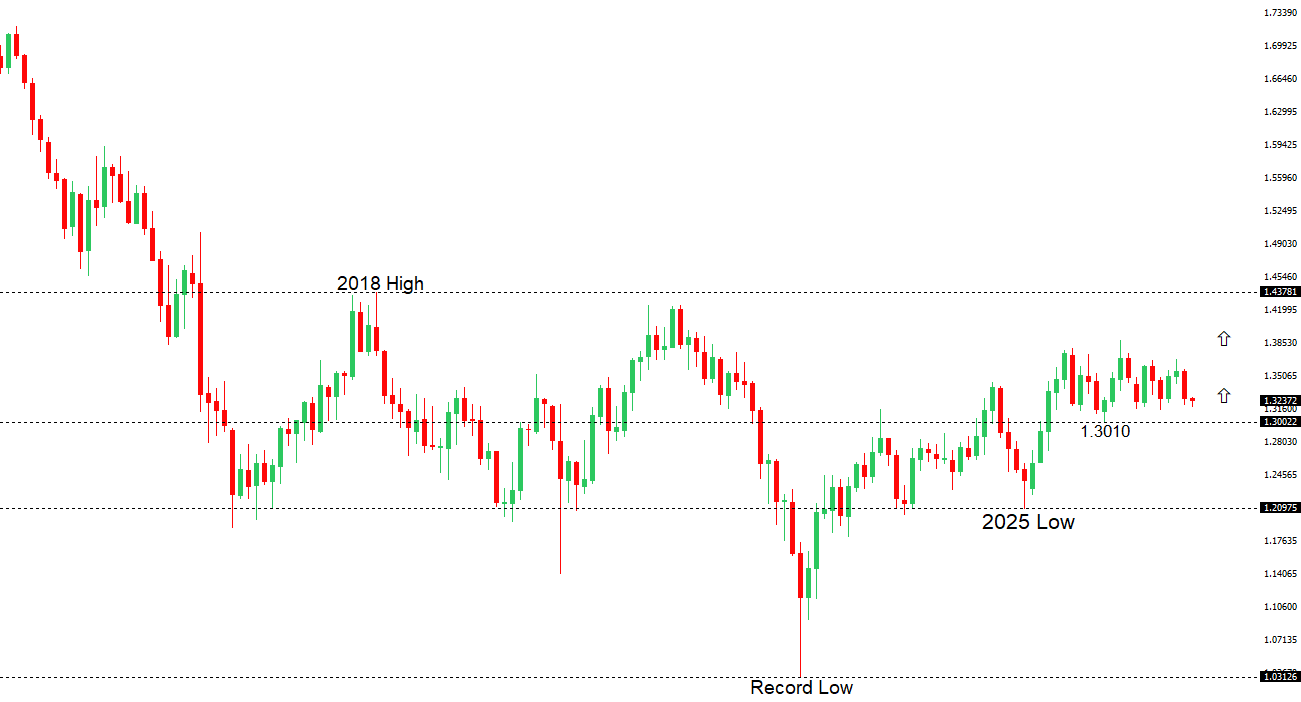 | ||
| R2 1.3407 - 17 September high - Medium R1 1.3312 - 30 September high - Medium S1 1.3181 - 1 October low - Medium S2 1.3140 - 24 June/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound is softening as renewed dollar demand outweighs the relief from weaker US employment data and reduced expectations for an October Fed rate hike, with attention now turning to the US ISM services report. Sterling retains some support from expectations that the Bank of England could raise rates to contain persistent, energy-driven inflation, while an improved outlook for UK growth reinforces that policy bias. For now, however, those domestic supports are proving insufficient to offset the dollar’s strength, leaving the pound sensitive to incoming US data and shifts in relative interest rate expectations. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
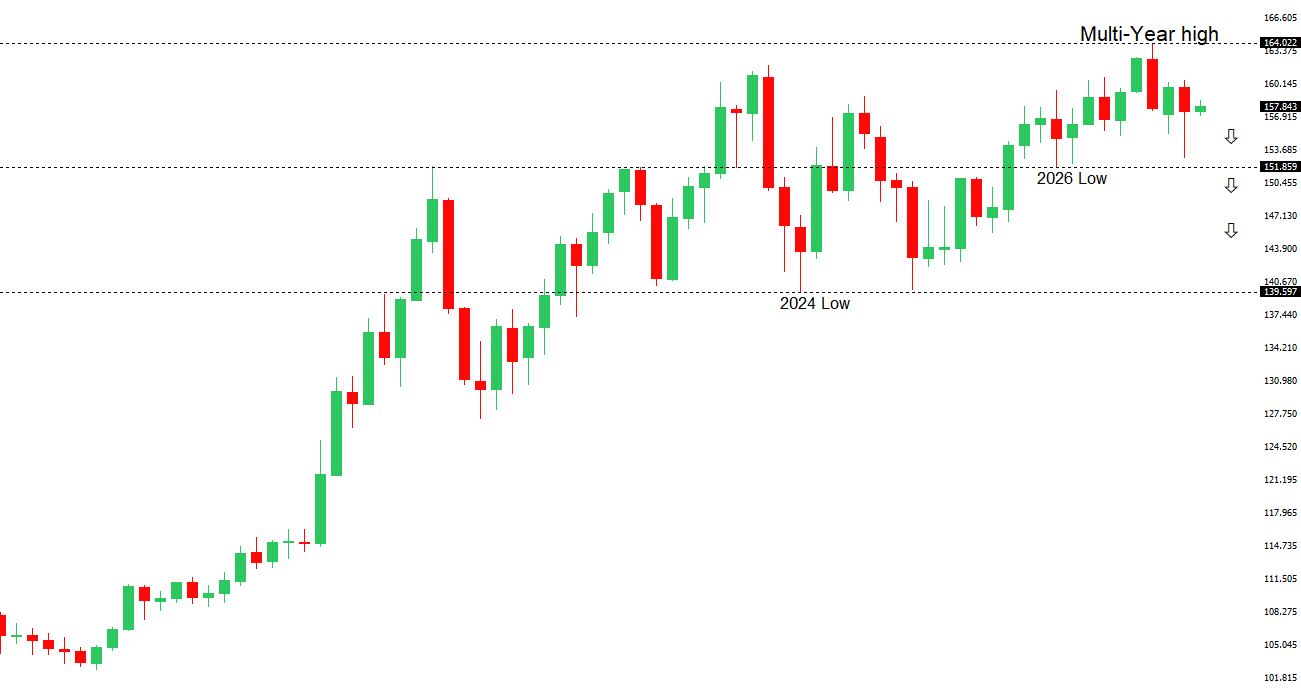 | ||
| R2 159.04 - 24 September high - Strong R1 158.46 - 1 October high - Medium S1 156.37 - 30 September low - Medium S2 155.33 - 17 September low - Medium | ||
| USDJPY: fundamental overview | ||
| The yen is finding support from softer US employment data, which have reduced expectations for an October Fed hike, alongside continued signals of inflation vigilance from the Bank of Japan. Deputy Governor Uchida’s latest comments highlight AI investment as a potential source of stronger demand and upward pressure on prices, reinforcing the case for continued policy normalization without offering an explicit signal on the timing of another hike. Elevated US Treasury yields remain a constraint, however, leaving the yen sensitive to shifts in the US-Japan interest rate differential. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
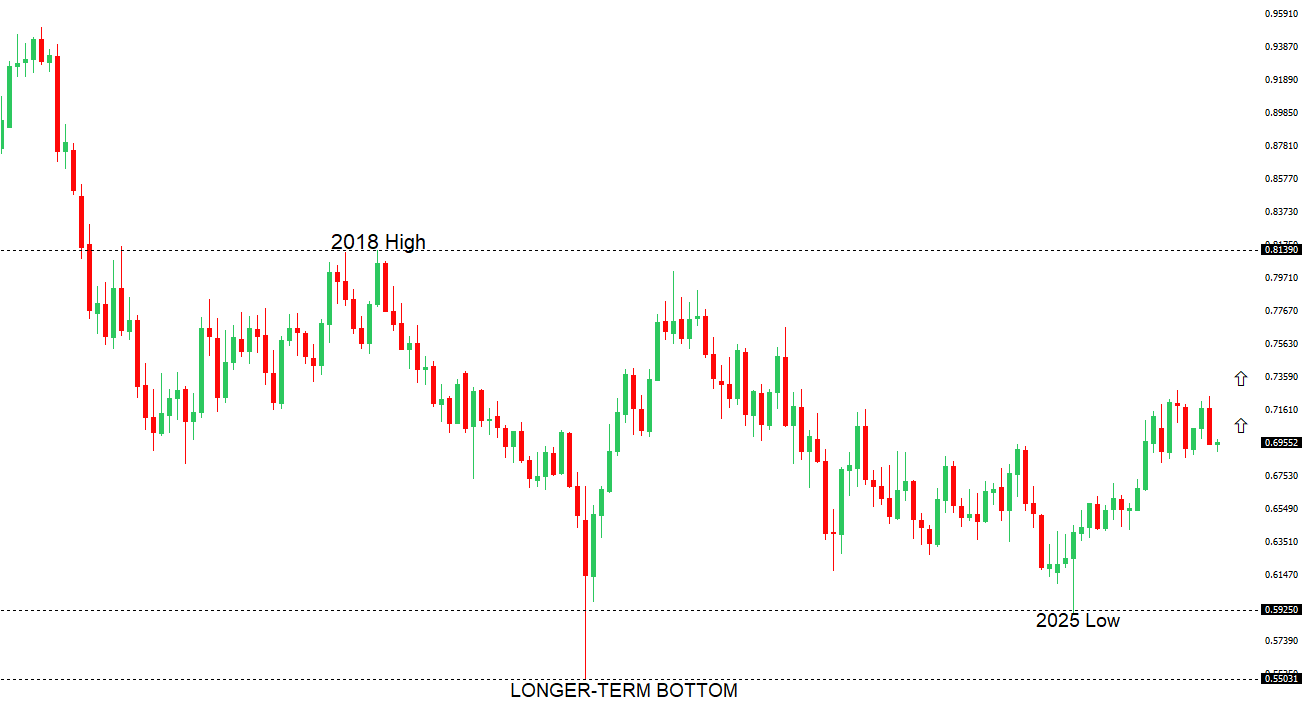 | ||
| R2 0.7142 - 15 September high - Strong R1 0.6995 - 30 September high - Medium S1 0.6904 - 1 October low - Medium S2 0.6865 - 30 June low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar remains under pressure from broad US dollar strength, with mounting French fiscal concerns encouraging demand for the greenback and weighing on risk-sensitive currencies. Softer US employment data have reduced expectations for an October Fed rate hike, offering some potential relief for the Aussie, but elevated US Treasury yields continue to support the dollar. For now, global risk sentiment and the outlook for US monetary policy are overshadowing domestic drivers, leaving the Australian dollar vulnerable while demand for the greenback remains firm. | ||
| Suggested reading | ||
| The Pope Tried to Ban Prediction Markets in 1591, R. Chan-Wei, Cato Institute (September 24, 2026) Here’s who’s joining the S&P 500 in the index’s latest shakeup, C. Assis, Marketwatch (October 1, 2026) | ||