 | ||
| 2nd October 2026 | view in browser | ||
| The dollar’s bid meets the wage test | ||
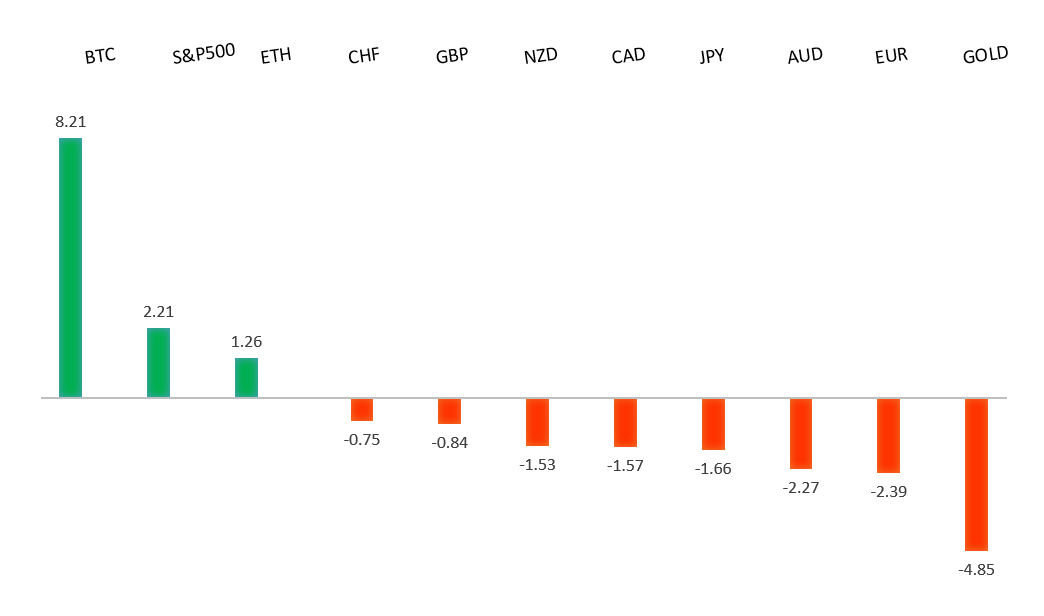
| Markets head into Friday’s US jobs report with the dollar firm, equities tentative and oil elevated, as investors look to hiring and wage growth to determine whether inflation concerns will trigger renewed pressure on bonds. | ||
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1200. | ||
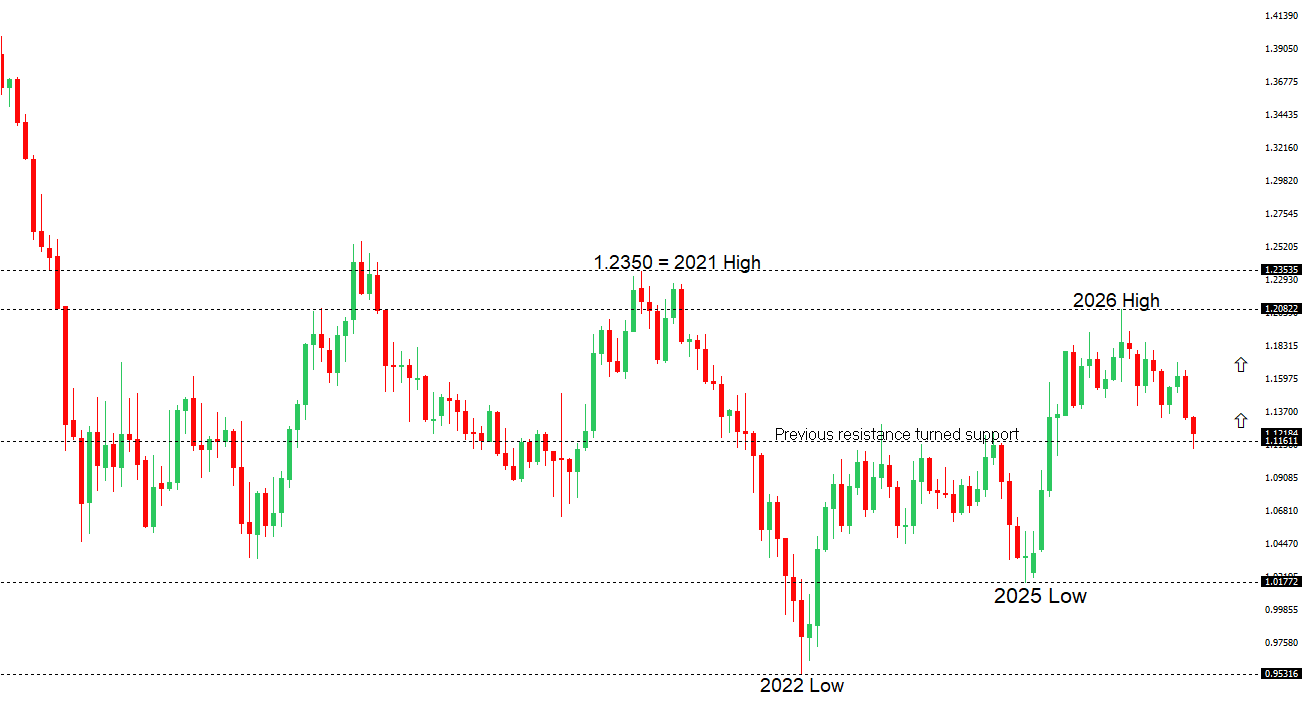 | ||
| R2 1.1381 - 30 September high - Medium R1 1.1337 - 1 October high - Medium S1 1.1215 - 1 Octoberber/2026 low - Strong S2 1.1200 - Figure - Strong | ||
| EURUSD: fundamental overview | ||
| The euro is finding some relief as the Dollar eases ahead of today’s key data, but the broader fundamental backdrop remains challenging after several sessions of losses. Hawkish Fed commentary, including Lorie Logan’s call for further tightening, has supported US rate expectations and kept the single currency under pressure. Attention now turns to Eurozone inflation, where an expected acceleration could reinforce expectations for additional ECB rate hikes and offer the euro some support. The US employment report will be equally important: resilient hiring and firm wage growth would strengthen the case for further Fed tightening, while softer labor market conditions could temper those expectations and give the euro room to recover. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
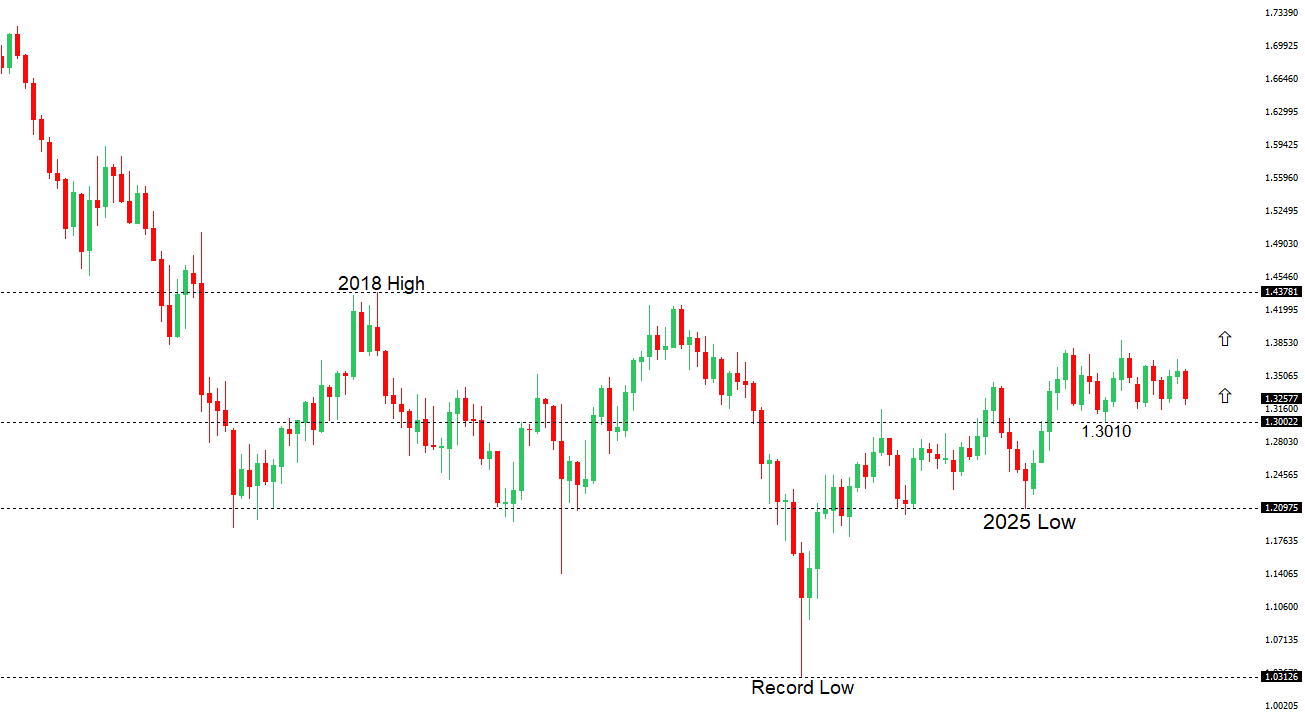 | ||
| R2 1.3407 - 17 September high - Medium R1 1.3312 - 30 September high - Medium S1 1.3181 - 1 October low - Medium S2 1.3140 - 24 June/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound remains under pressure as broad US Dollar strength combines with mounting concerns over the UK’s fiscal outlook. Oil-driven inflation risks and persistent US-Iran tensions are keeping US Treasury yields elevated and supporting safe-haven demand for the Dollar, even as expectations for an October Fed rate hike have eased. Meanwhile, the surge in long-term gilt yields is weighing on sterling by raising government borrowing costs and intensifying concerns about fiscal headroom ahead of the Autumn Budget. We now look to US payrolls for the next major catalyst, with a firm report potentially reinforcing Dollar demand, while softer employment and wage growth could offer the pound some relief. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
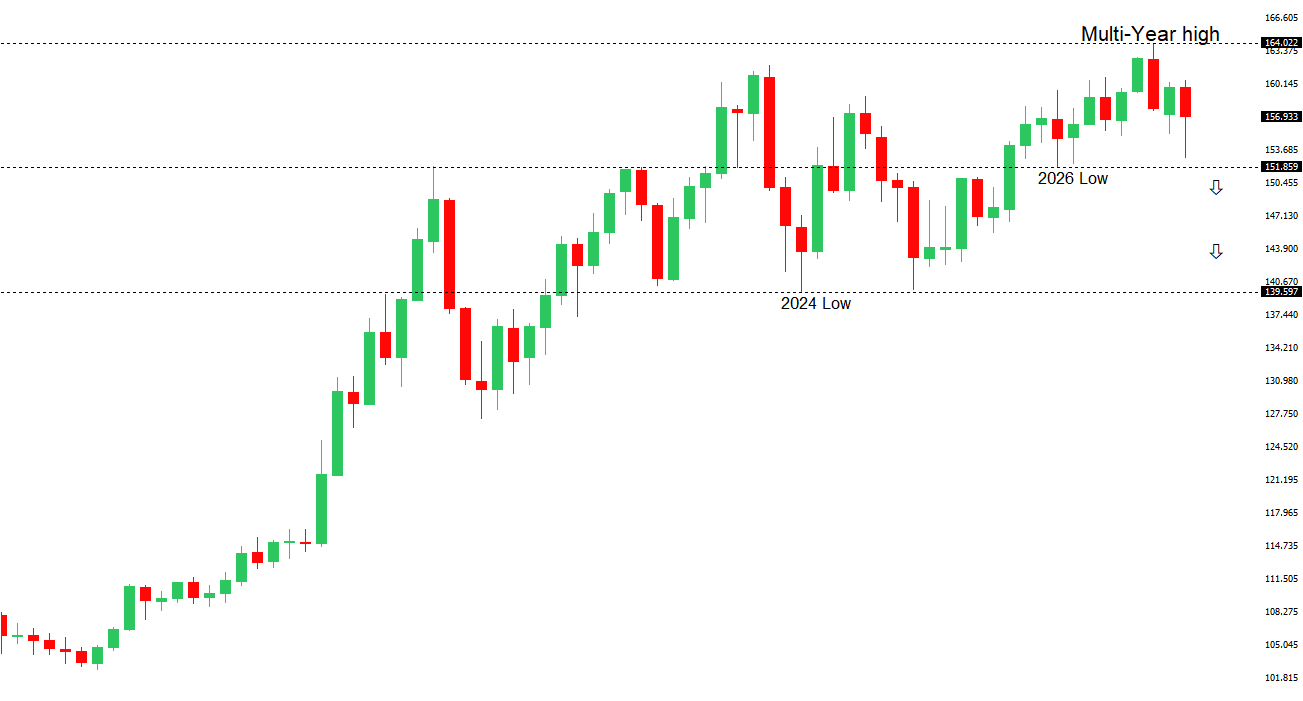 | ||
| R2 159.04 - 24 September high - Strong R1 158.46 - 1 October high - Medium S1 156.37 - 30 September low - Medium S2 155.33 - 17 September low - Medium | ||
| USDJPY: fundamental overview | ||
| The yen has regained support after stronger Tokyo inflation reinforced expectations for further Bank of Japan tightening, with the acceleration in underlying price pressures suggesting inflation extends beyond food and energy. A softer Dollar, reflecting reduced expectations for an October Fed rate hike, has also helped the currency recover. However, elevated US Treasury yields and lingering expectations for a December hike continue to limit the yen’s upside, as energy-driven inflation concerns keep US monetary policy in focus. Attention now turns to US payrolls, which could determine whether the recent easing in Dollar demand develops into a more sustained recovery for the yen. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
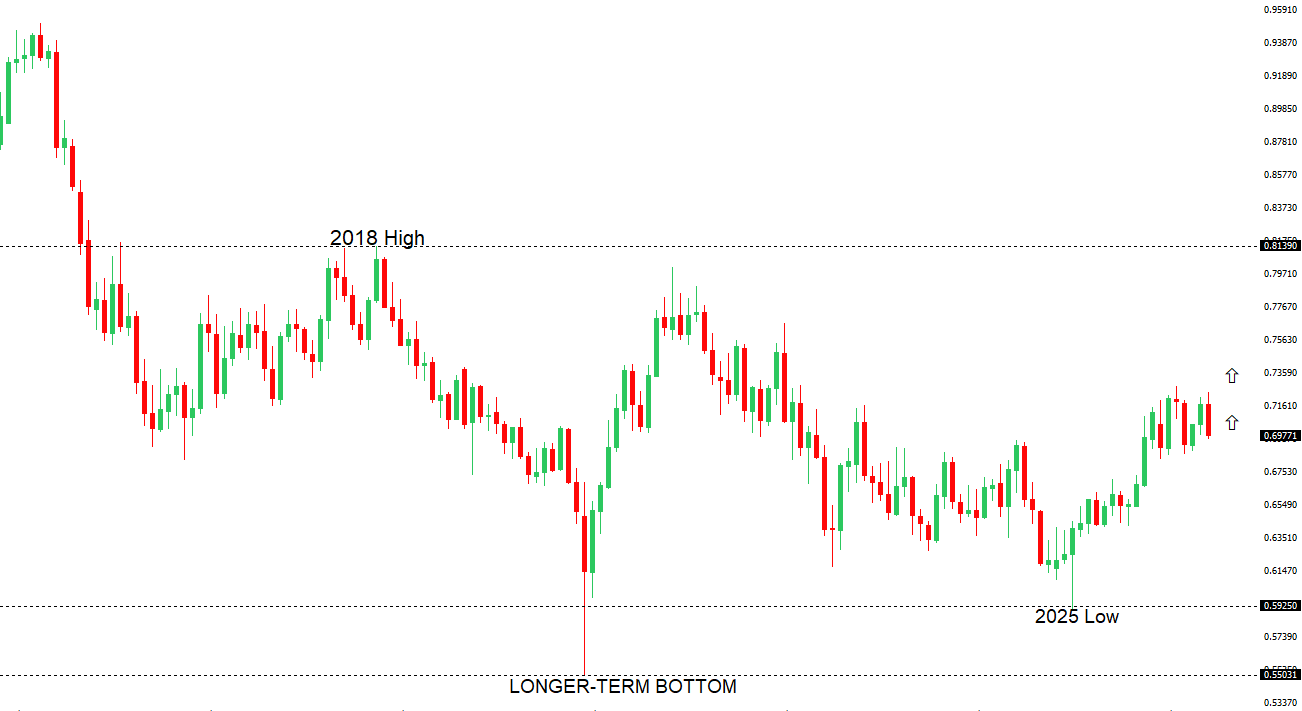 | ||
| R2 0.7142 - 15 September high - Strong R1 0.6995 - 30 September high - Medium S1 0.6904 - 1 October low - Medium S2 0.6865 - 30 June low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar remains under pressure as elevated energy costs sustain US inflation concerns, keeping US yields high and supporting the US dollar ahead of the latest US employment report. A softer jobs reading could temper expectations for further Fed tightening, making the release a key near-term catalyst. Domestically, persistent inflation is keeping another RBA hike in play, although the lagged effects of earlier tightening and emerging property-sector weakness favor a patient approach. CBA sees the hiking cycle as paused for now but considers November’s meeting live, with upcoming inflation data likely to determine whether the RBA delivers additional tightening and provides fresh support for the currency. | ||
| Suggested reading | ||
| The Sovereign Wealth Fund America Needs, S. Hill, Project Syndicate (October 1, 2026) Stocks Tread Water While the Bond Market Shudders, S. Hansen, Morningstar (October 1, 2026) | ||