 | ||
| 5th November 2026 | view in browser | ||
| Buck catches downdraft from crude | ||
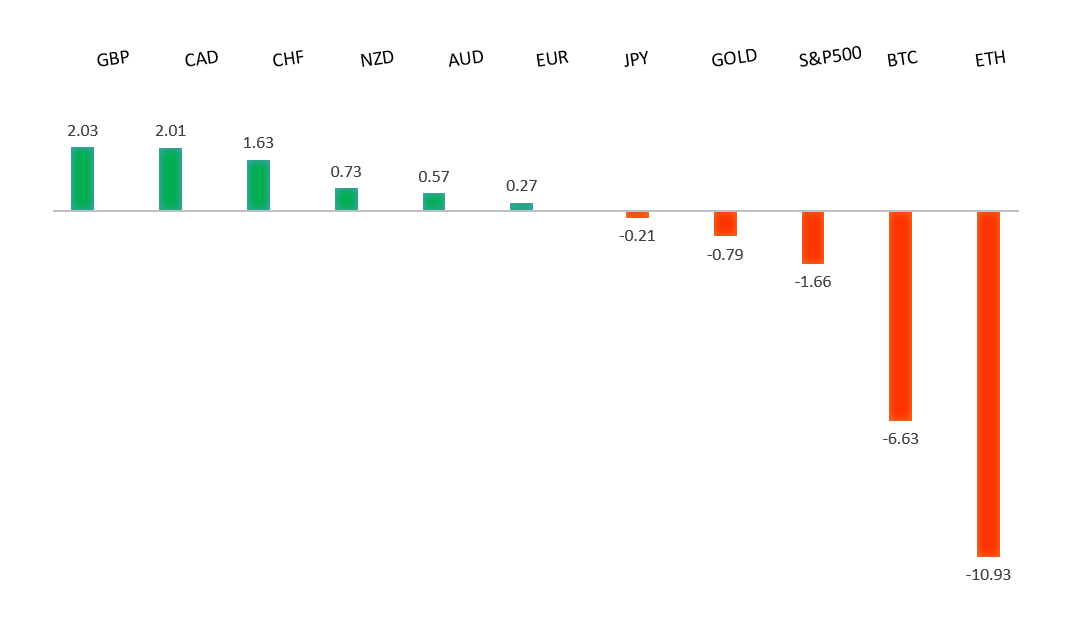
| The dollar and Treasury yields are under pressure heading into Thursday as hopes for US-Iran diplomacy drive oil lower, lift gold and help broaden the post-election rally on Wall Street. | ||
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
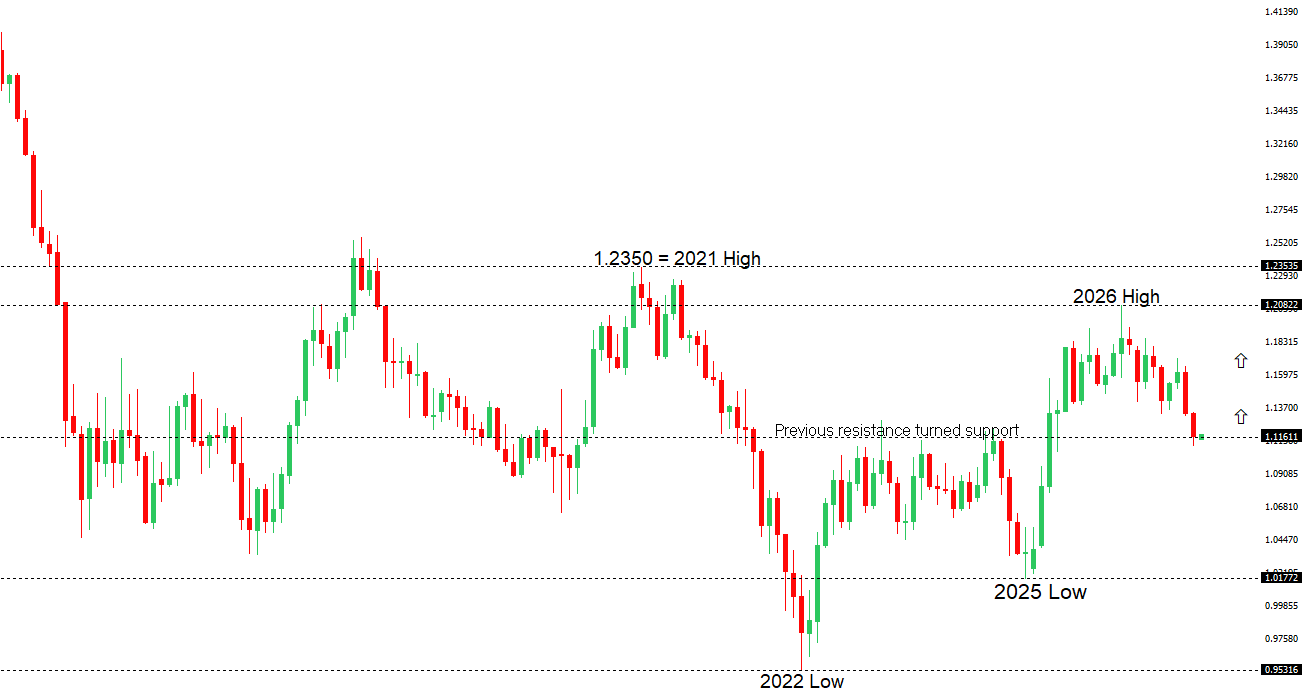 | ||
| R2 1.1337 - 1 October high - Medium R1 1.1274 - 4 November high - Medium S1 1.1136 - 30 October low - Medium S2 1.1104 - 29 October/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro extended its gains against the dollar on Thursday as hotter eurozone inflation reinforced expectations for a December ECB rate hike and falling US Treasury yields weighed on the greenback. Eurozone headline inflation reached a three-year high of 4.0% in October, strengthening the case for a quarter-point move from the ECB. In the US, the midterm results raised the prospect of fiscal gridlock, while hopes for an end to the Iran war pushed oil prices lower and eased inflation concerns. A December Fed hike remains on the table, but lower US yields are giving EURUSD room to rise, with France’s debt burden and political impasse still tempering demand for the euro. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
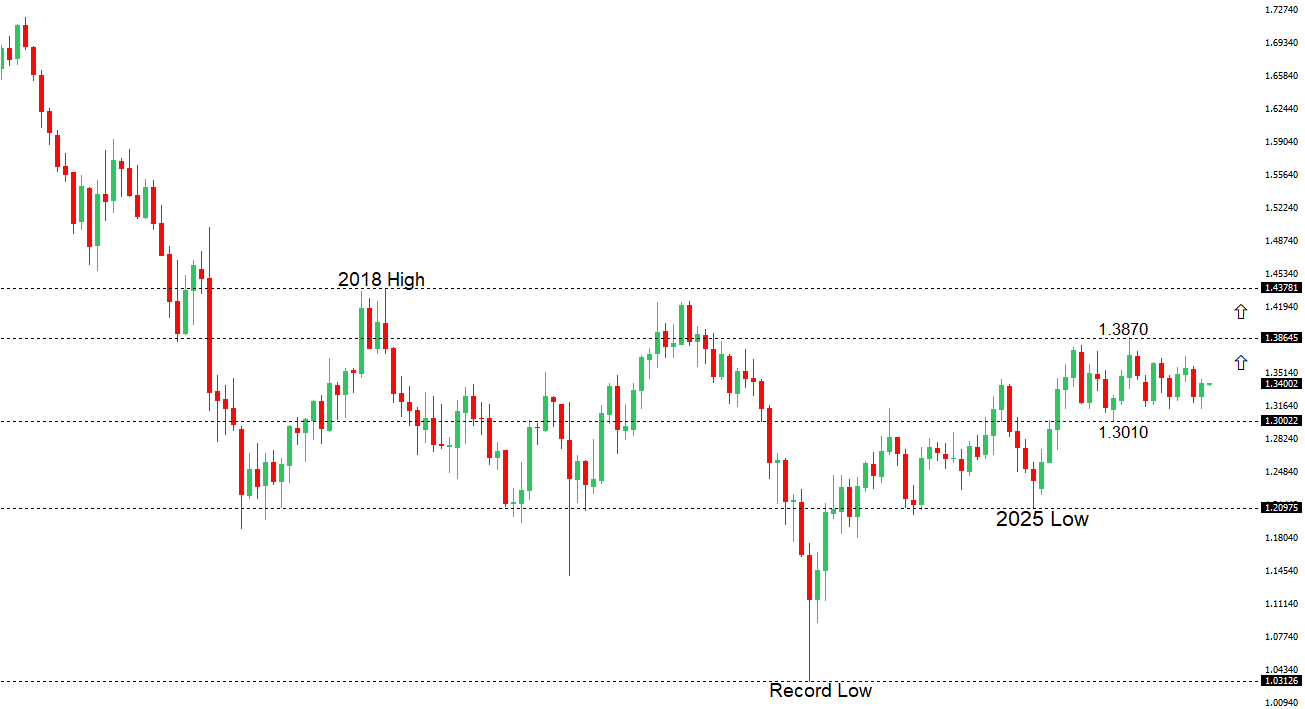 | ||
| R2 1.3568 - 9 September high - Medium R1 1.3504 - 4 November high - Medium S1 1.3396 - 3 November low - Medium S2 1.3371 - 30 October low - Medium | ||
| GBPUSD: fundamental overview | ||
| Sterling is holding near 1.3490 against the dollar early Thursday, tracking the euro higher as Treasury yields ease and the greenback remains under pressure following the Democrats’ capture of both chambers of Congress. Slight downward revisions to the UK’s October services and composite PMIs did little to alter the rate outlook, leaving the Bank of England decision as the next catalyst. A quarter-point hike to 4% is largely priced in, along with another 75 basis points of tightening over the next year or so. That puts the focus on the vote split and Governor Bailey’s guidance for clues on whether the Bank is prepared to tighten as much as markets expect. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
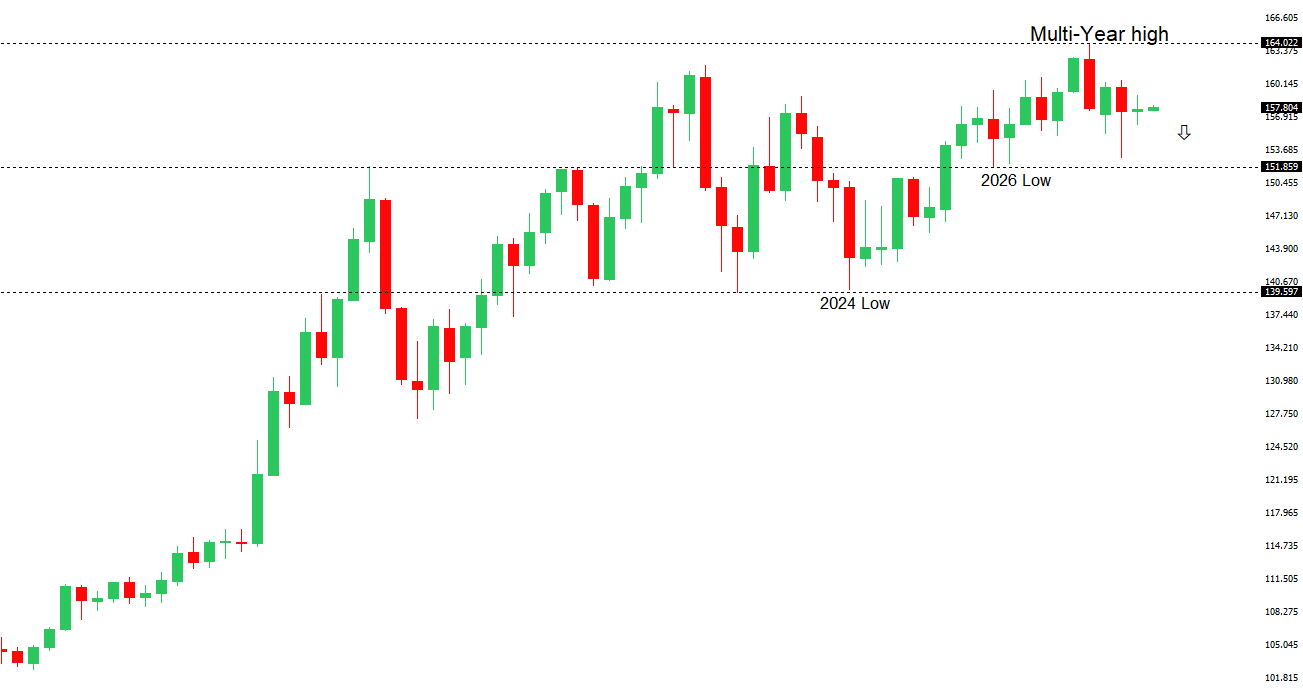 | ||
| R2 159.04 - 24 September high - Strong R1 158.77 - 3 November high - Medium S1 156.96 - 30 October low - Medium S2 156.07 - 23 October low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen is firmer against the dollar for a second straight session after minutes from the Bank of Japan’s September meeting reinforced expectations for a December rate hike. Policymakers backed further tightening, with some open to moving faster if inflation runs hotter than expected. The yen has also benefited from a decline in US Treasury yields as hopes for an easing of tensions with Iran pushed oil prices lower and took some pressure off US inflation expectations, narrowing the yield advantage of the dollar. The risk of Japanese intervention continues to discourage yen selling, though stronger-than-expected US private payrolls have kept a December Fed hike firmly in play. Friday’s US jobs report is the next test of whether Treasury yields and the dollar can regain ground. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
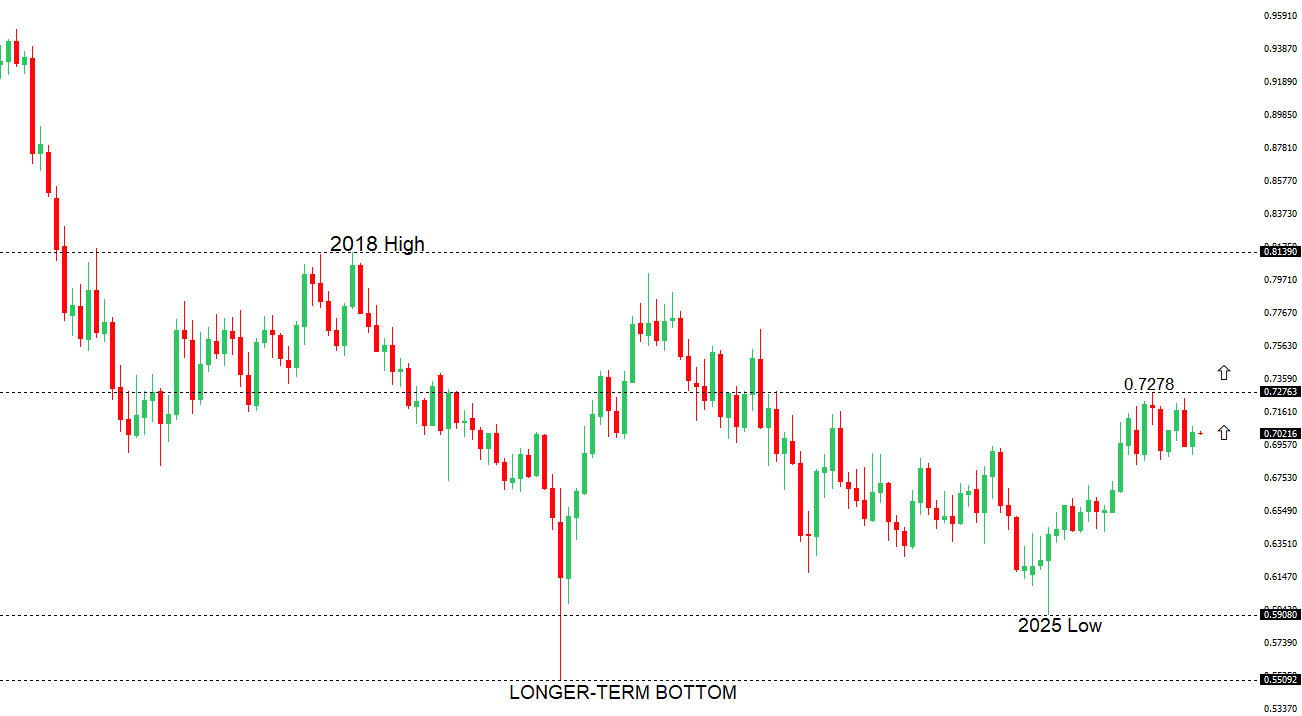 | ||
| R2 0.7100 - Figure - Medium R1 0.7068 - 29 October high - Medium S1 0.6954 - 4 November low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar is firmer for a second straight session, helped by broad US dollar weakness and falling Treasury yields following the US midterm elections. The rebound has been tentative, with Tuesday’s dovish RBA hike tempering expectations for further tightening. The RBA raised the cash rate to 4.85% but dropped its explicit reference to possible further hikes and flagged rising unemployment risks, making a December move less likely. That leaves the Aussie’s near-term direction largely in the hands of the US dollar, with Friday’s payrolls report and Fed commentary the next tests of whether Treasury yields can extend their decline. | ||
| Suggested reading | ||
| Who has to leave the Federal Reserve next?, D. Wessel, Brookings (November 2, 2026) France’s colonial battle to control African money, R. Wigglesworth, Financial Times (November 4, 2026) | ||