 | ||
| 22nd October 2026 | view in browser | ||
| Earnings offer cover, oil raises the stakes | ||
| Markets head into Thursday caught between earnings optimism and geopolitical unease, with a softer dollar, cautious equities and firmer oil reflecting the competing forces shaping global sentiment. | ||
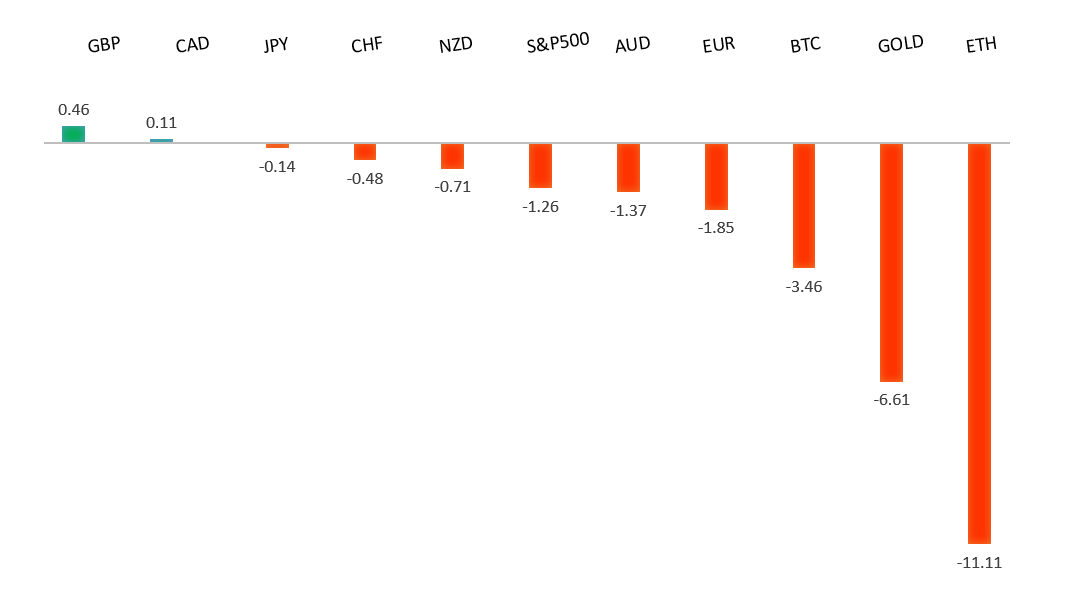
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
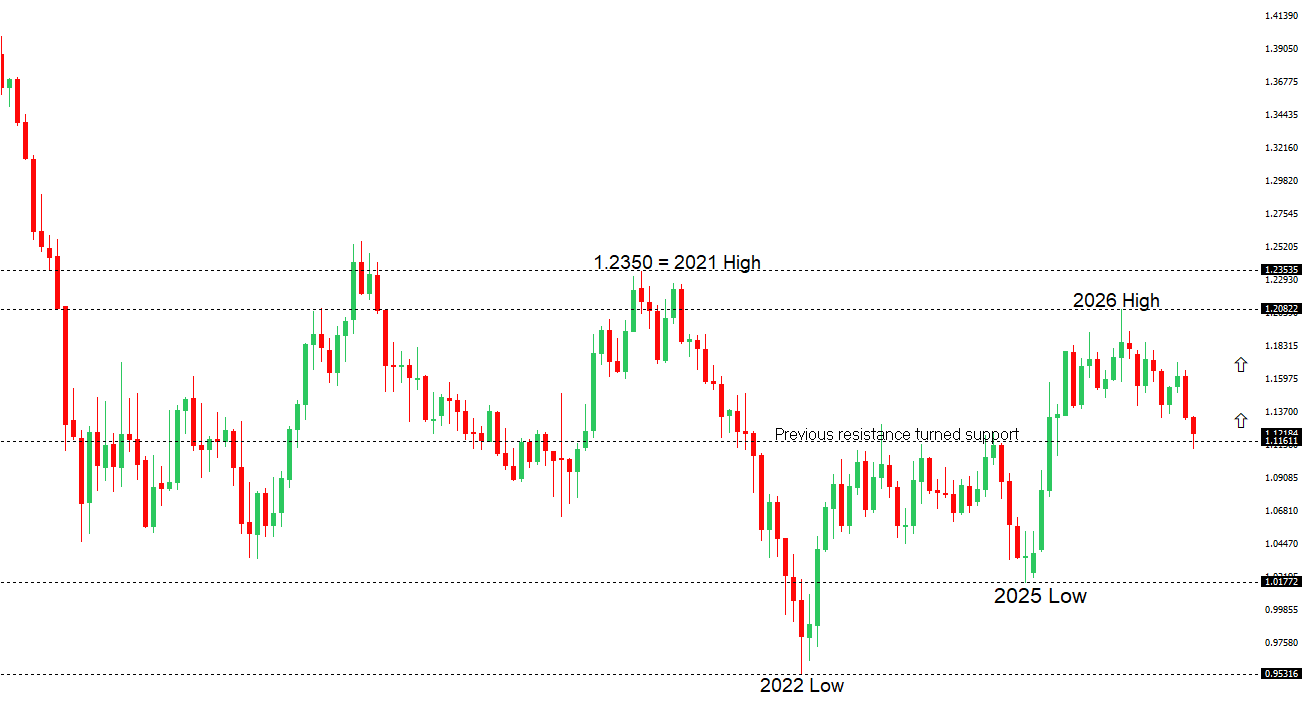 | ||
| R2 1.1337 - 1 October high - Medium R1 1.1270 - 16 October high - Medium S1 1.1181 - 19 Octoberber low - Medium S2 1.1113 - 14 Octoberber/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro is holding modest gains as expectations for a Fed pause next week temper dollar demand, although French fiscal concerns continue to limit upside. Rising French borrowing costs and unrest over public service cuts have reinforced doubts about the government’s ability to rein in its deficit. Even so, the euro’s resilience to higher natural gas prices and bond market stress suggests much of the negative news may already be reflected in positioning. Policy expectations offer some support, with the ECB widely expected to hold next week while markets anticipate a hike before year-end. Attention now turns to comments from ECB policymaker Panetta and whether the approaching central bank decisions provide enough clarity to break the current stalemate. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
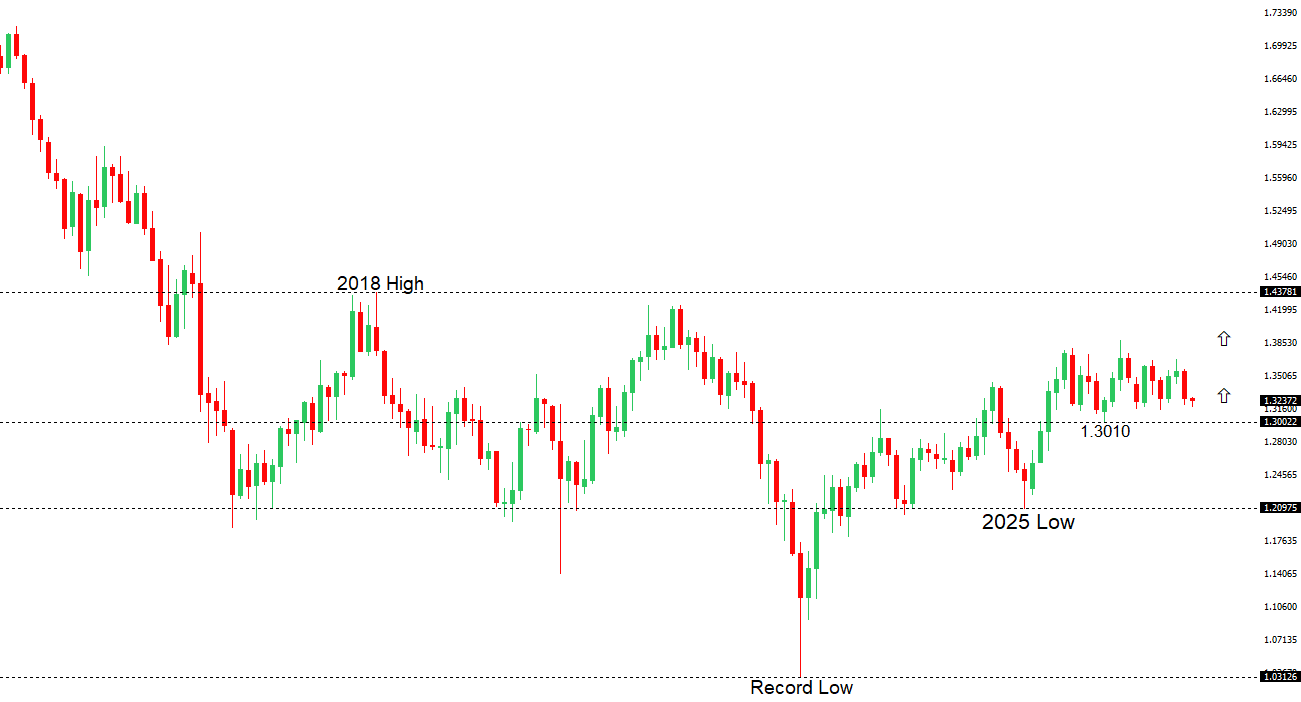 | ||
| R2 1.3498 - 16 September high - Medium R1 1.3410 - 20 October high - Medium S1 1.3297 - 20 October low - Medium S2 1.3137 - 14 October/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound remains supported by rising expectations for a Bank of England rate hike in November after UK inflation climbed to an 11-month high in September, while declining US Treasury yields and a subdued dollar have provided an additional lift. The key driver is the relative interest rate outlook, with renewed UK inflation pressure reinforcing expectations for tighter monetary policy and helping sterling preserve its recent gains. However, Middle East tensions and elevated oil prices remain potential constraints, as further energy inflation could reinforce expectations for a December Fed hike, while any deterioration in risk sentiment could revive safe-haven dollar demand. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
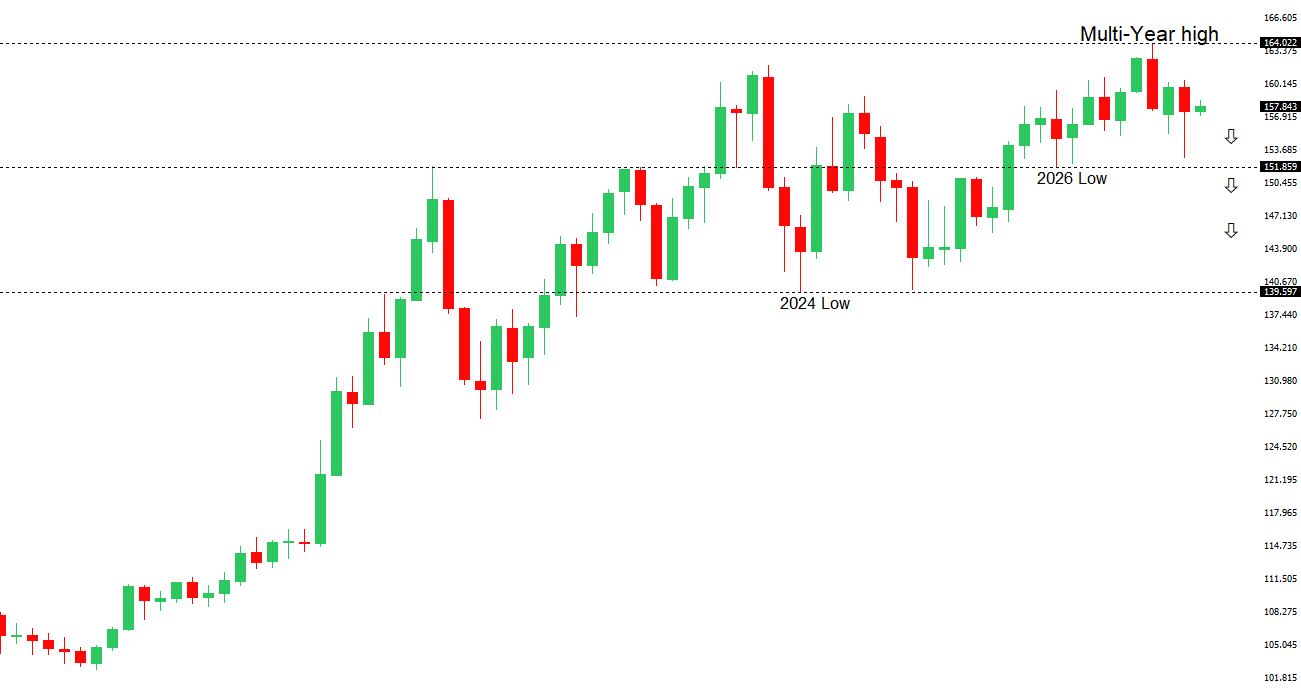 | ||
| R2 159.04 - 24 September high - Strong R1 158.26 - 22 October high - Medium S1 157.00 - Figure - Medium S2 156.37 - 30 September low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen is drawing support from falling US Treasury yields and a broadly softer dollar, with a narrowing yield differential helping the currency recover. Governor Ueda’s recent hawkish remarks have also reinforced expectations for further Bank of Japan tightening, potentially as soon as December, while concern over possible Japanese intervention adds another layer of support. However, the recovery remains vulnerable to a reversal in US yields, as energy-related inflation concerns keep the prospect of further Fed tightening alive. Escalating Middle East tensions could also support demand for the dollar, leaving the yen’s outlook sensitive to energy prices and policy guidance from next week’s Fed and BoJ meetings. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
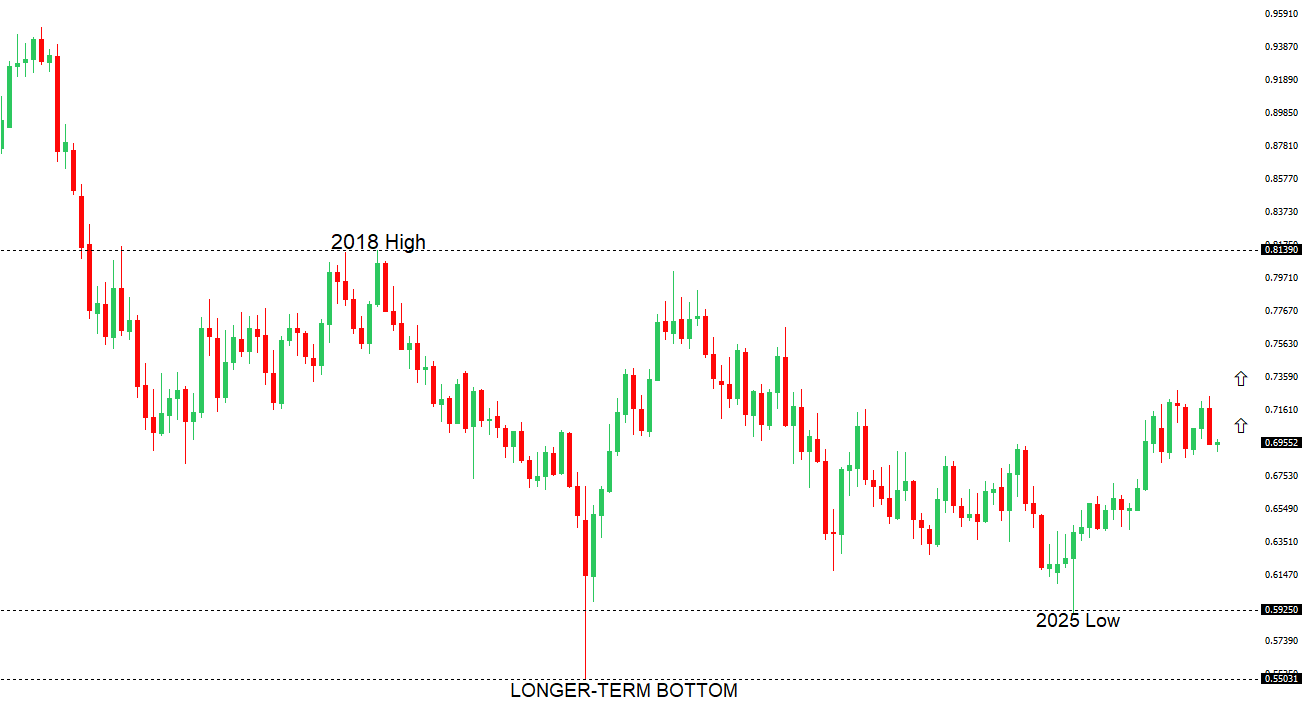 | ||
| R2 0.7046 - 24 September high - Strong R1 0.7037 - 22 October high - Medium S1 0.6970 - 20 October low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar has softened as Middle East tensions weigh on risk appetite and encourage safe-haven demand for the US dollar, offsetting support from increasingly hawkish RBA expectations. Deputy Governor Hauser’s warning that the inflation outlook has deteriorated materially has lifted expectations for another rate increase as soon as November, with domestic capacity constraints, technology prices, and strong data center investment adding to inflation concerns. These pressures are supporting Australian interest rate expectations, but the currency remains sensitive to geopolitical developments and the outlook for US monetary policy. With the Fed keeping its options open, upcoming US data and moves in Treasury yields remain key catalysts for whether the Aussie can regain momentum. | ||
| Suggested reading | ||
| How to Tell a Great Growth Stock From a Trap, C. Reilly, Grow or Die (October 19, 2026) The hidden cost of fast furniture waste, M. Speed, Financial Times (October 20, 2026) | ||