 | ||
| 21st October 2026 | view in browser | ||
| Earnings carry the market, oil carries the risk | ||
| Global markets head into Wednesday with resilient earnings supporting risk appetite, while stubborn inflation, elevated oil prices and geopolitical tensions keep investors cautious. | ||
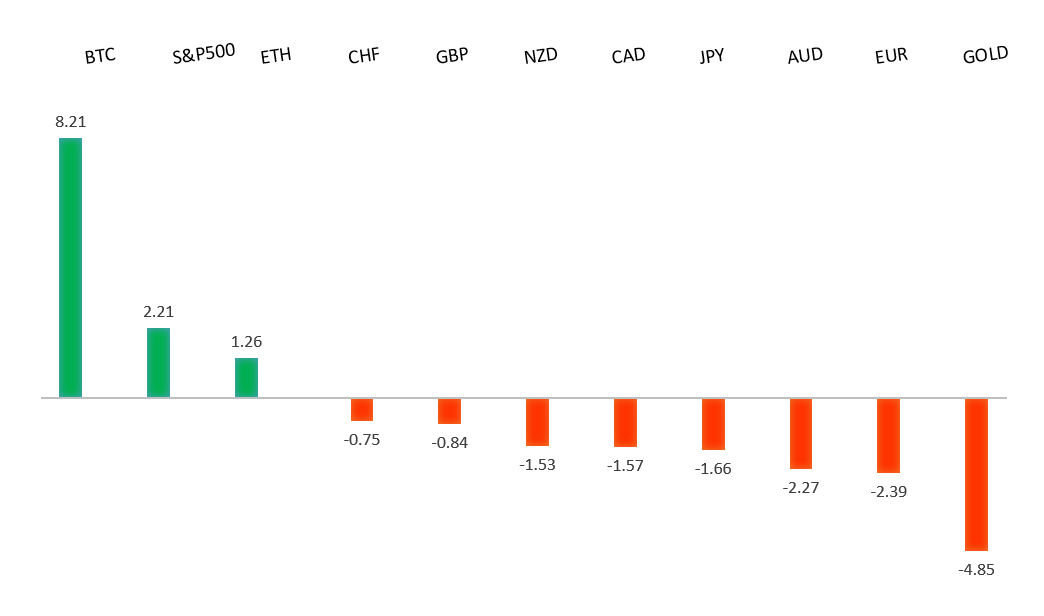
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro continues to show signs of wanting to carve out a major bottom after trading down to a 20-year low in 2022. Setbacks should be exceptionally well supported above 1.1000 on a weekly close basis ahead of the next major upside extension back above 1.2000. | ||
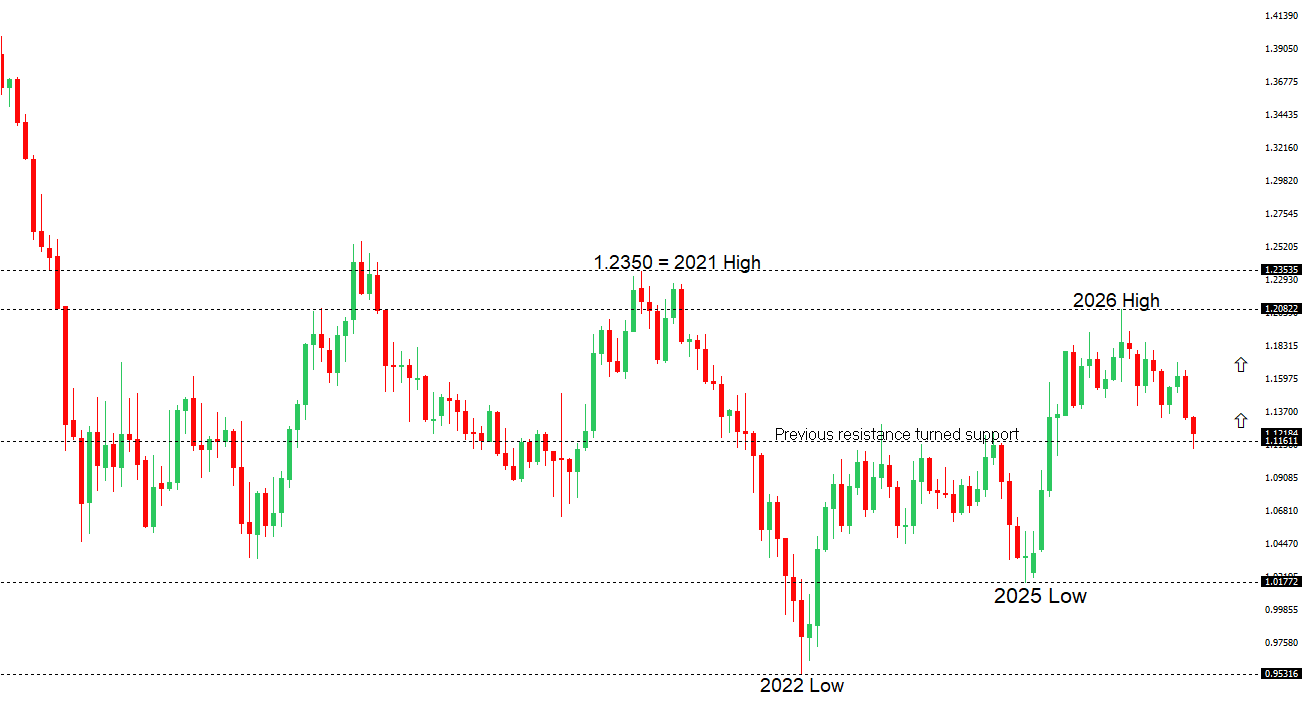 | ||
| R2 1.1337 - 1 October high - Medium R1 1.1270 - 16 October high - Medium S1 1.1181 - 19 Octoberber low - Medium S2 1.1113 - 14 Octoberber/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro is under pressure as persistent political and fiscal strains in France weigh on sentiment, with elevated French borrowing costs relative to Germany highlighting investor concerns. Widespread protests and further curfew measures are keeping domestic risks in focus, while mixed German investor confidence data suggest the region’s largest economy remains on a slow recovery path, offering limited support for the currency. On the US side, expectations for a Fed pause this month are tempered by markets continuing to anticipate another increase in December, helping underpin the dollar. Warsh’s reluctance to prejudge upcoming decisions leaves the outlook sensitive to incoming data, while comments from Lagarde and other senior ECB officials will be watched for guidance on European monetary policy. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
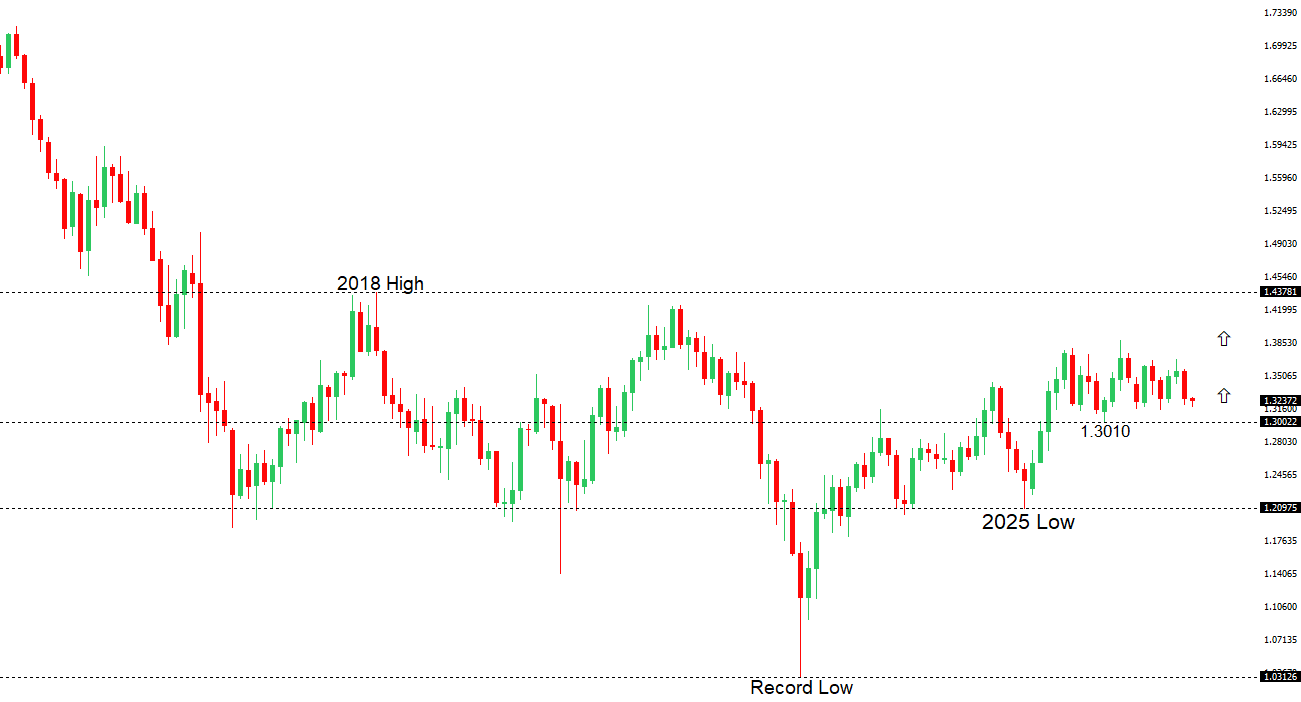 | ||
| R2 1.3410 - 20 October high - Medium R1 1.3400 - Figure - Medium S1 1.3297 - 20 October low - Medium S2 1.3137 - 14 October/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound has eased ahead of UK inflation data, but resilient labor market conditions continue to underpin expectations for a Bank of England rate hike in November. An unexpected decline in unemployment and firmer wage growth suggest domestic price pressures remain persistent despite falling vacancies, while policymaker Megan Greene has warned that higher energy costs could feed into broader inflation and pay demands. September’s CPI release is the immediate catalyst, with a stronger reading likely to reinforce the case for tightening, although an increase is already largely priced in. Meanwhile, Fed Chair Warsh’s reluctance to signal the next US rate decision leaves the dollar sensitive to incoming data, while the approaching UK budget adds another source of uncertainty for sterling. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
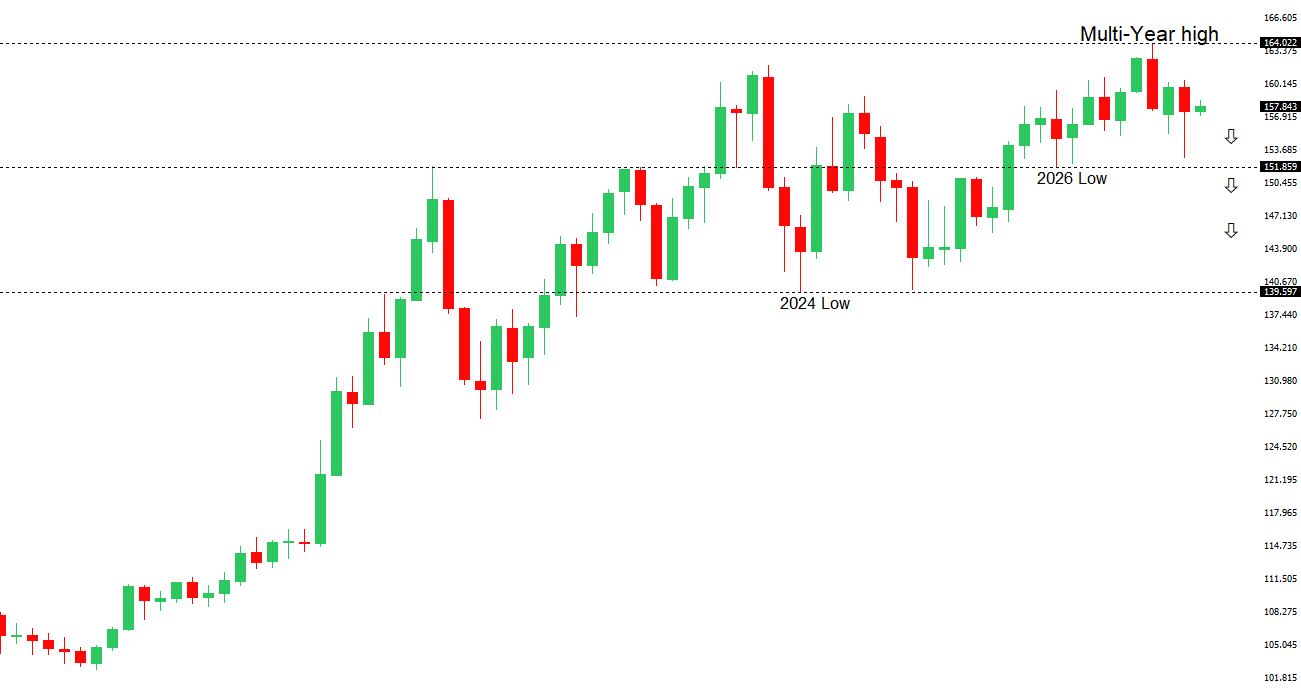 | ||
| R2 159.04 - 24 September high - Strong R1 158.95 - 14 October high - Medium S1 157.52 - 8 October low - Medium S2 156.37 - 30 September low - Strong | ||
| USDJPY: fundamental overview | ||
| The yen remains under pressure as Japan’s larger-than-expected September trade deficit and slower export growth highlight vulnerability to elevated energy costs and external uncertainty, although the shortfall narrowed from August. Finance Minister Katayama’s emphasis on coordination with the Bank of Japan and expanding supply capacity without accelerating inflation leaves investors focused on the timing of further monetary tightening. Meanwhile, US inflation data and Fed Chair Warsh’s neutral policy stance keep the outlook for US interest rates central to dollar-yen trading, with a softer US yield backdrop offering potential relief for the Japanese currency. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
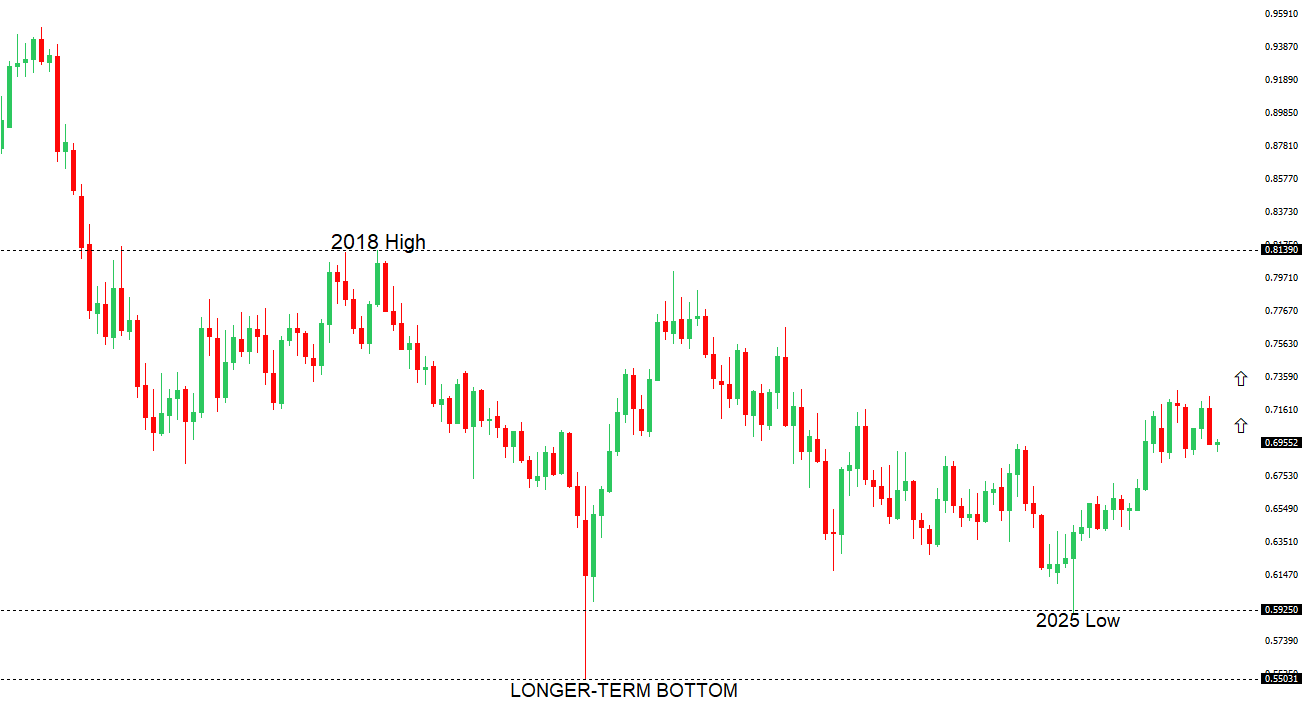 | ||
| R2 0.7046 - 24 September high - Strong R1 0.7030 - 21 October high - Medium S1 0.6970 - 20 October low - Medium S2 0.6894 - 15 October low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar remains supported near its monthly high as hawkish RBA commentary keeps further tightening in focus ahead of the November policy meeting. Deputy Governor Hauser’s warning that underlying inflation could exceed expectations, alongside Assistant Governor Christopher Kent’s remarks about rising neutral interest rates, has reinforced the prospect of borrowing costs staying higher for longer. Better-than-expected Chinese growth has provided additional support given Australia’s close trade ties with China. However, renewed US dollar demand is limiting gains as oil-driven inflation concerns sustain expectations for further Fed tightening. Developments surrounding potential US-Iran talks remain important, with any easing in tensions potentially improving risk appetite and reducing energy-related inflation pressures. | ||
| Suggested reading | ||
| Reality Bites, J. Calhoun, Alhambra Investments (October 18, 2026) Dislodging the dollar – Not likely, M. Rzepczynski, DSGMV (October 17, 2026) | ||