 | ||
| 30th September 2026 | view in browser | ||
| The quarter turns, the questions stay | ||
| Markets enter Wednesday with easing oil prices offering some relief, while persistent inflation risks, yen strength and quarter-end flows keep investors cautious ahead of key US data. | ||
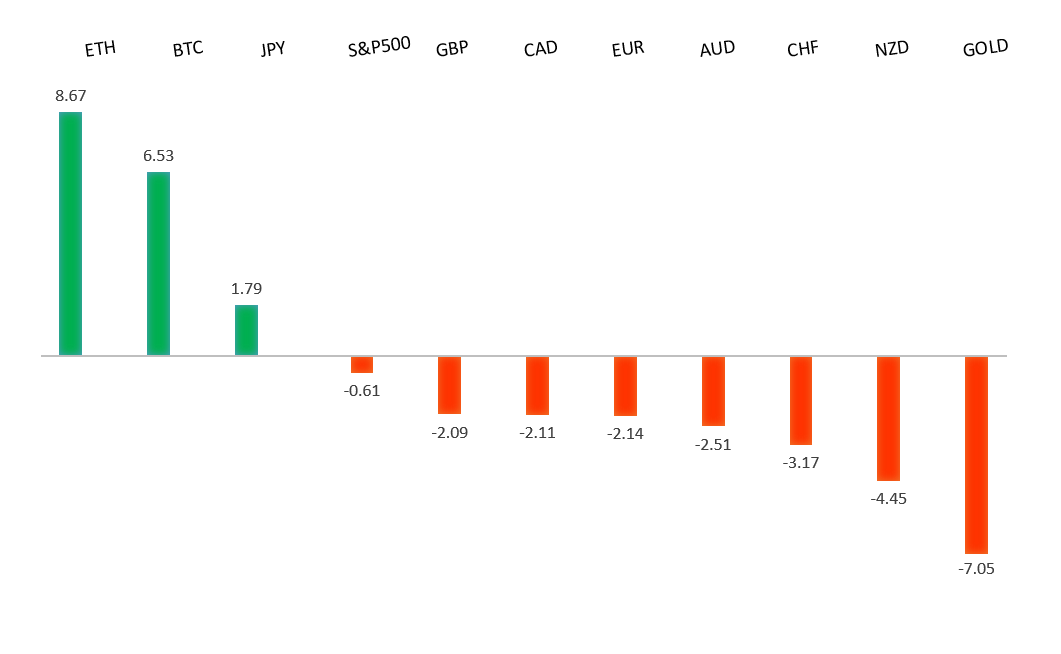
| Performance chart 30day v. USD (%) | ||
 | ||
| Technical & fundamental highlights | ||
| EURUSD: technical overview | ||
| The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1300. | ||
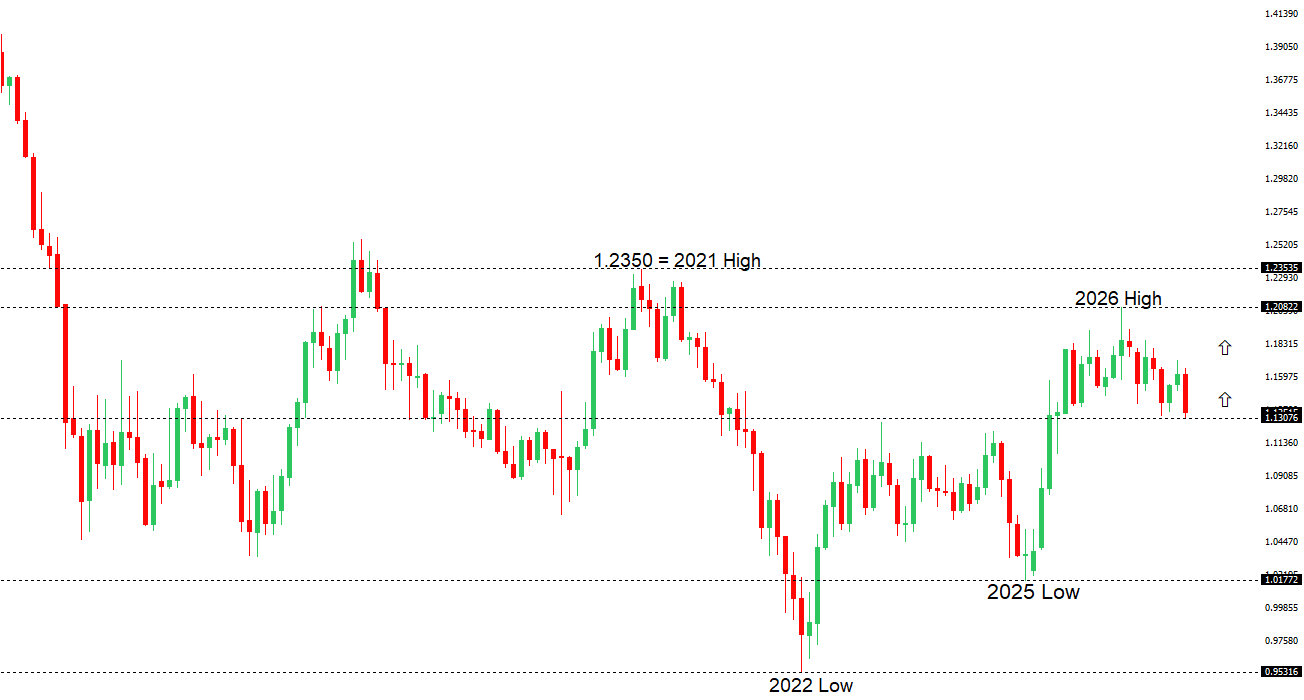 | ||
| R2 1.1498 - 17 September high - Medium R1 1.1412 - 25 September high - Medium S1 1.1329 - 30 September low - Medium S2 1.1312 - 29 September/2026 low - Strong | ||
| EURUSD: fundamental overview | ||
| The euro remains under pressure as Lagarde’s cautious policy guidance tempers expectations for an October ECB hike, leaving relative interest rate expectations tilted in the Dollar’s favor. Her assessment that tight financial conditions are limiting the spread of higher energy costs into broader inflation has reduced the urgency for further tightening. Germany’s weaker-than-expected retail sales rebound adds to concerns over consumer demand, with spending recovering only partially from July’s sharp decline and remaining below year-earlier levels. Meanwhile, Europe’s exposure to elevated energy costs and political uncertainty in France continues to weigh on sentiment. Attention now turns to German and French inflation releases and incoming US data, which could either revive support for ECB tightening or reinforce the euro’s yield disadvantage. | ||
| GBPUSD: technical overview | ||
| The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates. | ||
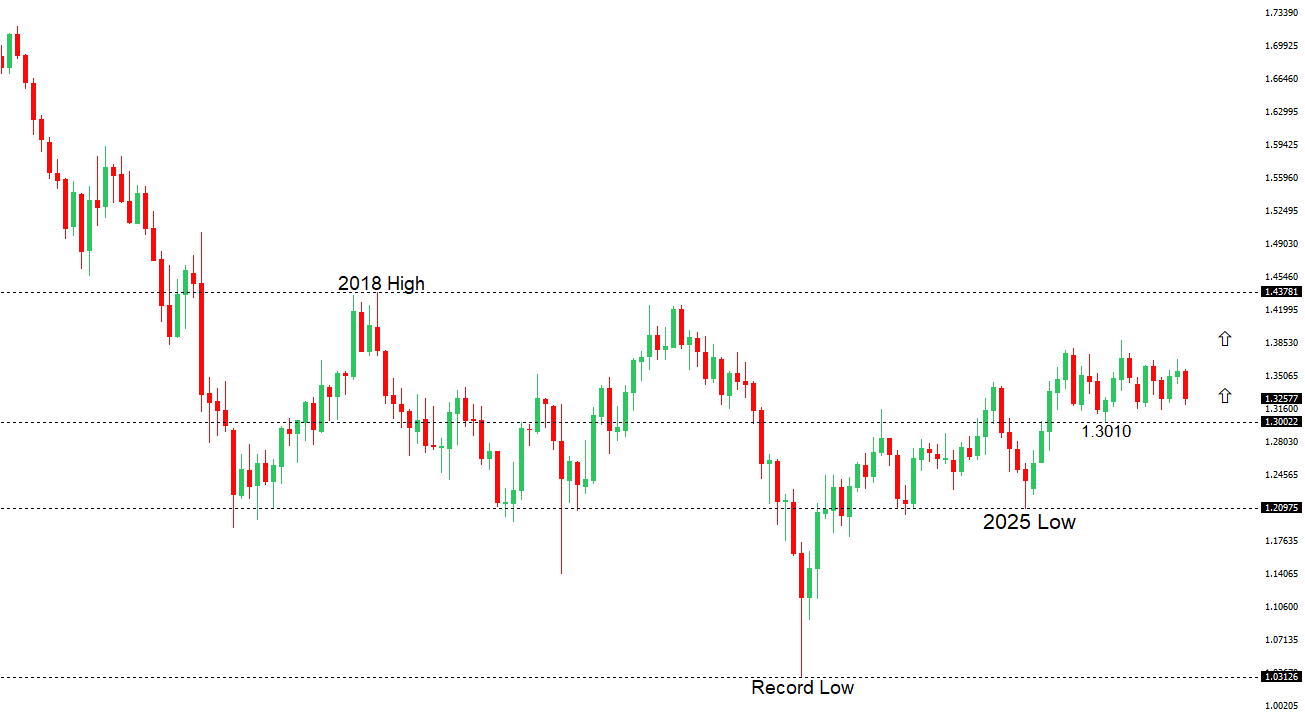 | ||
| R2 1.3407 - 17 September high - Medium R1 1.3300 - Figure - Medium S1 1.3202 - 29 September low - Medium S2 1.3140 - 24 June/2026 low - Strong | ||
| GBPUSD: fundamental overview | ||
| The pound remains under pressure against the Dollar as elevated US Treasury yields and expectations of further Fed tightening overshadow support from prospective Bank of England rate increases. Sterling’s domestic backdrop is challenging, with higher energy costs adding to inflation risks while weak labor demand and sluggish private sector momentum limit the economy’s ability to absorb tighter policy. BoE officials remain divided over the need to raise rates, with Alan Taylor arguing that evidence of broader inflation persistence is still insufficient. Meanwhile, weaker mortgage approvals highlight pressure from borrowing costs, and uncertainty over tax and spending decisions ahead of the October Budget adds another constraint on sentiment. Together, these forces leave sterling caught between inflation concerns that support higher rates and growth risks that undermine their currency benefit. | ||
| USDJPY: technical overview | ||
| The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58. The market would need to get back above 160.00 to take the immediate pressure off the downside. | ||
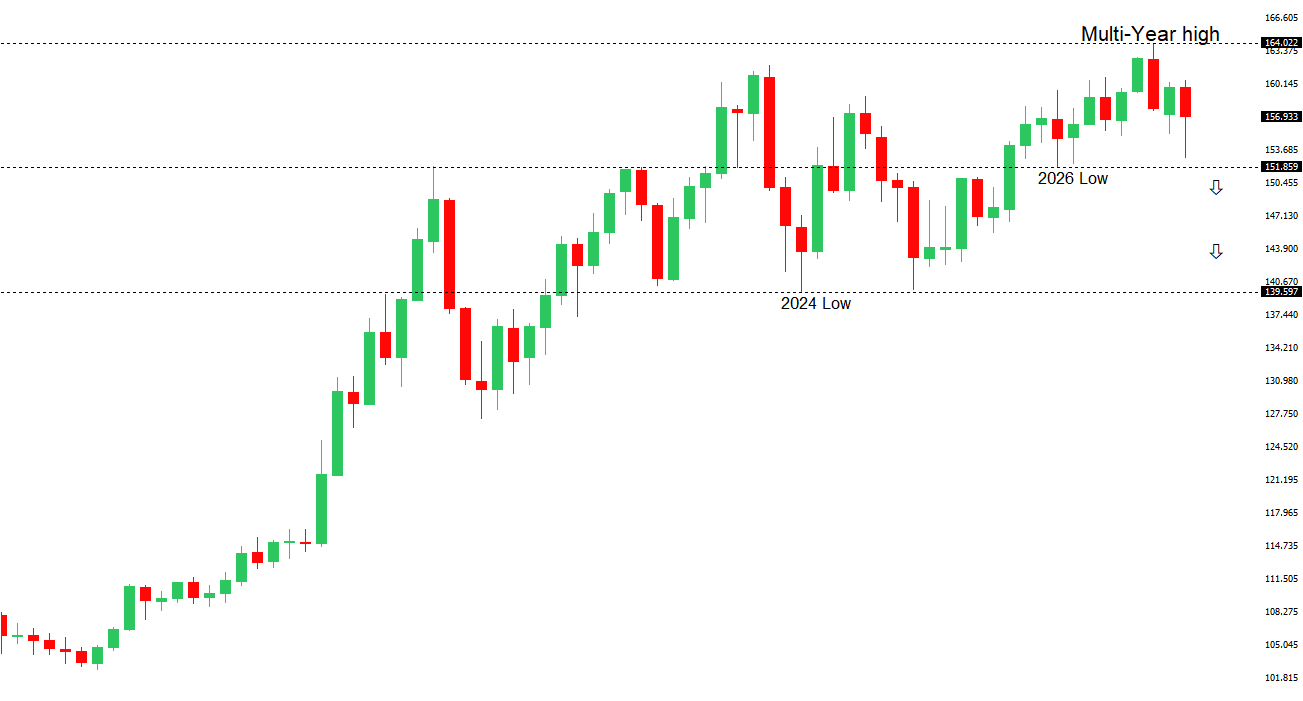 | ||
| R2 159.04 - 24 September high - Strong R1 157.86 - 28 September high - Medium S1 156.37 - 30 September low - Medium S2 155.33 - 17 September low - Medium | ||
| USDJPY: fundamental overview | ||
| The yen is finding support from increasingly forceful intervention warnings out of Tokyo, with renewed coordination between Japanese and US officials making investors more cautious about selling the currency. The Bank of Japan’s continued policy normalization and rising Japanese yields are also providing support, while comments from Fed President Williams pushing back against the need for immediate further tightening have eased some pressure from the Dollar. Nevertheless, elevated US yields remain a headwind, leaving the yen’s recovery dependent on both the credibility of official intervention threats and the outlook for relative interest rates. Upcoming US inflation and employment data will be key to whether that recovery can extend. | ||
| AUDUSD: technical overview | ||
| There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700. | ||
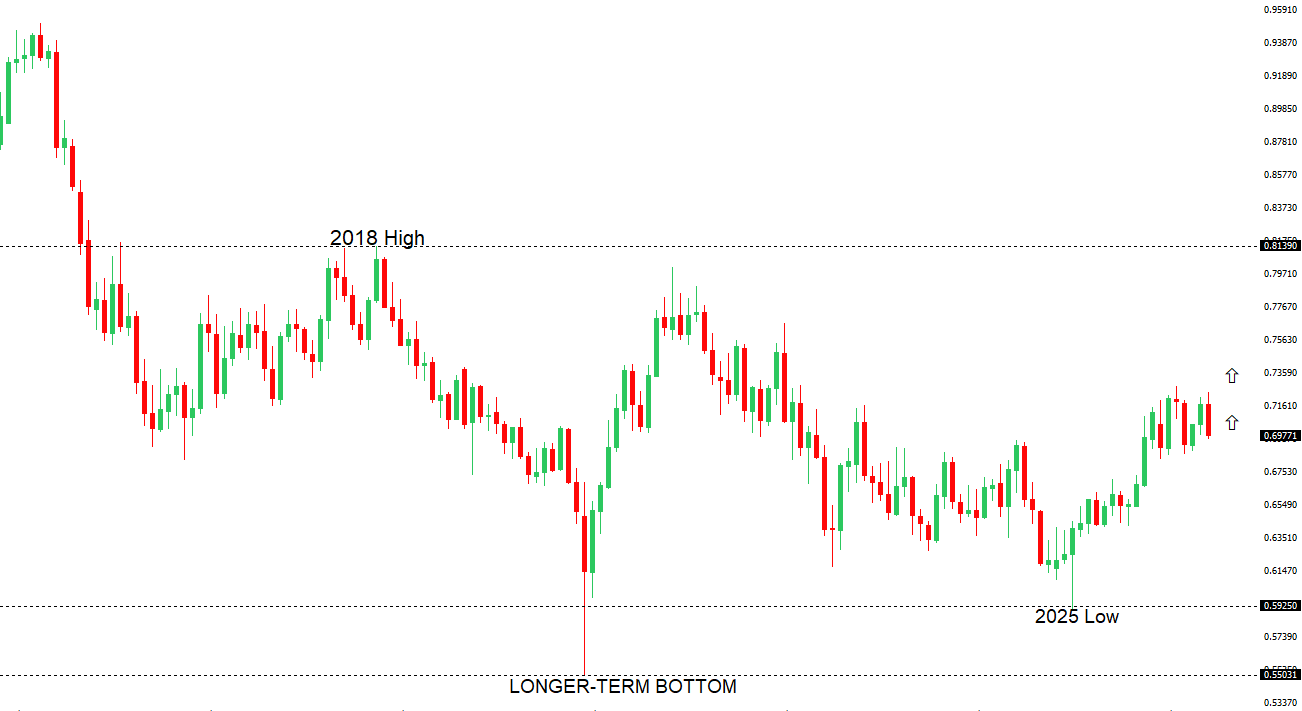 | ||
| R2 0.7142 - 15 September high - Strong R1 0.7046 - 24 September high - Medium S1 0.6958 - 30 September low - Medium S2 0.6922 - 29 July low - Strong | ||
| AUDUSD: fundamental overview | ||
| The Australian dollar is finding some support from persistent domestic inflation, with August CPI accelerating to 4% annually from 3.5%, reinforcing the case for the RBA to keep policy restrictive after its fourth rate increase this year took the cash rate to 4.6%. However, while Governor Bullock left further tightening on the table, her emphasis on allowing previous increases time to work has tempered expectations of an uninterrupted hiking cycle, limiting the Aussie’s benefit from higher rates. Against this backdrop, the currency’s modest recovery remains vulnerable, with attention turning to US PCE inflation for the next steer on Federal Reserve policy and the US dollar. | ||
| Suggested reading | ||
| The bloody history behind the bond market, G. Tett, Financial Times (September 30, 2026) It’s Your Father’s Market, Not One You’re Used To, J. Calhoun, Alhambra (September 27, 2026) | ||