Day Image
14th September 2026 | view in browser
Central Banks enter the geopolitical crossfire

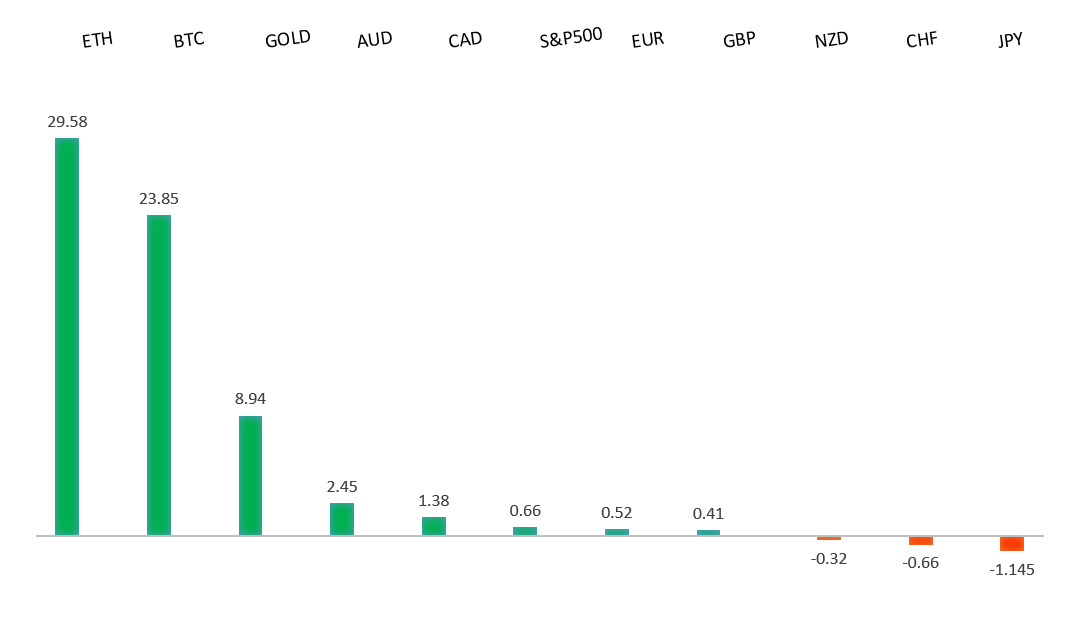
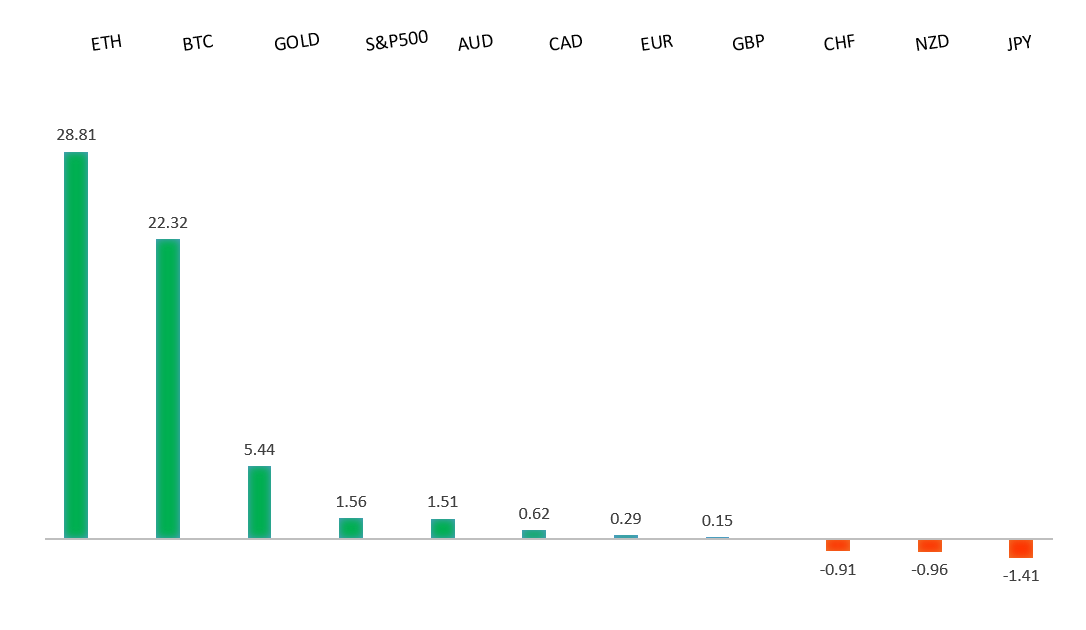
Markets open the week cautiously as escalating Middle East tensions and rising oil prices reinforce inflation concerns, support the dollar and bond yields, and pressure equities ahead of pivotal Fed, BoE and BoJ decisions.


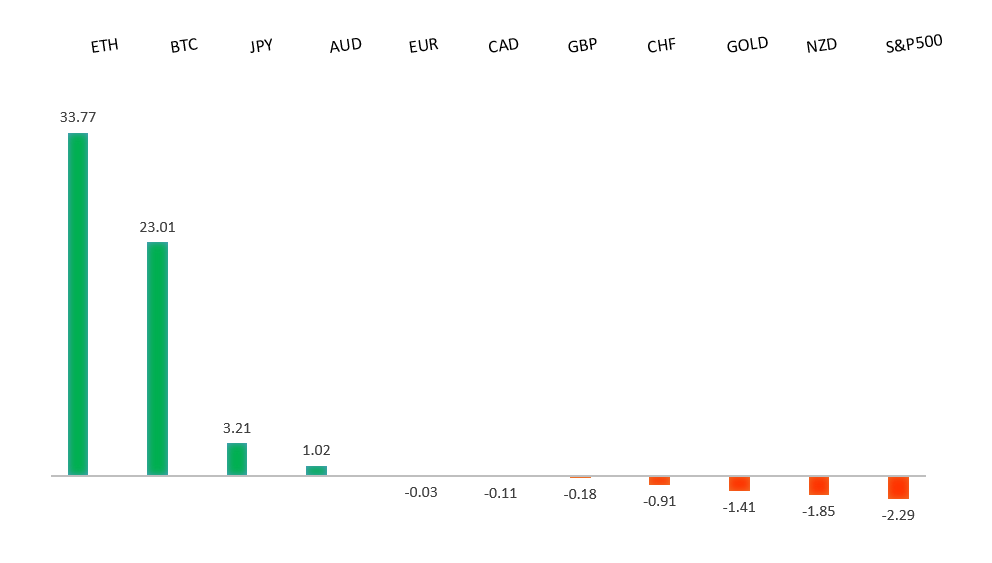
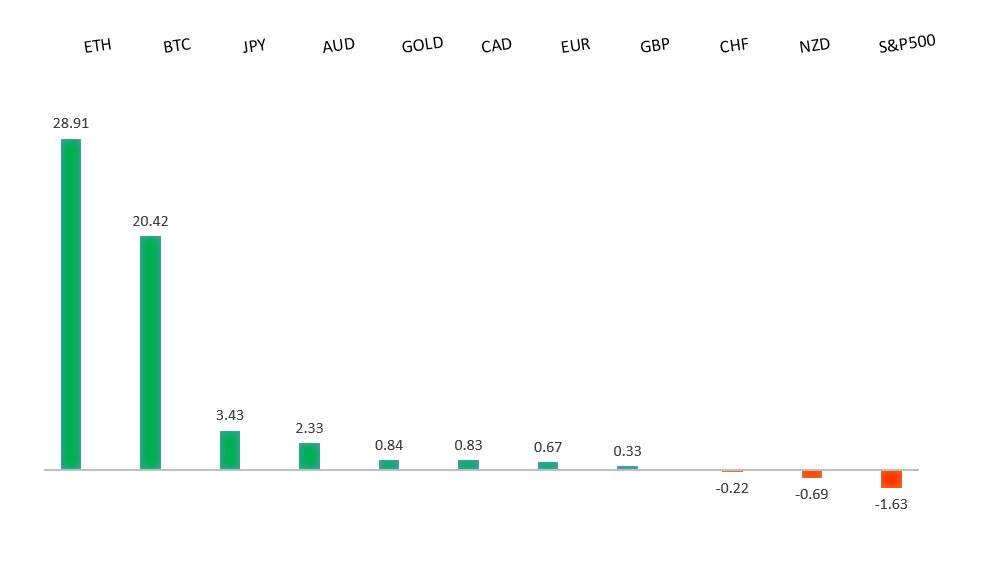
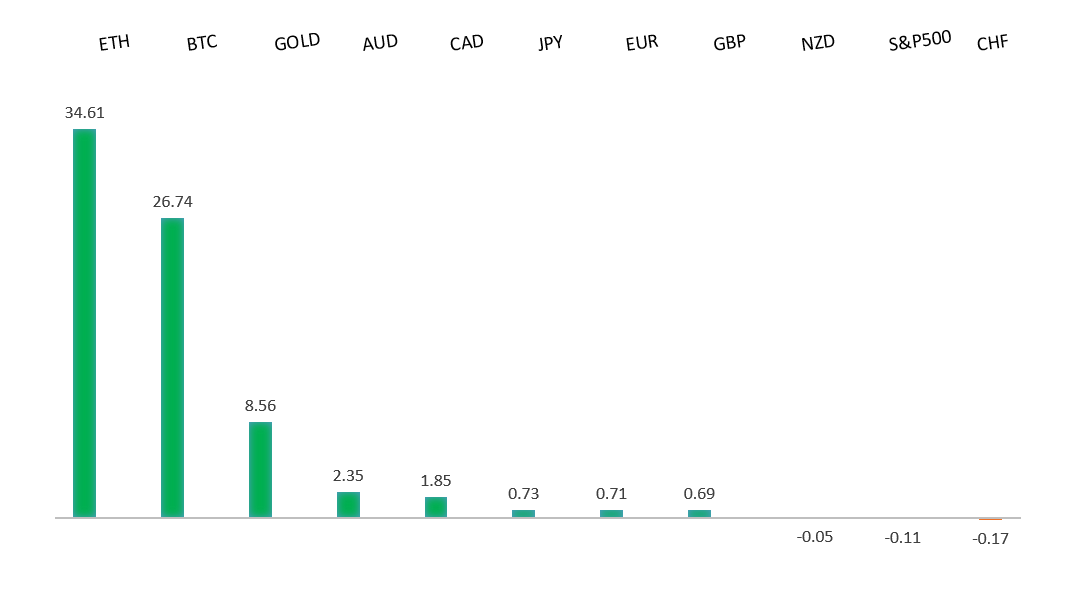
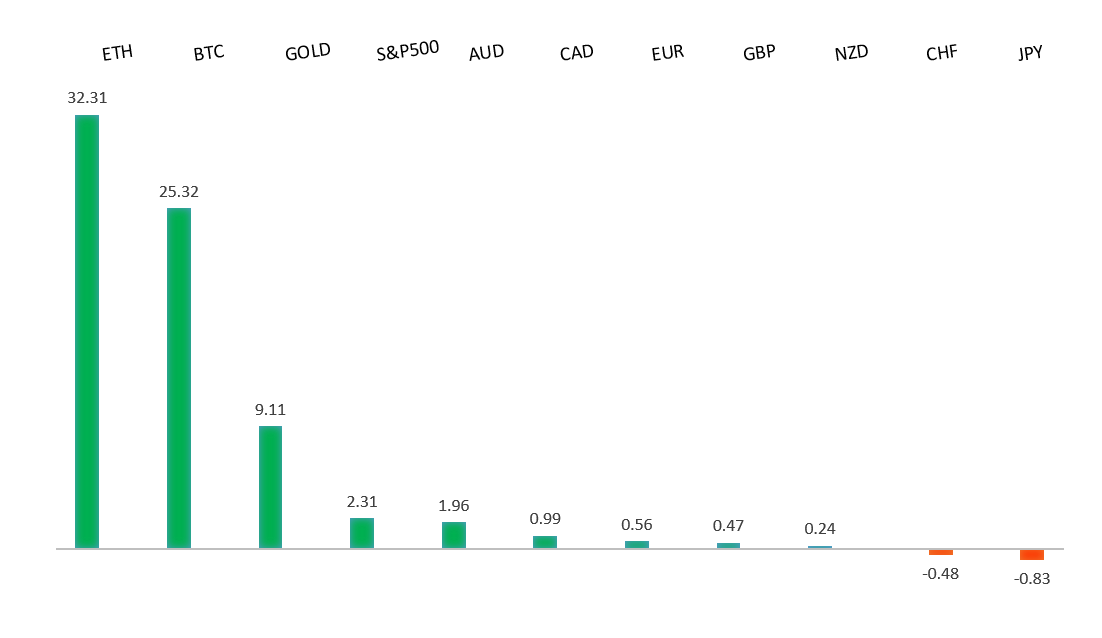
Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
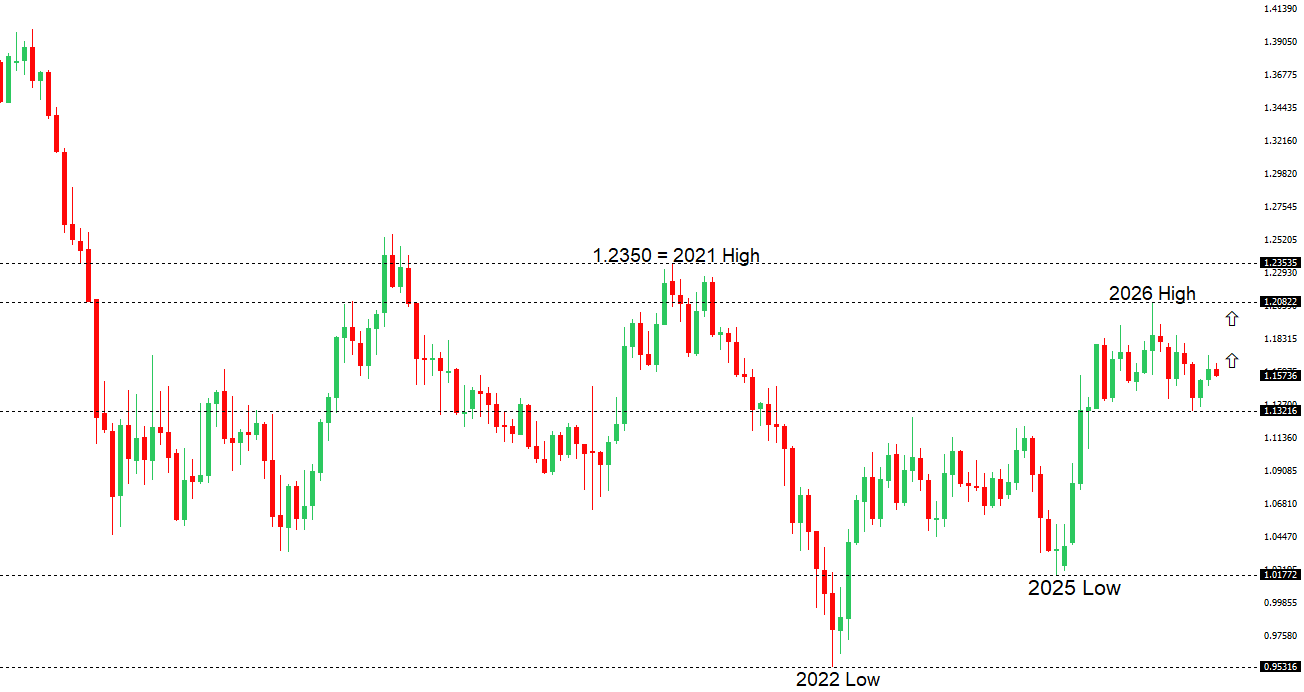
EURUSD: technical overview

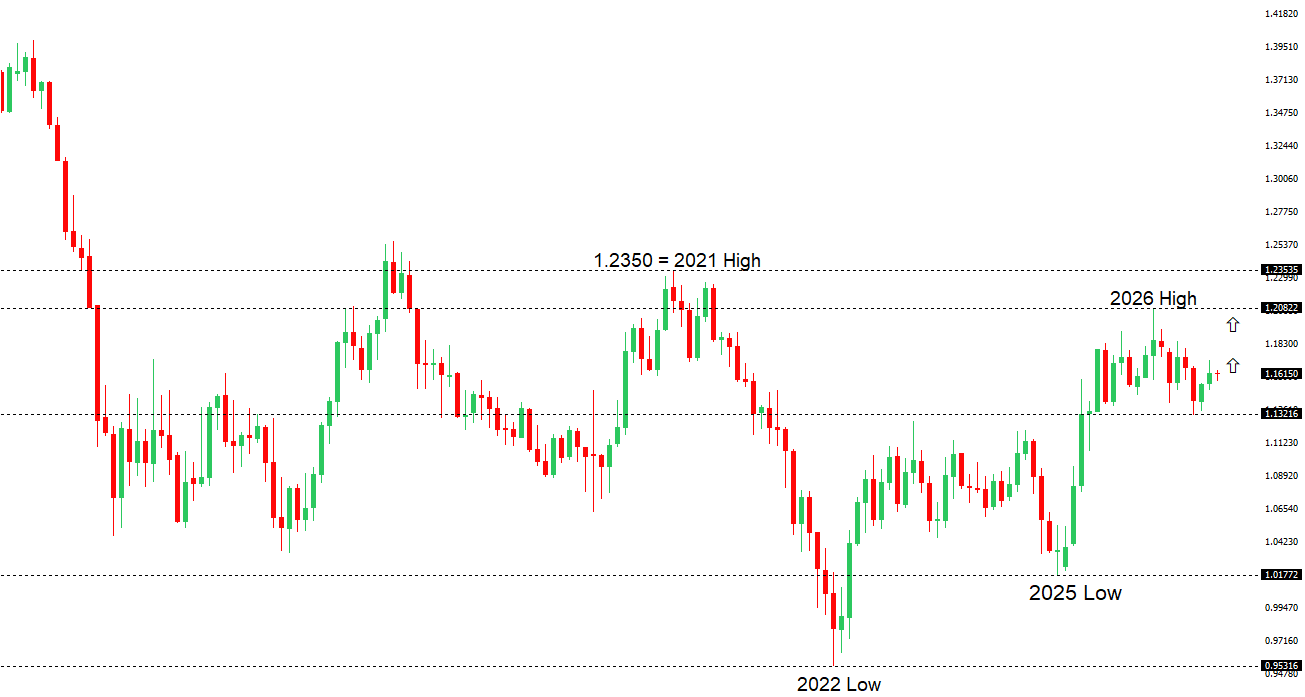
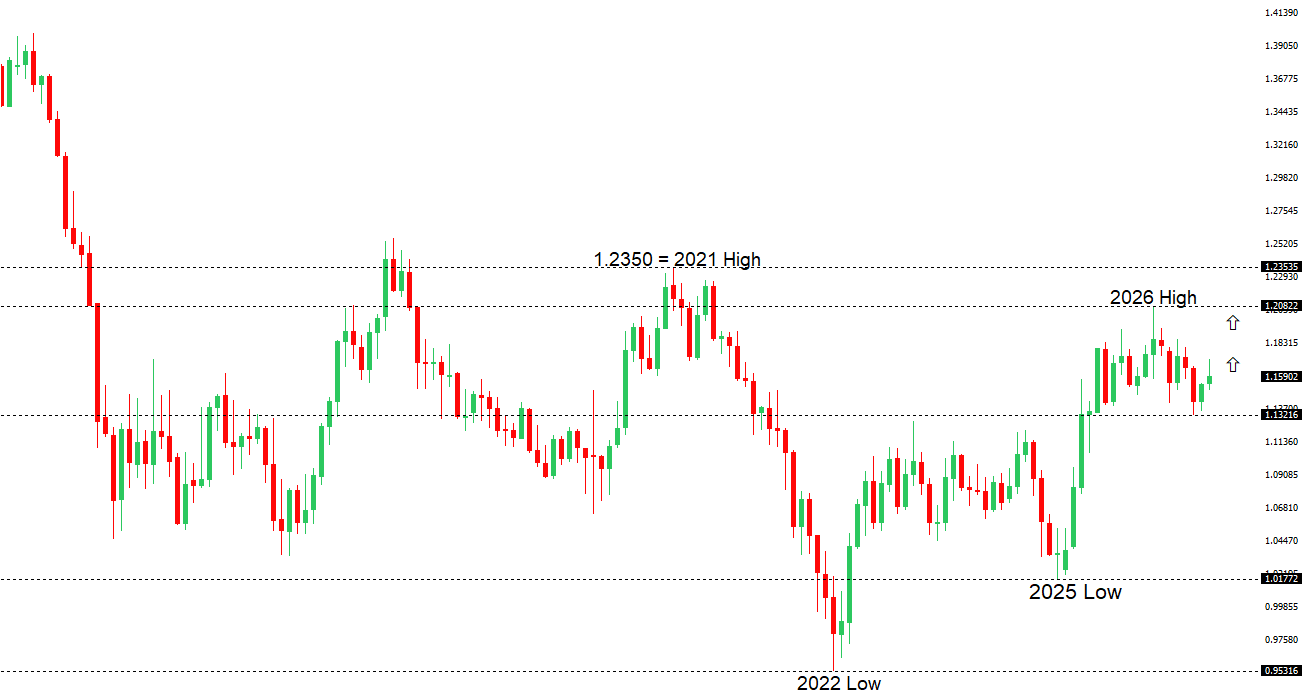
The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has come under pressure below 1.1600, with the dollar benefiting as hotter underlying US inflation and firm producer prices pushed markets toward expecting another Federal Reserve rate hike this week. The ECB’s recent quarter-point increase and broadly hawkish messaging have kept expectations for further European tightening elevated, particularly after updated forecasts showed inflation remaining above target for longer. However, that support has been overshadowed by the more immediate repricing of Fed policy, leaving relative rate expectations tilted in favor of the dollar ahead of Wednesday’s decision.

 
GBPUSD: technical overview

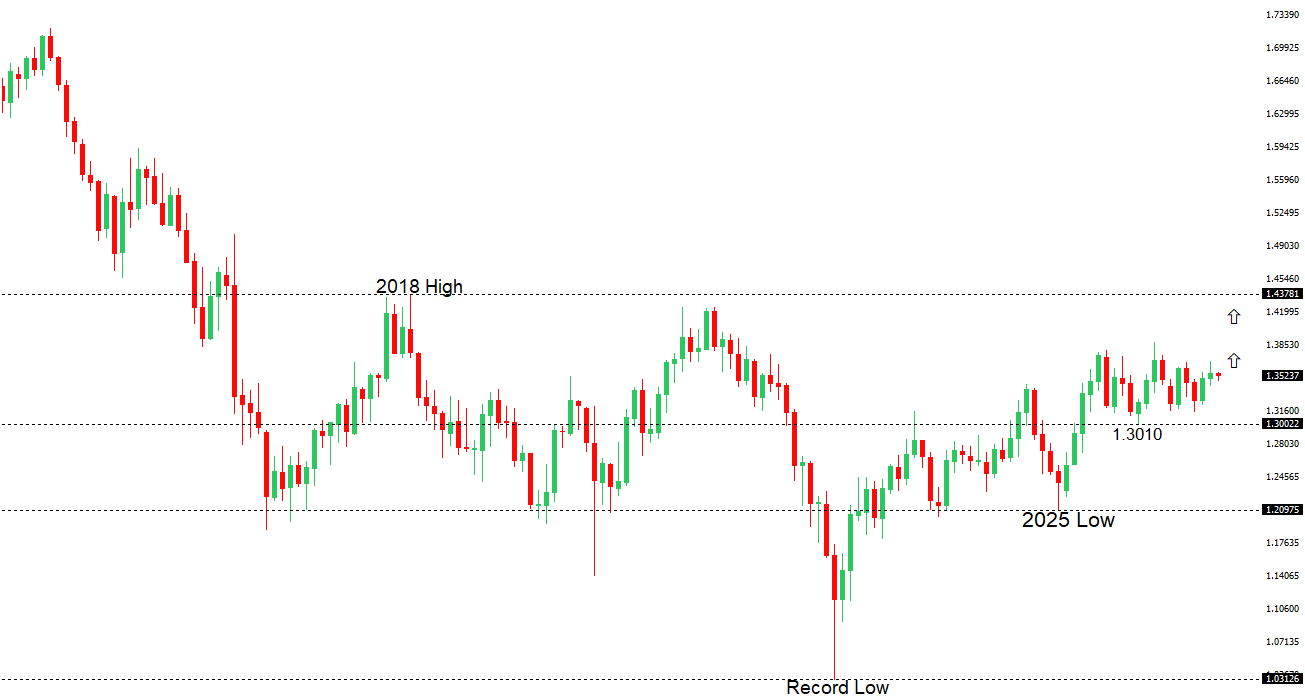
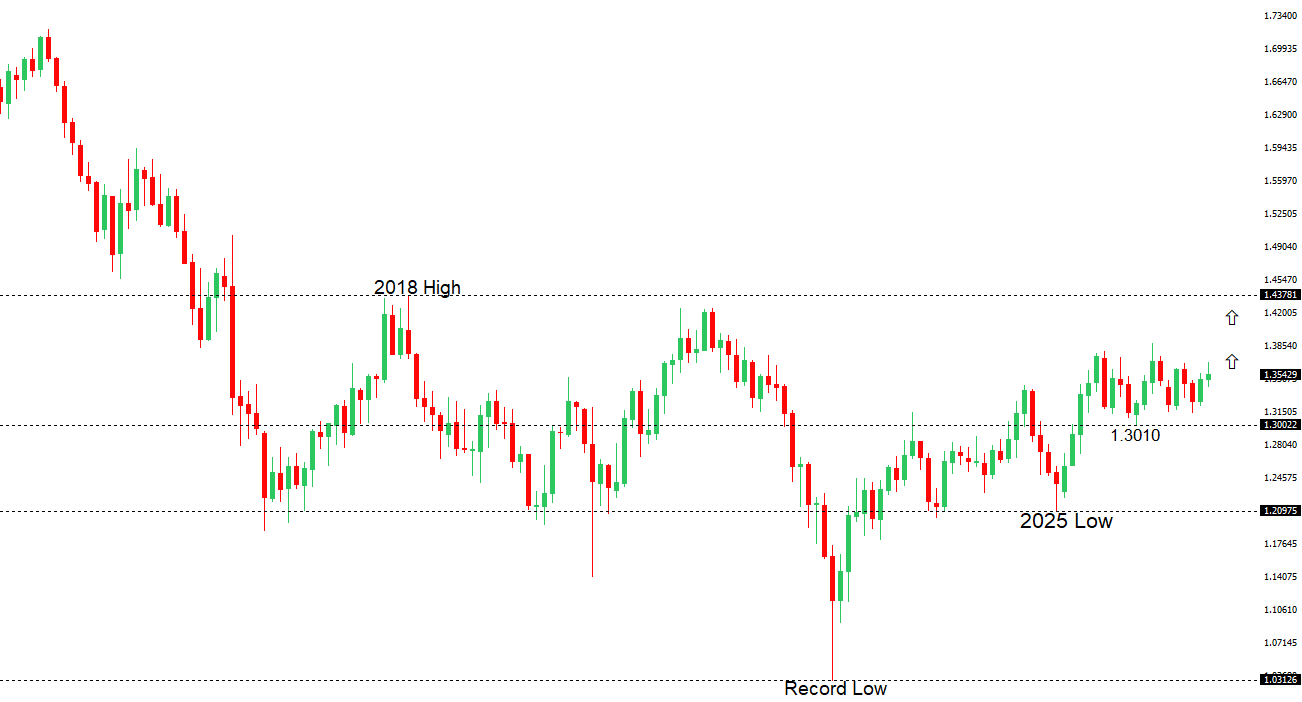
The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3568 - 9 September high - Medium
S1 1.3458 - 11 September low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound has been consolidating above 1.3500 against the dollar, supported by stronger-than-expected UK growth in July and lingering expectations that elevated energy costs could eventually require tighter Bank of England policy. However, Governor Bailey has pushed back against the idea that rate hikes are inevitable, while the BoE is widely expected to leave rates unchanged this week. This has limited sterling demand ahead of Tuesday’s UK employment report and Wednesday’s inflation data, which will shape the outlook for domestic policy. On the other side of the pair, rising expectations for a Federal Reserve rate hike and escalating Middle East tensions have supported the safe-haven dollar, leaving GBPUSD caught between resilient UK fundamentals and a firmer US currency.

 
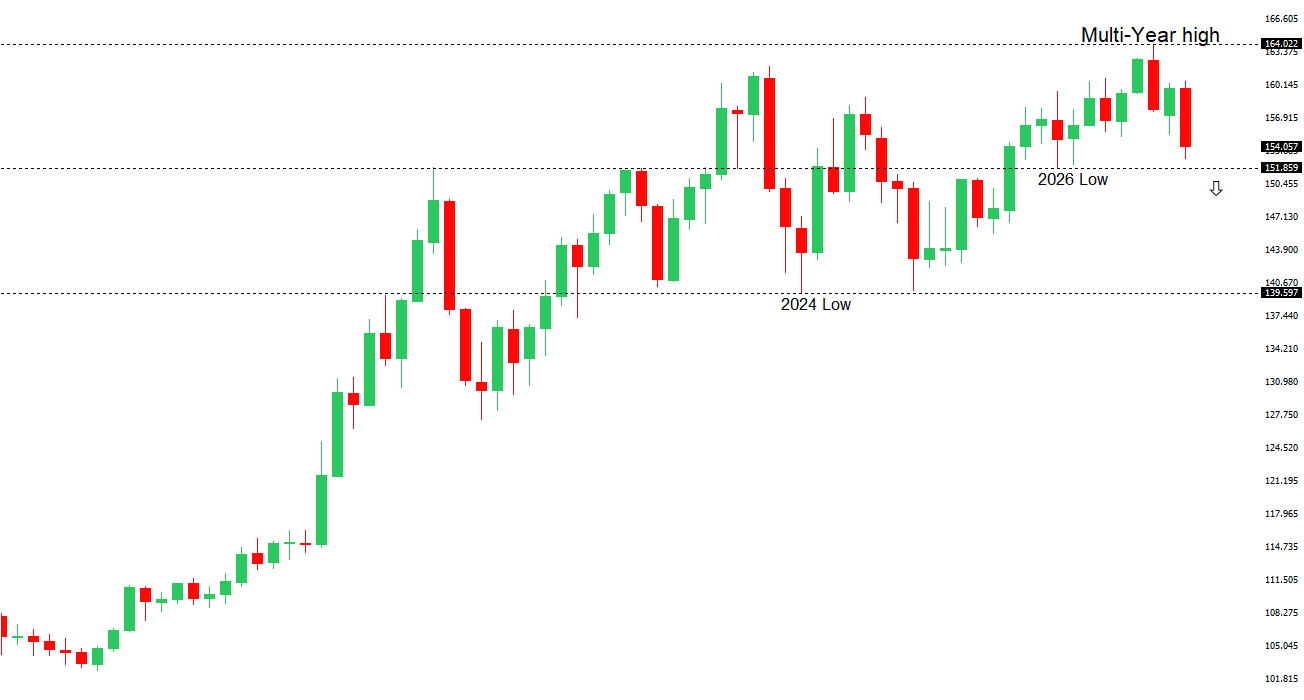
USDJPY: technical overview

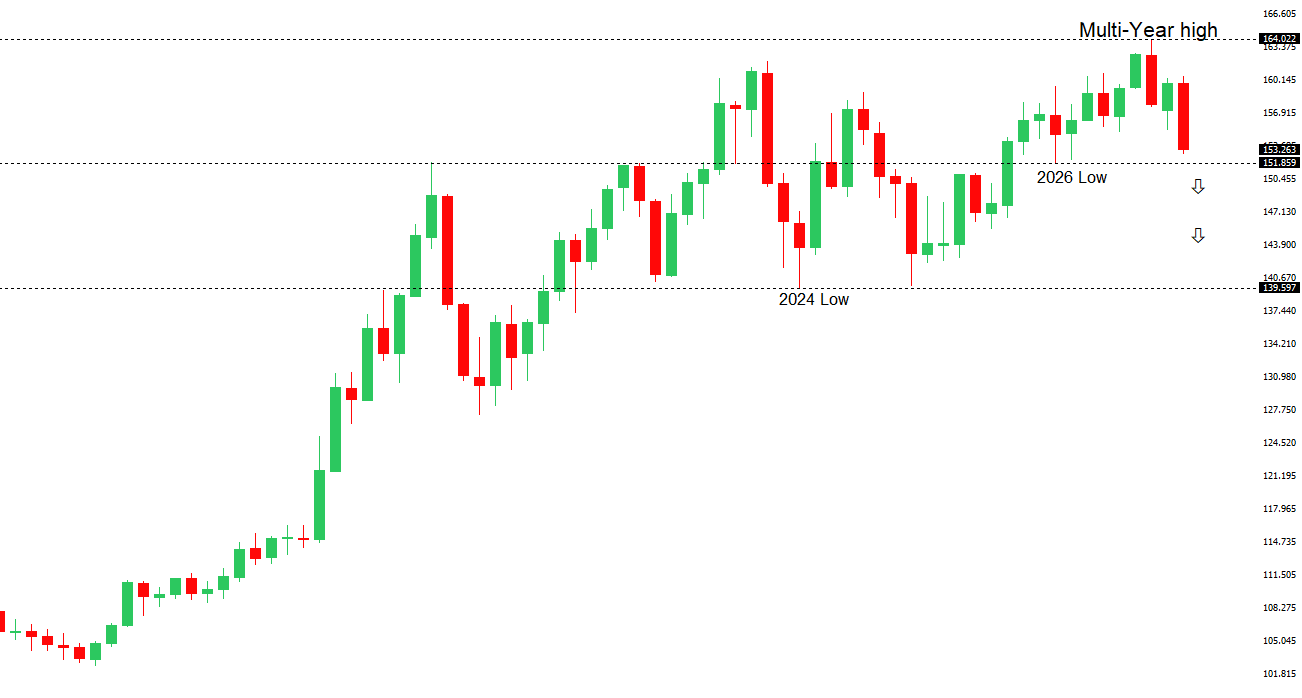
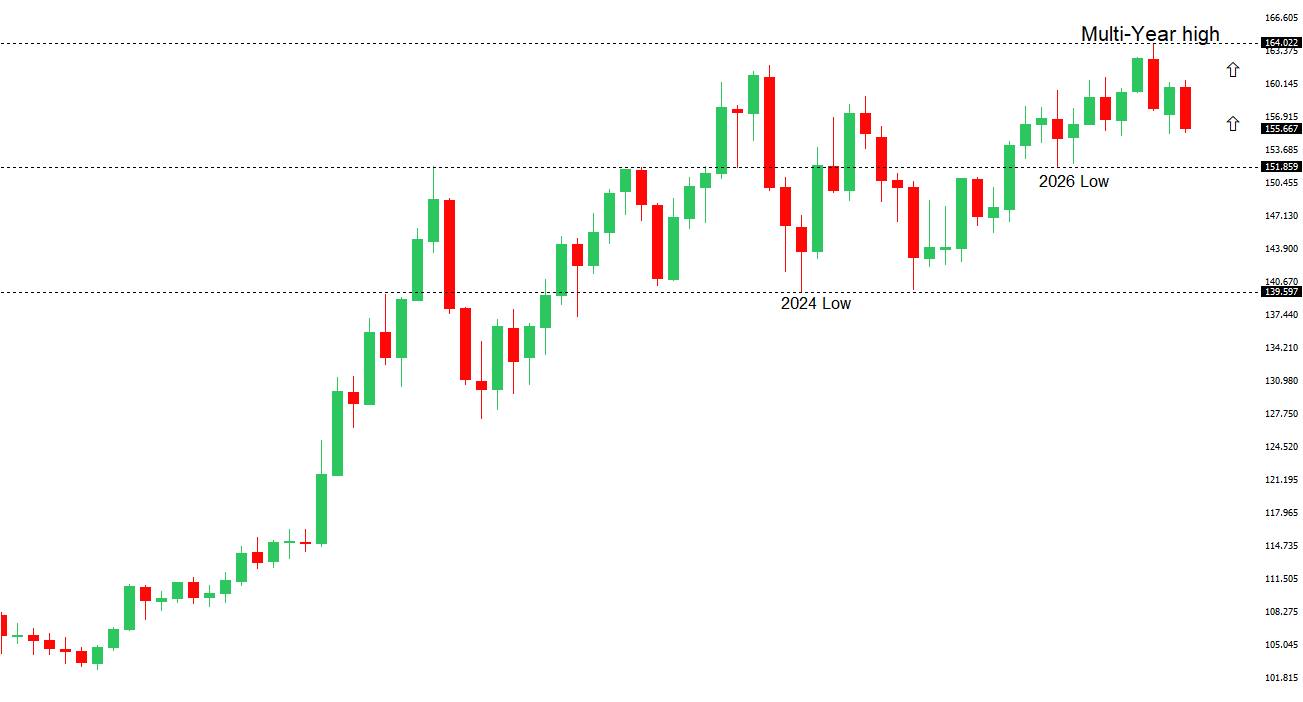
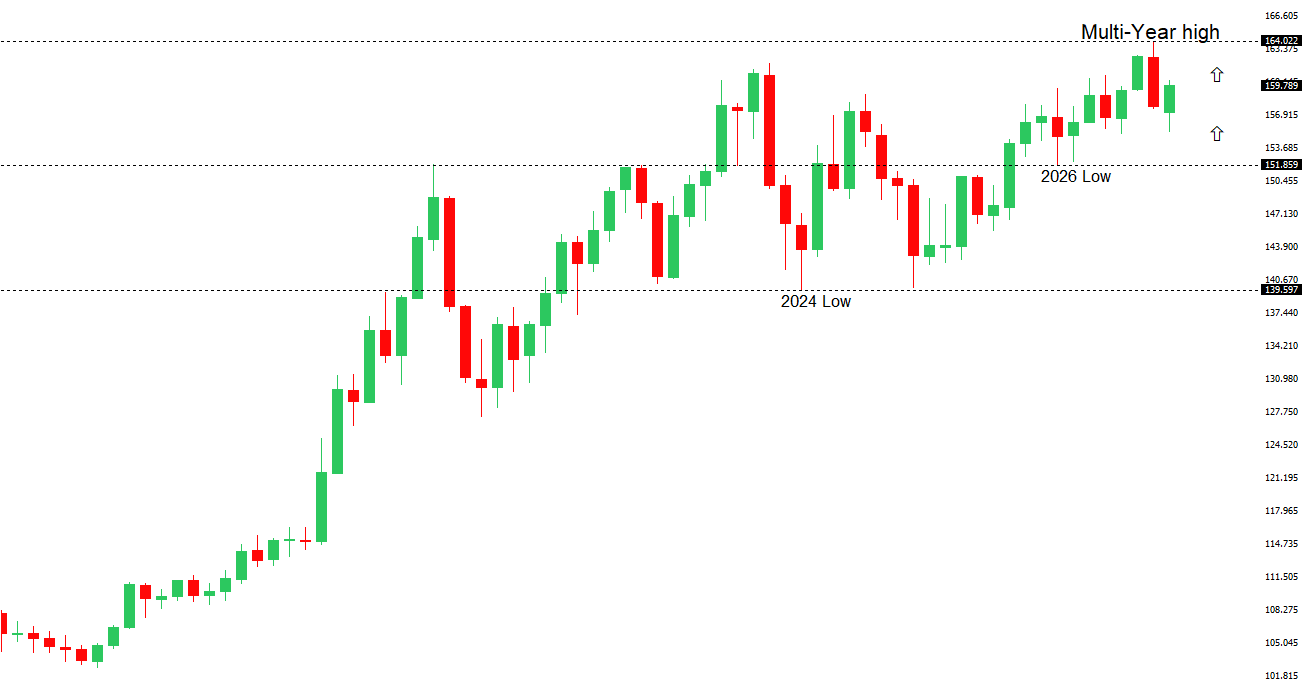
The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58.  The market would need to get back above 160.00 to take the immediate pressure off the downside.

USDJPY Chart
R2 156.75 - 4 September high - Strong
R1 154.68 - 10 September high - Medium
S1 152.88 - 8 September low - Medium
S2 151.97 - 28 January/2026 low - Strong
USDJPY: fundamental overview

The yen has edged lower against the dollar at the start of the week as firmer expectations for a Federal Reserve rate hike and escalating Middle East tensions support the greenback through higher US yields and safe-haven demand. Still, the Japanese currency remains close to a seven-month high, underpinned by a sharp hawkish repricing of the Bank of Japan outlook. Markets broadly expect the BoJ to raise rates later this week and will be focused on whether officials signal a faster pace of tightening, potentially including another move in December, as underlying inflation approaches target and policy remains below neutral. With both central-bank decisions approaching, USDJPY remains caught between near-term dollar strength and the prospect of a further narrowing in US-Japan rate differentials.

 
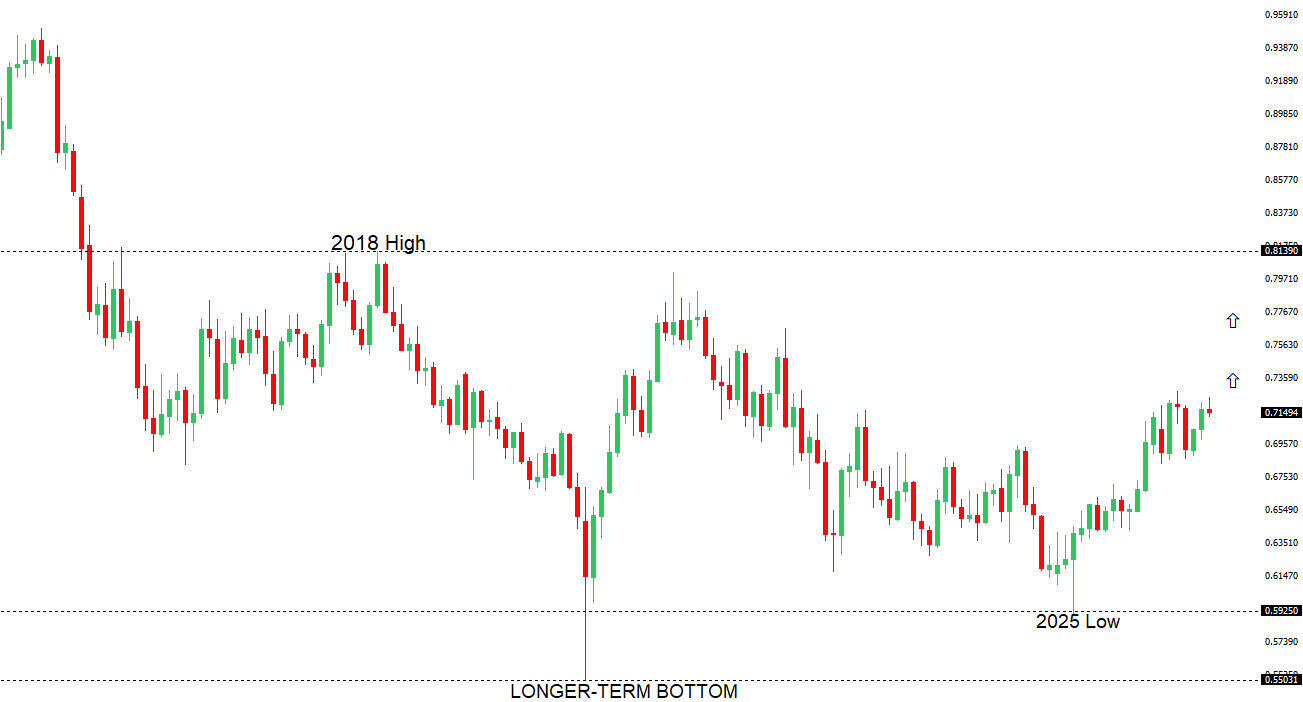
AUDUSD: technical overview

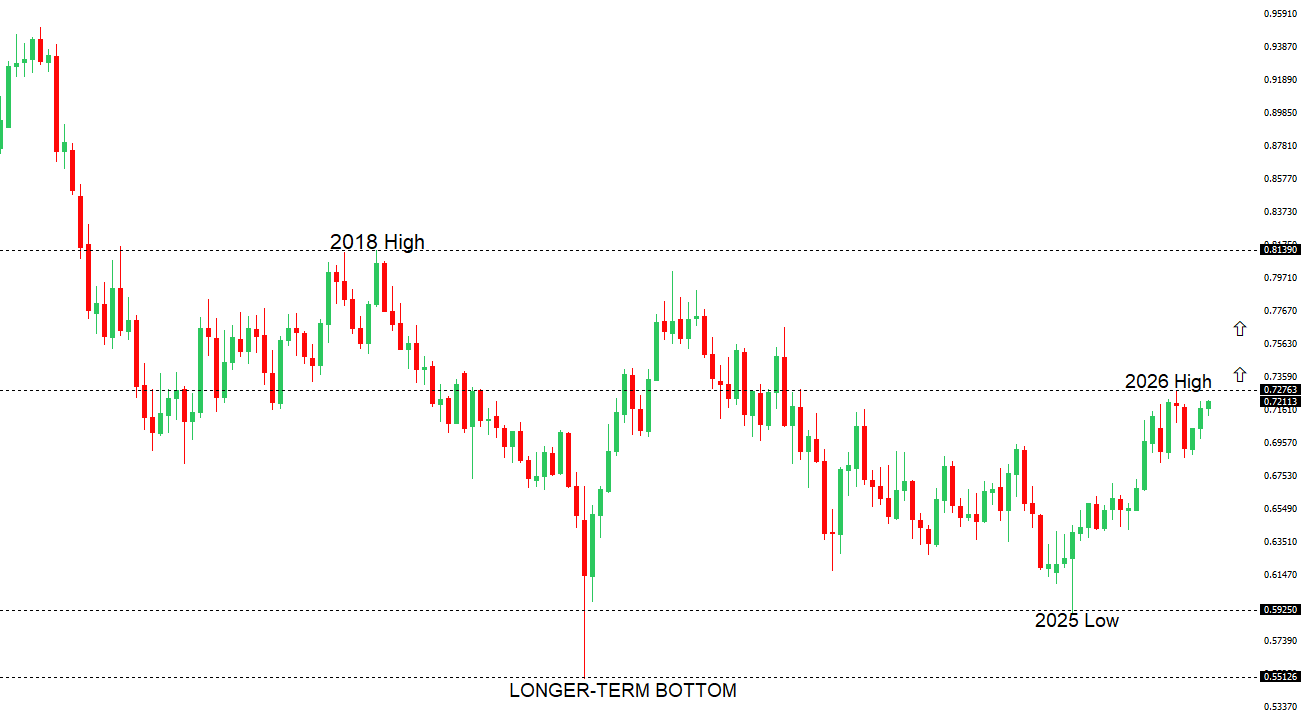
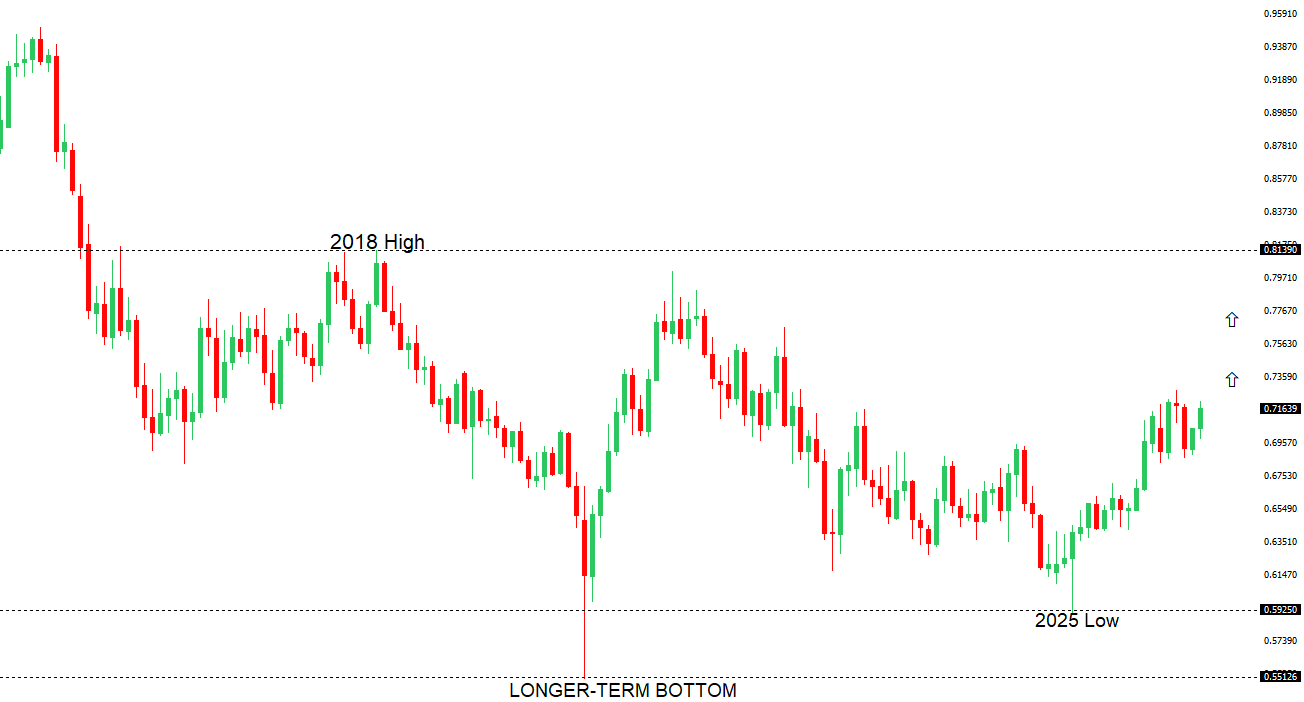
There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7278 - 6 May/2026 high - Strong
R1 0.7238 - 9 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has started the week on the defensive as rising expectations for a Federal Reserve rate hike, elevated US yields and renewed Middle East tensions support the US dollar and weigh on risk-sensitive currencies. Higher oil prices are also unsettling global markets, although the Aussie’s losses have been limited by increasingly hawkish RBA expectations after recent Australian inflation data showed persistent underlying price pressures. The prospect that higher fuel costs could keep domestic inflation elevated has reinforced the case for further RBA tightening, providing an important counterweight to softer consumer sentiment and broader risk aversion. Near-term direction will largely hinge on the Fed decision and upcoming Australian employment data, with the policy outlook on both sides of the pair remaining the dominant driver.

 
Suggested reading

How To Protect Your Nest Egg With Inflation Ballooning, J. Zweig, WSJ (September 11, 2026)

Why Higher Bond Yields Can Be ‘a Great Thing’, S. Hansen, Morningstar (September 10, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
11th September 2026 | view in browser
Crude realities confront global markets

Markets enter Friday in a defensive mood as escalating Middle East tensions and surging oil prices drive yields and the dollar higher, pressure global equities and leave investors focused on US inflation data.


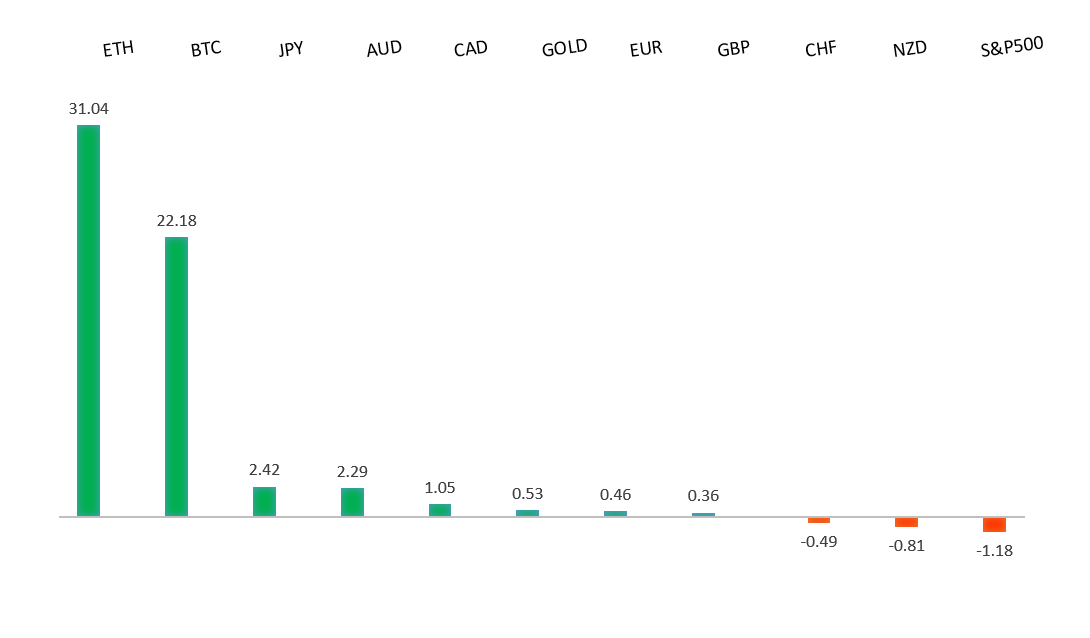
Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro is holding broadly steady after the ECB delivered a widely expected quarter-point rate hike and maintained a hawkish bias, warning that the Middle East-driven energy shock will keep inflation above target for an extended period. The ECB also raised its growth forecasts, highlighting the euro-area economy’s resilience, while upward revisions to the inflation outlook reinforced expectations that further tightening may be required. However, the currency has received only limited support because stronger US producer inflation has increased expectations for a Federal Reserve rate hike, supporting the dollar ahead of today’s critical US CPI release. A softer inflation print would likely favor the euro by tempering Fed tightening bets, while another upside surprise could strengthen the dollar and keep EURUSD under pressure.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3568 - 9 September high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound is holding broadly steady around 1.3500 against the dollar, caught between expectations of further Bank of England tightening and renewed support for the greenback from firm US inflation data. Rising energy costs and persistent UK inflation have encouraged markets to price another BoE rate increase before year-end, although Governor Andrew Bailey has pushed back against the idea that tightening is inevitable, stressing that policy will depend on incoming economic data and geopolitical developments. Attention now turns to US CPI, which could strengthen the dollar if inflation surprises higher, while upcoming UK growth, employment and inflation figures will shape expectations ahead of next week’s BoE decision, where a hawkish hold is widely anticipated. Elevated gilt yields and uncertainty surrounding the government’s October budget remain potential constraints on sterling, but the broader trend in sentiment toward the currency remains constructive.

 
USDJPY: technical overview

The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58.  The market would need to get back above 160.00 to take the immediate pressure off the downside.

USDJPY Chart
R2 156.75 - 4 September high - Strong
R1 154.68 - 10 September high - Medium
S1 152.88 - 8 September low - Medium
S2 151.97 - 28 January/2026 low - Strong
USDJPY: fundamental overview

The yen is remains well supported on dips on the back of a sharp hawkish repricing of Bank of Japan policy expectations. Japanese producer inflation remained elevated in August, reinforcing evidence of persistent domestic price pressures and strengthening the case for further tightening. Recent comments from BoJ officials have added to expectations for a rate hike at next week’s meeting, with markets also seeing a strong possibility of another move before year-end. However, yen gains remain constrained by resilient US inflation and growing expectations for a Federal Reserve rate hike, which continue to support the dollar and keep US-Japan rate differentials wide. Attention now turns to the US CPI report, which will determine whether USDJPY extends its recovery or renewed BoJ-driven yen demand takes control.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7278 - 6 May/2026 high - Strong
R1 0.7238 - 9 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has softened, pressured mainly by renewed US dollar strength after hotter US producer-price inflation increased expectations for a Federal Reserve rate hike in September. Attention now turns to the US CPI report, which will be the final major inflation reading before next week’s Fed decision and could determine whether the US dollar extends its advance. Domestic policy expectations remain supportive for the Aussie, however, with RBA officials Sarah Hunter and Andrew Hauser warning that persistent inflation could require additional tightening. Markets are consequently assigning a high probability to an RBA rate increase this month, helping to limit the currency’s downside despite the stronger US dollar backdrop.

 
Suggested reading

The Next Financial Crash: A Scenario, W. Munchau, UnHerd (September 7, 2026)

Are China’s Rare Earths Really a Potent Weapon?, D. Gros, Project Syndicate (September 8, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
10th September 2026 | view in browser
Oil, yields and the return of inflation anxiety

Global markets head into Thursday on a cautious footing as escalating Middle East tensions and rising oil prices fuel inflation concerns, lift bond yields, pressure equities and leave major currencies subdued ahead of the ECB decision and US inflation data.


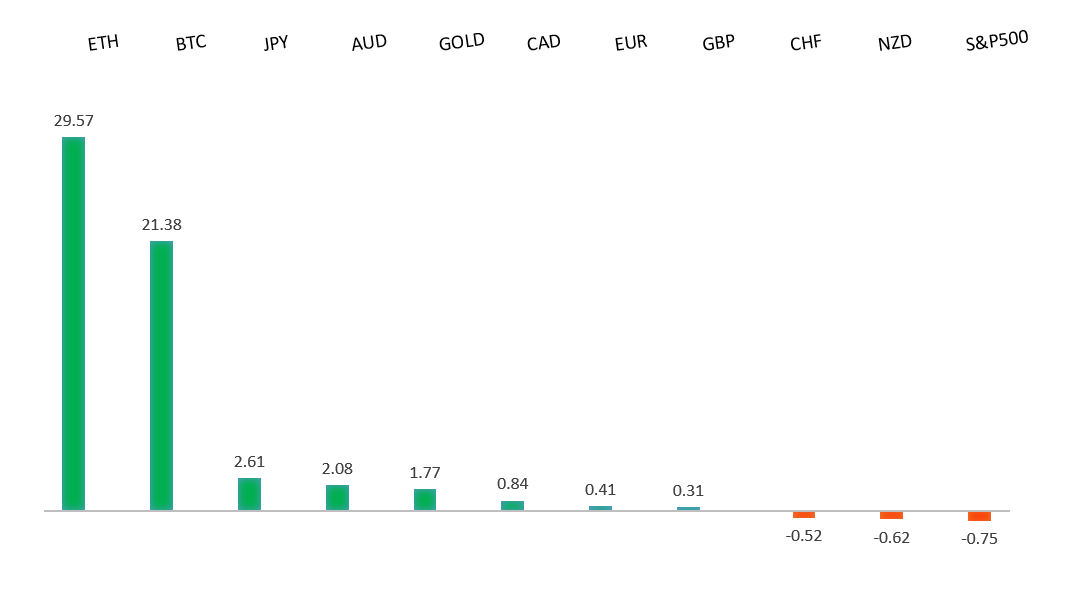
Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro is holding firm above 1.1600 as markets await today’s ECB decision, with a quarter-point rate hike widely expected after surging energy prices pushed Eurozone inflation further above target. The immediate focus will be on the ECB’s updated forecasts and whether President Lagarde signals that persistent inflation risks could justify additional tightening, although concerns about weak regional growth may limit how firmly she commits to further moves. Meanwhile, EURUSD remains sensitive to the US side of the equation, with today’s producer inflation report and Friday’s CPI release set to shape expectations for the Federal Reserve and the broader direction of the dollar.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3568 - 9 September high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound has extended its advance against the US dollar, supported primarily by broad dollar weakness and gradually firming expectations for additional Bank of England tightening later this year. UK housing data offered some encouragement, with the RICS survey reaching a five-month high and pointing to early signs of stabilization, although the recovery remains fragile. Markets expect the BoE to leave rates unchanged at next week’s meeting but are pricing a greater chance of incremental hikes into year-end. Near-term direction remains heavily dependent on upcoming US producer and consumer inflation data, which will shape expectations for the Federal Reserve after strong employment figures boosted the probability of another rate increase.

 
USDJPY: technical overview

The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58.  The market would need to get back above 160.00 to take the immediate pressure off the downside.

USDJPY Chart
R2 156.75 - 4 September high - Strong
R1 154.43 - 8 September high - Medium
S1 152.88 - 8 September low - Medium
S2 151.97 - 28 January/2026 low - Strong
USDJPY: fundamental overview

The yen has eased from a seven-month high against the dollar as traders lock in profits and turn cautious ahead of key US inflation data. The broader fundamental backdrop remains supportive, however, with markets fully pricing a Bank of Japan rate hike in September and assigning a strong probability to another move in December following hawkish signals from policymakers, solid wage growth and an upward revision to Japanese economic growth. Meanwhile, expectations for another Federal Reserve rate hike, elevated energy-driven inflation risks and escalating US-Iran tensions have helped the dollar recover modestly. Even so, the increasingly hawkish BoJ outlook should continue to underpin the yen and limit the scope for a sustained USDJPY rebound.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7278 - 6 May/2026 high - Strong
R1 0.7238 - 9 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has eased up a bit from recent highs as markets turn cautious ahead of key US inflation data, with the upcoming PPI and CPI reports set to shape expectations for next week’s Federal Reserve decision. Strong US employment data has revived the prospect of another Fed rate hike, supporting the US dollar, while escalating Middle East tensions have weighed on risk-sensitive currencies such as the Aussie. Nevertheless, downside pressure remains limited by an increasingly hawkish Reserve Bank of Australia outlook, after officials Sarah Hunter and Andrew Hauser signaled further tightening may be required if inflation remains persistent. This has encouraged expectations for additional RBA rate hikes and continues to provide underlying support for the Australian dollar.

 
Suggested reading

Was Jesus anti-capitalist? | The Story of Money, J. Tett, Financial Times (September 9, 2026)

Down Slightly On a Safe Asset Can Be Jarring, J. Calhoun, Alhambra (September 7, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
9th September 2026 | view in browser
War, oil and the inflation dilemma

Global markets head into Wednesday cautiously as escalating Middle East tensions drive oil higher and weigh on equities, while shifting central-bank expectations support the yen, euro and Australian dollar against a softer US dollar.


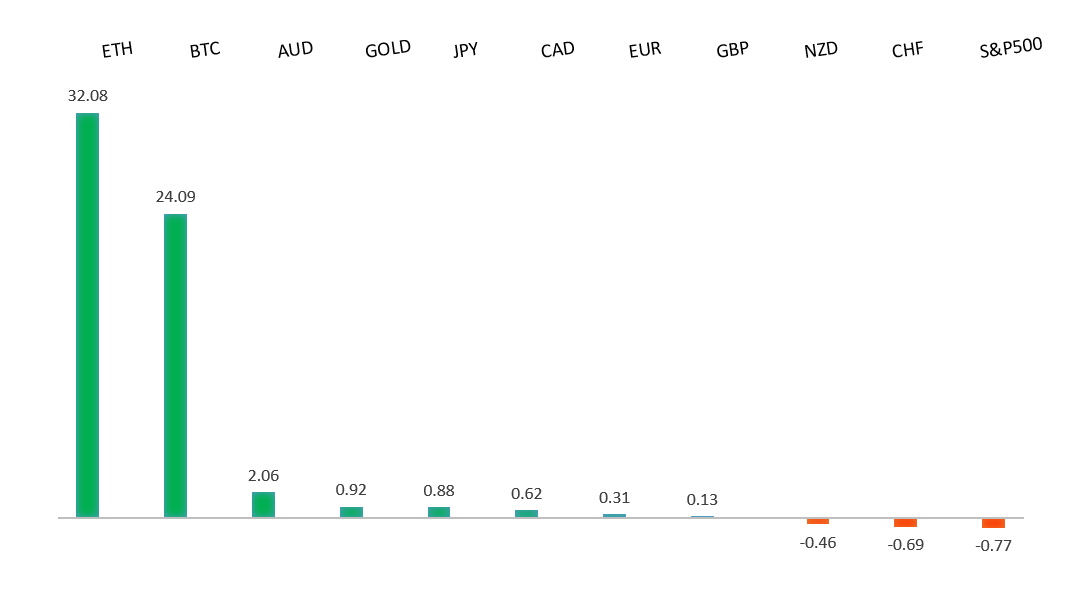
Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro remains well supported, benefiting from broad US dollar weakness and expectations that the ECB will raise rates on Thursday. The anticipated move is largely priced in, leaving the currency’s next direction dependent on the ECB’s updated outlook and whether policymakers signal scope for further tightening as elevated energy prices reinforce inflation risks. Resilient eurozone activity has supported the case for higher rates, although soft German industrial data and concerns about the growth impact of expensive energy are limiting conviction. Meanwhile, the dollar has come under pressure from the sharp yen rally, providing an additional lift to EURUSD, but escalating Middle East tensions and upcoming US producer and consumer inflation figures could revive Fed tightening expectations and cap further euro gains.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3566 - 31 August high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound remains steady against the dollar, supported by broad USD weakness as the BoJ-inspired yen rally weighs on the greenback, alongside the UK government’s emphasis on growth and fiscal discipline. However, sterling’s gains have lacked conviction as traders await monthly UK GDP data for a clearer signal on the domestic economy. Rising expectations for another Fed rate hike and escalating Middle East tensions are also providing some underlying support to the safe-haven dollar, leaving GBPUSD largely range-bound ahead of the UK growth report and key US inflation releases.

 
USDJPY: technical overview

The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58.  The market would need to get back above 160.00 to take the immediate pressure off the downside.

USDJPY Chart
R2 156.75 - 4 September high - Strong
R1 154.43 - 8 September high - Medium
S1 152.88 - 8 September low - Medium
S2 151.97 - 28 January/2026 low - Strong
USDJPY: fundamental overview

The yen has extended its rally to a seven-month high, driven primarily by expectations that the Bank of Japan will raise rates at next week’s meeting following hawkish signals from policymakers. The case for near-term tightening has been strengthened by faster wage growth and an upward revision to second-quarter GDP, while the prospect of a narrower yield gap has encouraged the unwinding of yen-funded carry trades and potential repatriation flows. Lingering intervention concerns and pressure from Washington for a stronger yen have added to the move, although elevated oil prices present a counterweight given Japan’s dependence on energy imports. Attention now turns to US inflation data, with hotter readings potentially reviving Fed tightening expectations and offering the dollar some support against the yen.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7278 - 6 May/2026 high - Strong
R1 0.7231 - 8 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar remains well supported, benefiting from broad US dollar weakness and growing expectations that the Reserve Bank of Australia will raise rates again as resilient economic growth and persistent domestic inflation keep policy risks tilted toward further tightening. Stronger-than-expected Chinese inflation data offered little additional lift, suggesting the latest Aussie strength is being driven more by the RBA outlook and external dollar dynamics than by China-related optimism. The upside has nevertheless been restrained ahead of key US inflation data, with expectations of further Federal Reserve tightening, rising oil prices and escalating Middle East tensions supporting the safe-haven dollar and weighing on broader risk appetite.

 
Suggested reading

How chicken conquered the world, J. Evans, Financial Times (September 8, 2026)

The Market Survived Strong Jobs, Can It Survive Inflation?, A. Rosenberg, Barron’s (September 4, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
8th September 2026 | view in browser
Yen strength and oil risks set the tone

Markets head into Tuesday cautiously as yen strength and shifting central-bank expectations compete with rising oil prices and geopolitical tensions, leaving the dollar softer, US equity futures mixed and gold supported.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro is holding firm above 1.1600, supported by expectations that the ECB will raise rates again on Thursday as elevated energy costs keep inflation risks alive, while stronger-than-previously-estimated euro-area growth has given policymakers more room to tighten. With a quarter-point increase largely priced in, the currency’s next move will depend more on President Lagarde’s guidance and whether the ECB signals that another hike could follow in December. The backdrop is not uniformly positive, however, with weak German industrial production and rising political uncertainty tempering confidence in the region’s outlook. Meanwhile, solid US employment data and this week’s US inflation releases are supporting Fed tightening expectations, while renewed US-Iran tensions and the associated safe-haven demand for the dollar are limiting the euro’s upside.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3566 - 31 August high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

Sterling has edged higher against the dollar, supported by Chancellor Healey’s commitment to fiscal discipline and proposals to boost private investment through regional devolution, regulatory reform and lower business costs. However, the measures largely extend existing policy and have provided only modest support, with investors still concerned about strained public finances, elevated borrowing costs and the difficult choices facing the government in its October budget. The pound continues to benefit from expectations that persistent inflation could keep the Bank of England in a relatively hawkish stance, although fragile growth and the prospect of tighter fiscal policy argue against an aggressive tightening cycle. Meanwhile, stronger US employment data and increased expectations for a September Federal Reserve rate hike are limiting GBPUSD gains, placing greater emphasis on this week’s US inflation releases and Friday’s UK GDP report.

 
USDJPY: technical overview

The recent breakdown below 155.00 suggests the market could be on the verge of a bigger structural shift, with the possibility for an end to a longer-term uptrend and the start to a period of persistent weakness. Critical support now comes in the form of the 2026 low from January at 151.97, with a drop below to strengthen the bearish outlook and open the door for a major downside extension targeting the 2024 low at 139.58.  The market would need to get back above 160.00 to take the immediate pressure off the downside.

USDJPY Chart
R2 156.75 - 4 September high - Strong
R1 154.38 - 8 September high - Medium
S1 152.88 - 8 September low - Medium
S2 151.97 - 28 January/2026 low - Strong
USDJPY: fundamental overview

The yen has rallied to its strongest level since February, driven by a sharp unwinding of short-yen and carry-trade positions as investors price in faster Bank of Japan tightening. Japanese real wages recorded their strongest annual increase since 2021, while second-quarter growth was revised higher, reinforcing expectations that the BoJ will raise rates next week and may continue tightening thereafter. Speculation over capital repatriation by Japanese investors and the authorities’ demonstrated willingness to support the currency through intervention have added momentum to the move. Meanwhile, broad dollar weakness ahead of key US inflation data has outweighed support from hawkish Fed expectations and geopolitical tensions, intensifying the decline in USDJPY.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7278 - 6 May/2026 high - Strong
R1 0.7225 - 7 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has steadied after four consecutive sessions of gains, with China’s broadly in-line trade figures offering little fresh direction despite continued strength in exports. Domestically, a sharp deterioration in consumer confidence has weighed on sentiment, reflecting concerns over elevated interest rates, rising fuel costs, housing-market weakness and job security. Nevertheless, expectations that persistent inflation could force the RBA to tighten policy again, alongside Australia’s recent stronger-than-expected growth data, continue to provide underlying support. The Aussie has also benefited from broader US dollar weakness, although stronger US employment data and rising expectations for a September Fed rate hike are limiting further upside ahead of this week’s key US inflation releases.

 
Suggested reading

A Case That the Jobs Report Is Actually Good for Bonds, B. Arends, Marketwatch (September 5, 2026)

The Fed Doesn’t ‘Print,’ and the Government Doesn’t “Spend”, J. Tamny, Forbes (September 6, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
7th September 2026 | view in browser
Thin holiday trade masks a busy macro week

Global markets open the week cautiously as strong US payrolls revive Fed hike expectations, escalating US-Iran tensions lift oil, and the Labor Day holiday leaves trading conditions thin.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has been trading steadily around, with softer European growth signals offset by a more supportive ECB policy outlook and the dollar’s inability to sustain its post-payroll gains. German industrial production fell 1.1% in July against expectations for a 0.1% increase, driven by a partly temporary 9.2% slump in auto production, although weakness was broader, with capital and consumer goods output also declining. Excluding energy and construction, production fell 2.2%, but the three-month trend remained slightly positive, suggesting weakness rather than a fresh industrial collapse. Meanwhile, elevated energy prices are creating growth headwinds while also keeping inflation pressures high, reinforcing expectations for a 25-basis-point ECB rate hike on Thursday. The focus will be on President Lagarde’s guidance and whether the ECB leaves the door open to further tightening, while Friday’s US CPI report will be critical for determining whether stronger payrolls translate into a September Fed hike.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3566 - 31 August high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound has remained under modest pressure against the dollar, with GBPUSD struggling around 1.3500 as the greenback retains support from stronger-than-expected US payrolls and rising expectations that the Federal Reserve could raise rates in September. Escalating US-Iran tensions and associated energy-price risks have reinforced demand for the safe-haven dollar, while also posing a potential inflationary headwind for the UK economy. Sterling’s downside has nevertheless been limited by the Bank of England’s relatively hawkish stance and the absence of a clear domestic catalyst. Attention now turns to US inflation data for direction on Fed policy, followed by Friday’s UK monthly GDP report for a clearer reading on British growth and the BoE outlook.

 
USDJPY: technical overview

The major pair has entered a period of correction and consolidation after extending its run to fresh multi-decade highs at 163.99. Setbacks are now expected to be well supported around 155.00, with only a weekly close below to compromise the bullish structure.

USDJPY Chart
R2 158.02 - 20 August low - Strong
R1 157.00 - Figure - Medium
S1 155.29 - 4 September low - Medium
S2 155.00 - Figure - Strong
USDJPY: fundamental overview

The yen is consolidating near 156 against the dollar after outperforming sharply last week, with USDJPY falling from around 160 to 155.29. The move was driven primarily by a hawkish shift in Bank of Japan expectations after board member Takata left the door open to larger or back-to-back rate hikes, reinforcing speculation that the BoJ could tighten more aggressively as inflation pressures persist. Expectations for a September rate increase, potential capital repatriation and lingering intervention concerns have further discouraged yen-funded carry trades, although stronger US payrolls and renewed Fed tightening expectations have limited the yen’s advance. Attention now turns to Friday’s US CPI report, which will shape the US-Japan yield differential and likely determine whether the yen can extend its recovery.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7222 - 17 April high - Medium
R1 0.7218 - 7 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar remains well supported near 0.7200, close to its strongest level since mid-May, as resilient domestic fundamentals reinforce expectations that the RBA may raise rates again. Stronger-than-expected second-quarter growth, firm household spending and persistent underlying inflation have increased the probability of a September hike, while elevated energy prices add to Australia’s inflation risks. The Aussie’s upside has nevertheless been contained by renewed Fed tightening expectations following the stronger US payrolls report, rising US yields and safe-haven dollar demand amid escalating US-Iran tensions. Attention now shifts to US inflation data, which will be critical in determining whether the Fed-RBA policy outlook continues to support AUDUSD or allows the dollar to regain momentum.

 
Suggested reading

AI’s Biggest Breakthrough Is 80% Here– Here’s How to Play It, E. Fry, InvestorPlace (September 4, 2026)

Why I Am So Bullish Gold, V. Katsenelson, The Intellectual Investor (September 3, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
4th September 2026 | view in browser
Payrolls loom as Fed uncertainty drives markets

Global markets head into Friday’s US payrolls report in a cautiously constructive mood, with softer Fed rate-hike expectations weighing on the dollar and yields, supporting equities and gold, while elevated oil prices and Middle East tensions keep inflation and geopolitical risks firmly in focus.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has been steady above 1.1600 against the US dollar, with volatility subdued as markets await the US nonfarm payrolls report for clearer direction on the Federal Reserve’s September policy decision. The single currency has drawn some support from encouraging German factory orders, which rose a stronger-than-expected 2.5% in July, while expectations that the ECB remains prepared to tighten further are also helping underpin the euro. However, upside momentum has been limited by reluctance to sell the dollar ahead of payrolls and next week’s more decisive US inflation data. Attention now turns to Eurozone retail sales and comments from ECB Chief Economist Philip Lane, although the broader direction for EURUSD will likely depend on whether incoming US employment and inflation figures revive or further unwind expectations for a September Fed rate hike.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3566 - 31 August high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound has regained some ground above 1.3500, supported by a more hawkish Bank of England policy outlook after Chief Economist Pill argued for an early rate increase to prevent inflation from remaining above target. Pill’s preference for raising Bank Rate to 4% reinforces expectations that the BoE could tighten further, with markets assigning only a modest probability to a September move but a much stronger chance of an increase by November. Still, his insistence that an initial hike need not begin a prolonged tightening cycle has tempered the boost to sterling, particularly given uncertainty surrounding the Middle East conflict and its implications for energy prices and growth. With the UK calendar relatively quiet, GBPUSD direction now rests largely on the US August employment report, where a strong result could revive Fed tightening expectations and dollar demand, while a softer payrolls print would give the pound more room to extend its recovery.

 
USDJPY: technical overview

The major pair has entered a period of correction and consolidation after extending its run to fresh multi-decade highs at 163.99. Setbacks are now expected to be well supported around 155.00, with only a weekly close below to compromise the bullish structure.

USDJPY Chart
R2 158.02 - 20 August low - Strong
R1 157.00 - Figure - Medium
S1 155.29 - 4 September low - Medium
S2 155.00 - Figure - Strong
USDJPY: fundamental overview

The yen has been one of the stronger major currencies this week, supported by a sharp hawkish repricing of Bank of Japan policy expectations, softer US Treasury yields and speculation that Japanese authorities may have intervened to support the currency. Markets have moved to fully price a 25-basis-point BoJ rate hike at the September meeting, with the possibility of another increase in December reinforced by stronger Japanese services activity and persistent price pressures. At the same time, Fed Governor Christopher Waller’s more encouraging comments on inflation have reduced expectations for a September Fed hike, narrowing the relative yield advantage of the dollar. The yen has given back some ground ahead of the US payrolls report as traders reduce bearish-dollar positions, but USDJPY remains on course for a sizeable weekly decline, with the broader fundamental balance continuing to favor the yen unless US employment data materially revives Fed tightening expectations.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7222 - 17 April high - Medium
R1 0.7215 - 4 September high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian Dollar has pushed higher above 0.7200, supported by an increasingly favorable shift in relative rate expectations. Stronger-than-expected Australian second-quarter growth has reinforced the view that domestic demand remains resilient, lifting market pricing for a September RBA rate hike to around 70%. Meanwhile, the US Dollar has lost some ground after Fed Governor Christopher Waller signaled a preference for keeping rates unchanged this month if inflation continues to ease, prompting traders to scale back Fed hike expectations. Australia’s slightly narrower July trade surplus has had limited impact, particularly after an upward revision to June, leaving the RBA outlook as the dominant local driver. Attention now turns to the US employment report, which could determine whether the Aussie extends its gains or faces renewed pressure from a repricing of the Fed outlook.

 
Suggested reading

If You’re Worried About Your Bonds, You’re Missing the Point, C. Benz, Morningstar (September 3, 2026)

Bond Markets Are Losing Patience, P. Earle, The Daily Economy (September 3, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
3rd September 2026 | view in browser
Investors find relief but major event risk ahead

Global markets come into Thursday with a cautiously improved risk tone as oil and bond yields ease, although US-Iran tensions and uncertainty over the Fed outlook continue to drive FX, equities and commodities ahead of Friday’s US jobs report.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1566 - 2 September low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has steadied below 1.1600 against the dollar but remains under pressure as widening rate expectations and geopolitical risks offset increasingly hawkish signals from the ECB. Fed Chair Kevin Warsh’s warning that further tightening may be necessary if inflation does not return convincingly toward target has driven a sharp rise in expectations for a September Fed hike, supporting US yields and the dollar. At the same time, escalating US-Iran tensions and higher oil prices are weighing on the euro through safe-haven dollar demand and renewed concerns over the terms-of-trade impact on the energy-importing eurozone. ECB officials have also kept the door open to further tightening, with Makhlouf warning that rates may need to rise if inflation moves in the wrong direction and Nagel pointing to strong expectations for a September hike. This ECB repricing is providing some underlying support, but for now the dollar’s yield advantage, elevated oil prices and geopolitical uncertainty are keeping EUR/USD gains contained ahead of US ISM Services and Friday’s employment report.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3566 - 31 August high - Medium
S1 1.3474 - 13 August low - Medium
S2 1.3400 - 31 July low - Medium
GBPUSD: fundamental overview

The pound remains under pressure near a three-week low against the dollar, driven primarily by renewed US dollar demand as hawkish Fed expectations and escalating US-Iran tensions reinforce the greenback’s yield and safe-haven appeal. Sterling is also facing domestic headwinds from a sharp rise in UK gilt yields, with higher borrowing costs intensifying concerns over the government’s limited fiscal headroom ahead of the October budget. The Bank of England is expected to leave rates unchanged this month, although persistent inflation and rising energy costs have kept the possibility of another hike later this year alive, providing the pound with some underlying support. For now, however, mixed UK activity data and fiscal uncertainty leave GBPUSD largely dependent on US developments, with the ISM Services PMI and Friday’s employment report set to shape Fed expectations and the pair’s next move.

 
USDJPY: technical overview

The major pair has entered a period of correction and consolidation after extending its run to fresh multi-decade highs at 163.99. Setbacks are now expected to be well supported above 155.00, with only a break below to compromise the bullish structure.

USDJPY Chart
R2 160.40 - 2 September high - Strong
R1 158.97 - 3 September high - Medium
S1 157.95 - 3 September low - Medium
S2 156.67 - 7 August low - Strong
USDJPY: fundamental overview

The yen has been one of the stronger major currencies today, extending its rebound from the 160.00 area as intervention concerns, increasingly hawkish Bank of Japan signals and stronger domestic data reinforce expectations for a rate hike in mid-September. Japan’s services PMI rose to a five-month high of 52.5 in August, while near-record increases in selling prices strengthened the case for further tightening and helped offset the dollar support coming from Fed hike expectations. However, the wider yen outlook remains constrained by the still-large US-Japan interest-rate differential, concerns that rising Japanese bond yields partly reflect fiscal and debt-supply risks, and higher oil prices for energy-importing Japan. Intervention risk should continue to discourage aggressive yen selling near 160.00, but July’s intervention experience suggests official action alone is unlikely to produce a lasting reversal. Near-term direction will now depend heavily on US labor data and Fed commentary, with weak figures potentially extending the yen’s recovery and resilient data threatening a renewed move higher in USDJPY.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7222 - 17 April high - Medium
R1 0.7208 - 28 August high - Medium
S1 0.7121 - 2 September low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has been underpinned by rising expectations that the RBA may need to tighten policy further after hotter-than-expected inflation and stronger second-quarter growth, helping the currency outperform despite a generally firm US dollar. Domestic data offered modest additional support, with Australia’s July trade surplus of A$1.92 billion exceeding forecasts, while China’s services PMI improved to 51.4, although neither release generated a significant market reaction. The upside has remained contained by growing expectations for a September Fed rate hike and escalating US-Iran tensions, which have supported the dollar through higher US yields and safe-haven demand. Attention now turns to the US ISM Services PMI and Friday’s payrolls report, which should help determine whether AUDUSD can extend its recovery or remains capped around current levels.

 
Suggested reading

AI’s Market Path Will Get Bumpier, M. El-Erian, Project Syndicate (September 2, 2026)

When the US stopped backing its money with silver?, G. Tett, Financial Times (September 2, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
2nd September 2026 | view in browser
Dollar gains as risk sentiment deteriorates

Escalating US-Iran tensions are driving oil and bond yields higher, supporting the dollar and weighing on global equities as markets price a growing risk of renewed inflation and further central bank tightening.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1567 - 18 August low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has remained under pressure against the dollar as escalating US-Iran tensions, higher oil prices and rising Treasury yields reinforce safe-haven demand for the greenback and expectations of another Federal Reserve rate hike. The euro’s losses have been limited by a more hawkish ECB outlook after headline Eurozone inflation accelerated from 2.9% to 3.3% in August, strengthening the case for a 25-basis-point rate increase at next week’s meeting, although the decline in core inflation to 2.4% suggests underlying pressures remain better contained. The energy shock is therefore a mixed fundamental for the euro. It supports ECB tightening expectations and European yields in the near term, but also raises concerns about the region’s growth outlook and terms of trade. For now, relative rate expectations and geopolitical demand continue to favor the dollar, with attention turning to this week’s US labor-market data for the next directional catalyst.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3603 - 27 August high - Medium
S1 1.3500 - Psychological - Medium
S2 1.3474 - 13 Augus low - Medium
GBPUSD: fundamental overview

The pound has remained under pressure, as the renewed escalation in US-Iran hostilities has driven demand for the safe-haven dollar and weighed on broader risk sentiment. Sterling has also received limited support from the domestic policy outlook after Bank of England Governor Andrew Bailey said second-round inflation effects remain subdued and pointed to the continued softening in the labor market, suggesting the Bank can afford to monitor the situation rather than respond urgently. Although markets continue to price additional BoE tightening over the coming months, Bailey’s cautious comments have tempered the pound’s relative rate advantage. Near-term direction is likely to remain heavily influenced by geopolitical developments and Friday’s US employment report, which will shape expectations for Federal Reserve policy and the dollar.

 
USDJPY: technical overview

The major pair has entered a period of correction and consolidation after extending its run to fresh multi-decade highs at 163.99. Setbacks are now expected to be well supported above 155.00, with only a break below to compromise the bullish structure.

USDJPY Chart
R2 160.89 - 31 July high - Strong
R1 160.40 - 2 September high - Medium
S1 158.88 - 26 August low - Medium
S2 158.02 - 20 August low - Strong
USDJPY: fundamental overview

The yen remains under heavy pressure, with USDJPY trading above 160 at its highest level since late July. Fiscal concerns have intensified after the global bond selloff pushed Japan’s 10-year yield to 3% for the first time since 1996, raising questions about the cost of servicing the country’s enormous debt burden as the government pursues aggressive investment plans. Expectations for a Bank of Japan rate hike this month have strengthened, helped by mounting pressure from US officials, but this has provided little support given Japan’s persistently wide yield disadvantage and the yen’s continued role as a funding currency. At the same time, renewed expectations for a Federal Reserve rate hike, rising oil-driven inflation risks and escalating US-Iran tensions are supporting the dollar, leaving the yen vulnerable despite growing intervention risk around current levels.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7222 - 17 April high - Medium
R1 0.7208 - 28 August high - Medium
S1 0.7138 - 25 August low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has found support from stronger-than-expected domestic growth data, with the economy expanding 0.4% in the second quarter and annual growth of 2.1% also comfortably beating forecasts. The figures reinforce the view that the Australian economy remains resilient and give the RBA additional room to maintain a restrictive policy stance, particularly with inflation risks still elevated. However, the currency’s gains have been limited by renewed US dollar demand as surging oil prices and rising global bond yields revive inflation concerns and support expectations that US interest rates may remain higher for longer. Mixed US data, including softer JOLTS job openings but a still-expansionary ISM manufacturing reading, has done little to meaningfully weaken the dollar, leaving the Australian currency caught between supportive domestic fundamentals and a more challenging global backdrop

 
Suggested reading

Artificial Intelligence Addicts Won’t Be Better Workers, A. Bhide, Project Syndicate (August 31, 2026)

Can social media bans protect children online?, D. Thomas, Financial Times (September 1, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.

Day Image
1st September 2026 | view in browser
Rising oil and bond yields challenge risk sentiment

Global markets head into Tuesday on a cautious footing as escalating US-Iran tensions drive oil and bond yields higher, revive inflation and rate-hike concerns, support the dollar and weigh on equities, while Eurozone inflation and upcoming US labor data move into focus.


Performance chart 30day v. USD (%)
Performance Chart
 
 
Technical & fundamental highlights
EURUSD: technical overview

The Euro outlook remains constructive with higher lows sought out on dips in favor of the next major upside extension targeting the 2021 high at 1.2350. Setbacks should be exceptionally well supported ahead of 1.1400.

EURUSD Chart
R2 1.1712 - 21 August high - Strong
R1 1.1660 - 27 August high - Medium
S1 1.1567 - 18 August low - Medium
S2 1.1512 - 313 August low - Strong
EURUSD: fundamental overview

The euro has struggled to extend gains as renewed dollar demand, driven by rising expectations for a September Fed rate hike and escalating US-Iran tensions, offsets an increasingly hawkish ECB outlook. Higher energy prices and Germany’s August inflation increase to 2.9% have reinforced expectations that the ECB will raise rates this month, with policymakers warning that persistent energy-driven inflation may require further tightening. This policy support has helped limit euro weakness, but with markets also repricing the Fed in a more hawkish direction, EURUSD remains caught between competing rate-hike expectations. Attention now turns to the preliminary Eurozone inflation reading, followed by key US manufacturing and labor-market data, for clarity on which central bank is likely to pursue the more forceful tightening path.

 
GBPUSD: technical overview

The Pound remains exceptionally well supported on dips into the 1.3000 area, with the price largely consolidating above the psychological barrier and previous resistance turned support in the form of the 2023 high. Look for the market to continue be well supported on dips ahead of the next major upside extension through the yearly high at 1.3870 and towards a retest of the 2018 high at 1.4377 further up. Only a monthly close below 1.3000 negates.

GBPUSD Chart
R2 1.3676 - 21 August high - Strong
R1 1.3603 - 27 August high - Medium
S1 1.3523 - 19 August low - Medium
S2 1.3474 - 13 Augus low - Medium
GBPUSD: fundamental overview

Sterling has come under modest pressure against the dollar, with GBPUSD slipping as Fed Chair Kevin Warsh’s hawkish Jackson Hole message boosted US yields and sharply increased expectations for a September rate hike. At the same time, downside pressure on the pound has been limited by a more constructive Bank of England outlook, with markets assigning around a 60% probability to a 25-basis-point hike at the September meeting and pricing further tightening by year-end. This leaves sterling caught between renewed dollar strength and expectations that UK interest rates may also need to remain elevated, while attention is increasingly turning toward incoming inflation data and the October UK budget for clarity on the country’s fiscal and monetary-policy outlook.

 
USDJPY: technical overview

The major pair has entered a period of correction and consolidation after extending its run to fresh multi-decade highs at 163.99. Setbacks are now expected to be well supported above 155.00, with only a break below to compromise the bullish structure.

USDJPY Chart
R2 160.89 - 31 July high - Strong
R1 160.21 - 28 August high - Medium
S1 158.88 - 26 August low - Medium
S2 158.02 - 20 August low - Strong
USDJPY: fundamental overview

The yen remains under heavy pressure, with USDJPY pushing toward 160.00 despite Japan’s 10-year government bond yield reaching 3% for the first time since 1996. The rise in yields reflects mounting fiscal and inflation concerns, but has not been enough to support the currency as investors remain focused on Japan’s still-unfavorable rate differential with the United States and doubts over how aggressively the Bank of Japan will tighten policy. US Treasury Secretary Scott Bessent’s expectation that Japanese authorities and the BoJ will take action to strengthen the yen has increased attention on the September 18 policy decision, while comments from Japanese officials stressing the importance of orderly currency moves have also revived intervention risk. For now, however, markets appear unconvinced that verbal pressure alone will reverse the yen’s weakness, leaving the currency vulnerable unless the BoJ delivers a clearly more hawkish signal or authorities intervene directly.

 
AUDUSD: technical overview

There are signs of the formation of a longer-term base with the market recovering out from a meaningful longer-term support zone. The latest monthly close back above 0.7000 takes the big picture pressure off the downside and strengthens the case for a bottom, with the focus now on a push towards 0.8000. Setbacks should now be well supported ahead of 0.6700.

AUDUSD Chart
R2 0.7222 - 17 April high - Medium
R1 0.7208 - 28 August high - Medium
S1 0.7138 - 25 August low - Medium
S2 0.7067 - 19 August low - Medium
AUDUSD: fundamental overview

The Australian dollar has remained well supported, benefiting from stronger Chinese manufacturing data after the RatingDog PMI rose to 51.5 in August from 50.9, an encouraging signal given Australia’s close trade exposure to China. Domestic data were also mildly supportive, with Australian building approvals falling 3.6% in July, a smaller decline than expected, while annual approvals growth edged up to 9%. However, the currency’s upside has been limited by renewed US dollar demand as hawkish Federal Reserve commentary strengthens expectations for a possible September rate hike. With Fed officials continuing to emphasize persistent inflation and the need for faster progress toward the 2% target, the near-term direction for the Australian dollar remains a balance between improving China-sensitive sentiment and a widening policy advantage in favor of the US dollar.

 
Suggested reading

It’s Not Warsh vs. Bessent, It’s PhD Confusion About Inflation, J. Tamny, Forbes (August 30, 2026)

Sept. Is Coming: So Are False Seasonality Fears, Fisher Investments (August 27, 2026)


Any opinions, news, research, analyses, prices or other information ("information") contained on this Blog, constitutes marketing communication and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Further, the information contained within this Blog does not contain (and should not be construed as containing) investment advice or an investment recommendation, or an offer of, or solicitation for, a transaction in any financial instrument. LMAX Group has not verified the accuracy or basis-in-fact of any claim or statement made by any third parties as comments for every Blog entry.

LMAX Group will not accept liability for any loss or damage, including without limitation to, any loss of profit, which may arise directly or indirectly from use of or reliance on such information. No representation or warranty is given as to the accuracy or completeness of the above information. While the produced information was obtained from sources deemed to be reliable, LMAX Group does not provide any guarantees about the reliability of such sources. Consequently any person acting on it does so entirely at his or her own risk. It is not a place to slander, use unacceptable language or to promote LMAX Group or any other FX and CFD provider and any such postings, excessive or unjust comments and attacks will not be allowed and will be removed from the site immediately.